Returning From Parental Leave Can Be Stressful. How Some Employers Aim to Fix That.
Companies increasingly are creating formal ‘reboarding’ programs to help new parents transition back to work more easily

 5 min
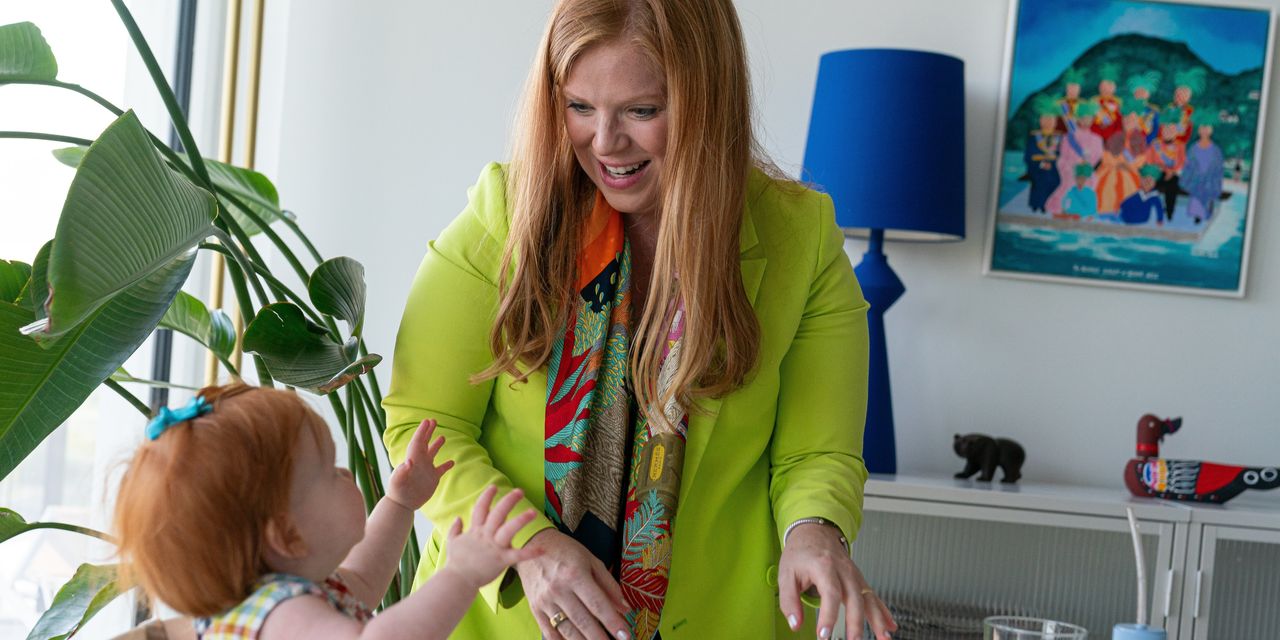
Sarah Tucker-Ray, a partner in McKinsey’s Washington, D.C., office, felt a lot of trepidation when she took a six-month parental leave in 2022.
“There is fear about, ‘Am I going to get written out of the story?’ ” says the 36-year-old Tucker-Ray, whose daughter, Viviana, was born in August 2022. “Is someone going to step in for me and take over? How will I come back?”
She addressed those fears in a reintegration plan that she drafted before going on leave. It included instructions for those who would be covering her workload while she was out, and it laid out what she wanted her job to look like when she returned. For example, Tucker-Ray didn’t want her role to change significantly, but she asked to not be given any internal projects—those focused on McKinsey’s own operations versus those of outside clients—during her first six months back. She also thought about small stuff, such as writing down all of her passwords, and she connected with other working mothers at the company who served as peer counselors before she went on leave.
“They told me that the goal for week one is to get dressed, have breakfast with my baby, get into a suit without getting spilled on and get out the door,” she says. “It sounds so basic but I hadn’t had to do that yet.”
The days, weeks, and months after a new parent returns to work after leave can be a critical and challenging time for an employee. Many experience anxiety about how they are going to manage work and parenting, and some end up feeling like a failure at both.
To address that, some organisations have launched formal “reboarding” programs that structure those first months back after leave so they aren’t overwhelming for new parents, while also providing them with emotional support. McKinsey tested such a program in Europe and then expanded it globally
Many see it as a business imperative. Organisations are making substantial investments in paid maternity and paternity leave—in 2023, 40% of organisations in a Society for Human Resource Management survey offered paid maternity leave and 32% offered paid paternity leave—and they want to ensure new parents return to work and are productive and content when they do.
Creating a plan
A successful reboarding program requires planning, and it and starts long before an employee goes on leave, consultants and HR leaders say. It begins with mapping out a comprehensive work-coverage plan, including if and under what circumstances the employee wants to be contacted about work while out on leave. The plan also should create clear expectations about what the return-to-work will look like, including the employee’s job description post-leave and even an explanation of what that first daunting day back might entail.
Many reboarding programs also connect new moms with experienced working parents or colleagues who have recently returned from parental leaves, as well as a coach (often an outside consultant) who can help set priorities and guidance on best practices.
When Maria del Mar Martinez became head of McKinsey’s diversity, equity and inclusion efforts in Europe in 2018, she learned that working moms left the management-consulting firm at nearly double the rate of their childless female peers with similar tenure. In exit interviews, women shared common grievances, including the challenge of balancing parenthood with a demanding job, a lack of support from their managers and few role models.
She heard similar sentiments in Asia and the U.S.
“That was a business problem,” says del Mar Martinez, now the global head of DEI at McKinsey. “I don’t want to lose those amazing women coming up the pipeline.”
To combat attrition, del Mar Martinez created a reboarding pilot program in Europe that included coaching employees before, during and after a parental leave. (Men are eligible to take part in the program if they have taken 12 weeks or more of leave.)
Built into the plan was a guarantee that new parents would have “meaningful work” upon their return, with the option of slowing down if that’s what they wanted, says del Mar Martinez. One issue, she and others say, is that managers often incorrectly assume that new mothers want lighter workloads or don’t want to travel, which is why it’s important for employees to spell out their preferences in a reboarding plan.
The McKinsey pilot required managers to confirm they understood their employee’s reintegration plan and to calibrate goals in performance reviews to ensure the person taking leave wouldn’t be penalised.
It worked. McKinsey closed the European attrition gap in 18 months, del Mar Martinez says, and later expanded the program globally.
The manager’s role
Other companies are increasing the support they offer to new parents, too, including Wall Street’s Morgan Stanley, which in 2019 appointed Allyson Bronner head of family advocacy at the company’s institutional division, a full-time position that focuses on supporting employees before, during and after parental leaves.
Bronner says one of the best ways to ensure a successful return experience for new parents is to include managers in the process.
To that end, she meets with an expecting employee’s manager between the 25th and 30th week of pregnancy to preview what the employee’s return-to-work will look like and discuss best practices for easing the transition.
“It’s important to set the scene and give them tools to manage their employees,” she says.
She says her next meeting with the manager occurs about a month before the employee is due back to discuss how the first month should be structured. She suggests the manager call the new parent two to three weeks ahead to preview what the first few days back will look like—namely, checking email and showing colleagues baby pictures.
The support continues throughout the first several months, with managers having weekly check-ins with the employee for the first six weeks and then monthly check-ins after that. Bronner encourages managers to ask new parents how they are doing and how their child care is going to determine whether they would benefit from more support or advice in that area.
Since Morgan Stanley created the family advocacy role, “it feels like there has been a culture shift,” Bronner says. “It’s hard to quantify in numbers, but culturally it feels like we’re moving in a more positive direction.”
A culture shift is also under way at chip-equipment maker ASML, which recently expanded the paid parental leave it offers and in May joined forces with employee-benefits firm Parentaly to create a support system for new parents.
ASML is in a male-dominated industry, says Karen Reinhardt, the firm’s chief human-resource officer in the U.S., so retaining women is critical to having a diverse workforce.
As of December, 82 employees had registered for the reboarding program, “more people than we expected,” Reinhardt says.
Among them is Meredith Polm Sheain of San Diego, a knowledge-management developer who went out on maternity leave in late August. In her reboarding plan, she made clear that she wanted to be notified while on leave about any bumps in a recently launched product. She also laid out her priorities for the first two months of her return.
“I felt so much better about the concept of returning to work once I gave my team this plan,” says Polm Sheain, who returned to work on Dec. 22. “I left them and myself in the best position I could.”
Reboarding isn’t the only new benefit companies are offering to make life easier for new parents.
McKinsey’s Tucker-Ray was asked to attend a partner conference in Atlanta about six weeks after returning from maternity leave. The firm covered the cost of her daughter and caregiver (her husband) to join her on the trip since she was still breast-feeding.
“I would have been torn about going away for nearly a week for an internal event but it became a nonevent,” she says. “It got rid of the barrier to feeling you can’t participate fully in parenting and be a leader.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From snow-dusted valleys to festival-filled autumns, Bhutan reveals itself as a rare destination where culture, nature and spirituality unfold year-round.

Formula 1 may be the world’s most glamorous sport, but for Oscar Piastri, it’s also one of the most lucrative. At just 24, Australia’s highest-paid athlete is earning more than US$40 million a year.