The $65 Million Perk for CEOs: Personal Use of the Corporate Jet Has Soared
Company spending on the benefit has climbed 50% since before the pandemic

 5 min
One of the flashiest executive perks has roared back since the onset of the pandemic: free personal travel on the company jet.
Companies in the S&P 500 spent $65 million for executives to use corporate jets for personal travel in 2022, up about 50% from prepandemic levelsthree years earlier, a Wall Street Journal analysis found. Early signs suggest the trend continued last year.
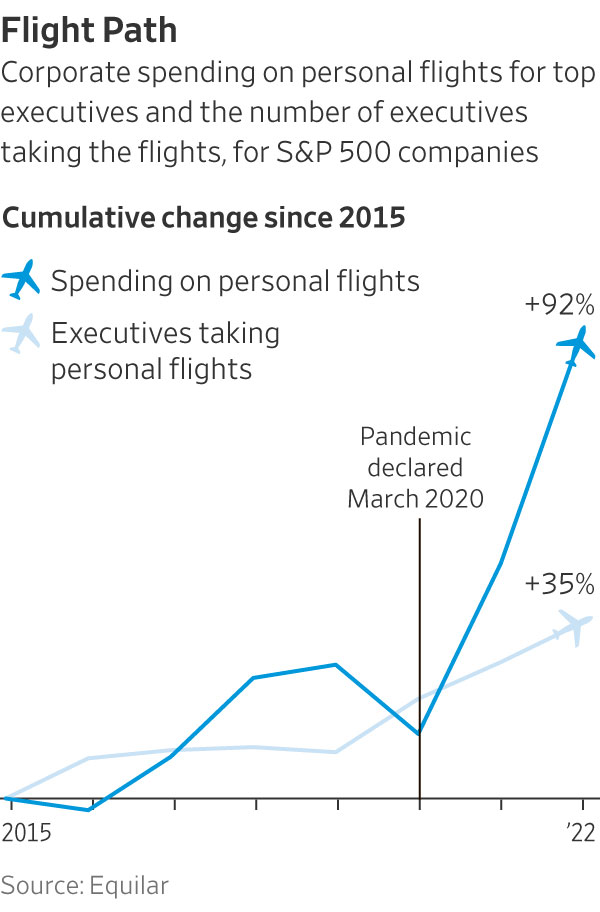
Overall, the number of big companies providing the perk rose about 14% since 2019, to 216 in 2022, figures from executive-data firmEquilar show. The number of executives receiving free flights grew nearly 25%, to 427.
Most companies report executive pay and perks in the spring.
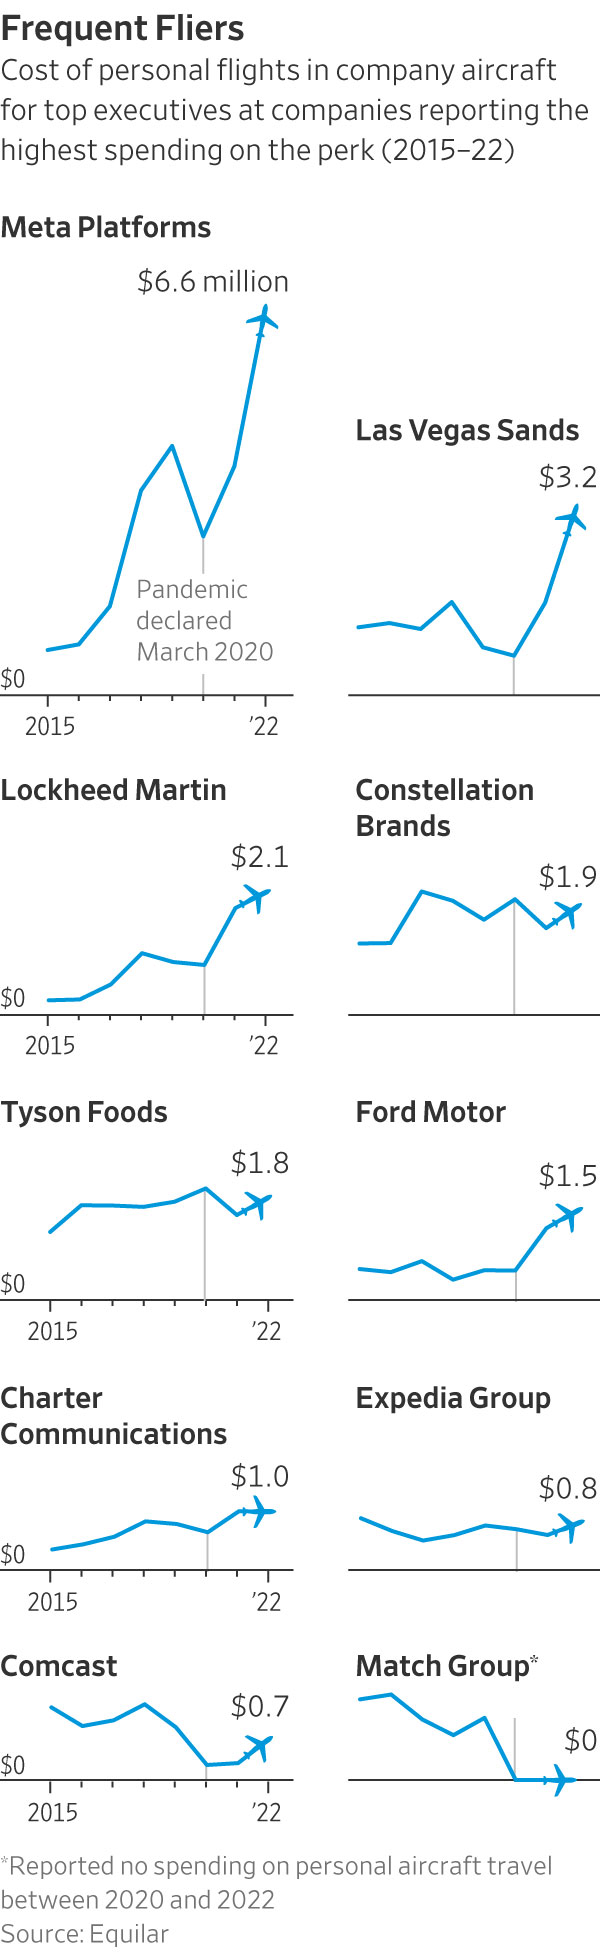
Meta Platforms spent $6.6 million in 2022 on personal flights for Chief Executive Mark Zuckerberg and his then-lieutenant, Sheryl Sandberg—up about 55% from 2019, the Journal found. Casino company Las Vegas Sands spent $3.2 million on flights for four executives, more than double its annual expense in any year since 2015. Exelon, which owns Chicago’s Commonwealth Edison utility, more than tripled its spending on the perk since 2019.
Company jets have long symbolised corporate success and, to critics, excess. Companies typically say flying corporate is safer, healthier and more efficient. Some companies—including Cardinal Health, Raymond James Financial and Hormel Foods—added or expanded the perk in 2020 or 2021, citing pandemic health and safety concerns. Most spending growth came at companies already paying for personal flights in 2019.
Palo Alto Networks began subsidising personal flights for CEO Nikesh Arora in the year ended July 2022, spending about $650,000. That total rose to $1.8 million in its most recent fiscal year, plus a further $286,000 to cover his tax bill for the perk, the cybersecurity company said in an October securities filing.
The company said in filings that its board requires Arora to fly corporate in response to a security consultant’s report. “There was a bona fide, business-related security concern for Mr. Arora and credible threat actors existed with both the willingness and resources necessary for conducting an attack on Mr. Arora,” it said.
Companies report spending on flights they can’t classify as business-related, including trips to board meetings for other companies or commuting from distant residences. Some give executives a fixed personal-flight allowance in hours or dollars, and require reimbursement beyond that.
The sums have little financial impact on most giant corporations, even when annual flight bills exceed a million dollars. Critics say the free flights indicate directors too eager to please top executives.
“The vast majority of S&P 500 companies do not offer this perk,” said Rosanna Landis Weaver, an executive-pay analyst at As You Sow, a nonprofit shareholder-advocacy group that has produced annual lists of CEOs it considers overpaid.
The Journal’s analysis reflects what companies disclose in securities filings, typically in footnotes to annual proxy statements. Federal rules generally require companies to itemize the perk for each top executive if it costs the company $25,000 or more in a year.
PepsiCo spent $776,000 on personal flights for five executives in 2022, double what it paid for the perk in 2019. Two-thirds of the spending subsidized flights by CEO Ramon Laguarta, who is required to use company aircraft for personal flights for safety and efficiency reasons. In an interview last spring, Laguarta said he sometimes ended business trips to Europe by flying to visit his mother in his native Barcelona. She died later in the year, in her 90s.
A PepsiCo spokesman said the company jet allows executives to reach remote facilities.
Personal jet use can draw investor and regulatory scrutiny. It contributed to the ouster of Credit Suisse’s chairman in 2022.
In June, tool maker Stanley Black & Decker settled Securities and Exchange Commission charges that it failed to disclose $1.3 million in perks for four executives and a director, mostly their use of company aircraft, from 2017 through 2020. In 2020, Hilton Worldwide Holdings settled SEC charges that it didn’t disclose $1.7 million in perks over four years, in part by underreporting costs for CEO Christopher Nassetta’s personal flights by 87%in two of those years. Hilton paid a $600,000 penalty.
Both companies settled without admitting or denying wrongdoing.
Stanley Black & Decker said it raised the errors with the SEC and settled without a fine. In 2022, Stanley Black & Decker reported spending nearly $143,500 on personal flights for former CEO James Loree and his successor, Donald Allan Jr., primarily to fly to outside board meetings or from second homes to work.
Hilton cited higher fuel prices in reporting about $500,000 in flights for Nassetta in 2022.
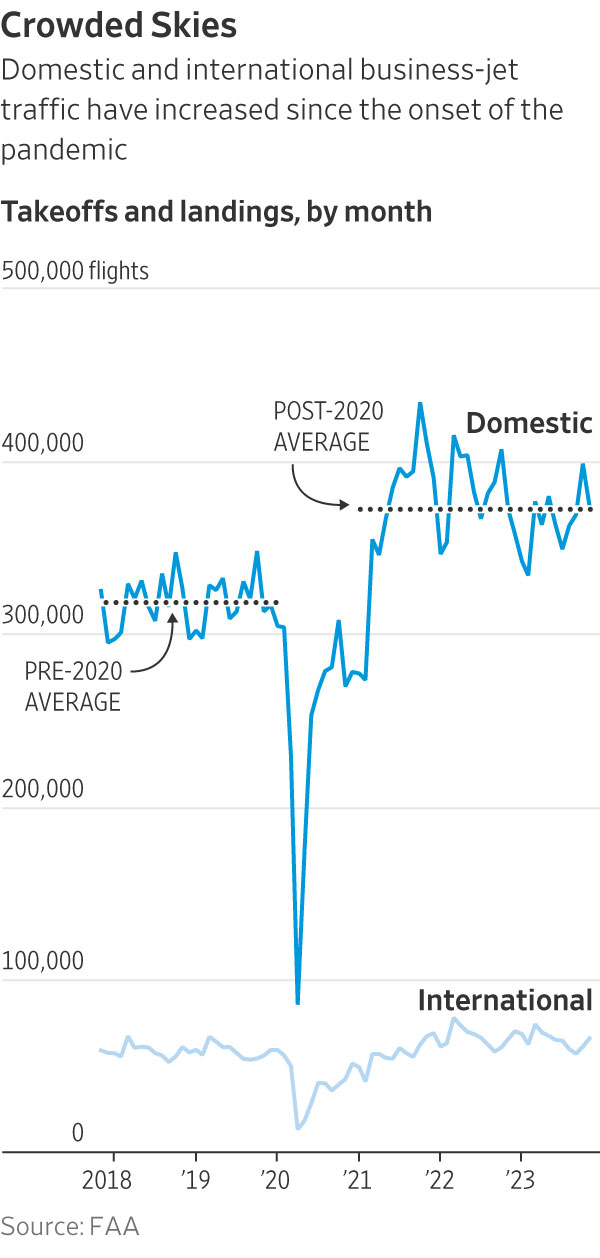
Spending on executives’ personal travel outpaced overall growth in business-jet traffic. Takeoffs and landings are up by about 19% since 2019, after dropping sharply in 2020, Federal Aviation Administration data show. Corporate spending on the perk rose 52%, the Journal found.
Higher fuel costs in 2022 contributed to the increase in spending, and there is little indication of a slowdown last year. Of the 15 S&P 500 companies that have reported spending on the perk in fiscal years ended in the second half of 2023, 10 said they increased spending, including three that didn’t report the perk a year earlier, securities filings show.
Sixteen companies that started paying for personal flights during the pandemic have since stopped. An additional 31 continued spending into 2022, with a median of $124,000. Accenture, Palo Alto Networks and concert promoter Live Nation Entertainment reported spending more than $500,000 apiece.
In 2020, Julie Sweet’s first full year as CEO, Accenture capped annual spending for her personal flights at $200,000, then doubled it the next year. Accenture raised the cap to $600,000 in its year that ended Aug. 31, when it spent about $575,000 on Sweet’s personal flights, the company said in a December securities filing.
In its filings, Accenture said it encourages Sweet to use company aircraft for personal travel, citing a security study the company commissioned.
Companies that provided the perk already in 2019 accounted for most of the recent growth in spending, the Journal found.
Meta, for example, spent nearly $11 million on Zuckerberg and Sandberg’s personal flights from 2015 through 2019, and a further $13.3 million over the next three years. Zuckerberg’s company-paid travel included trips on an aircraft he owns, which Meta charters for business, paying $523,000 in 2022. The Facebook owner stopped paying for Sandberg’s personal flights when she stepped down as a company employee in September 2022. She remains on Meta’s board.
Spokesmen for Meta and Sandberg declined to comment beyond Meta’s securities disclosures.
CEOs incurred most of the personal flight spending, making up half the executives receiving the perk in 2022 and two-thirds of the overall cost, Equilar’s data show.
At some companies, other executives are making up a bigger share of the cost. Four Norfolk Southern executive vice presidents accounted for just over half its roughly $370,000 in spending on personal flights in 2022, securities filings show. CEO Alan Shaw accounted for the rest. By contrast, the railroad reported subsidising flights only for then-CEO James Squires in the five years through 2020.
Shaw may take as many as 60 hours of personal flights on company aircraft before reimbursing Norfolk Southern, the company said in its filings. Personal use of company aircraft by executives other than the CEO was infrequent, it added. Norfolk Southern didn’t respond to requests for comment.
—Jennifer Maloney contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Parts for iPhones to cost more owing to surging demand from AI companies.

From office parties to NYE fireworks, here are the bottles that deserve pride of place in the ice bucket this season.