Why Couture Clients Keep Buying Six-Figure Gowns
How designers brought the antiquated craft of haute couture into the future at the shows in Paris

 3 min
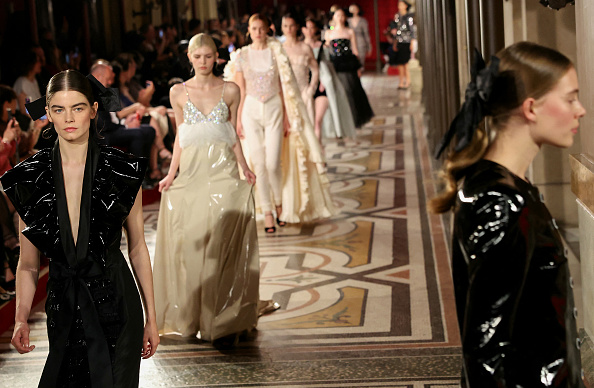
“Nobody really needs couture, to be honest,” said Demna after his Balenciaga haute couture show this week in Paris. No, most people do not need a bespoke gown that costs six figures and takes highly trained petites mains thousands of hours to make by hand. And yet.
Partaking in the official haute couture fashion week in Paris—which is rife with arcane rules about how the clothes are made—can pay off handsomely for the few designers left in the club. For the 15 or so brands that invest in the game, including Dior and Chanel, couture can multiply press and red-carpet opportunities, and have a trickle-down effect on sales of ready-to-wear and beauty and fragrance.
Then there are the orders, which can total in the millions for a single client. Wealthy couture diehards fly in for the shows and then quickly convene in cosseted showrooms to make their selections while munching macarons. Competition can be fierce, especially when a stylist nabs a gown early on for, say, Cardi B. When you’re paying this much to look unique, no one wants a duplicate.
Couture is famously over-the-top, and this season was no exception, with rampant feathered capes, obscuring hoods and trailing trains. But philanthropist, creative director and avid couture client Fredrik Robertsson told me he found the looks very wearable this season: “less PR showstoppers and more things people actually want.” He pointed to the calmer suits and cocktail dresses at Schiaparelli, which has in the past paraded out looks such as one bearing a faux lion’s head .
Couture can sag somewhat under the weight of its history. Craftsmanship, fashion’s favourite buzzword, can be a burden too, with designers feeling the need to embellish every gown with hand-embroidered butterflies and panoplies of pearls. But the following five looks show how a range of designers are making couture relevant today.
Balenciaga’s Sculptural Chaos
Demna, who goes by a mononym, is perhaps the contemporary designer most intent on bringing couture into the future. While he’s never far from Cristóbal Balenciaga’s archive—with its dramatic shapes and volumes—he’s also a student of streetwear. So the subcultures he reveres, from goth to skate kids, were present in his deceptively casual designs. Would the founder of the house turn in his grave at metal-band T-shirts masquerading as couture? Maybe not once he realised they were in fact hand-painted over a period of several days.
This top and skirt ensemble is made from unstitched cotton-jersey elements, which are then assembled and sewn together, and knotted on the model. It is a wearable sculpture, with the casual look of a pile of T-shirts.
Chanel’s Sublime Sweatsuit
Chanel, which is between creative directors after the departure of Virginie Viard, showed its haute couture collection at the Opéra Garnier. While many of the looks echoed the vibe of the classic theatre—including a sumptuous pink silk opera coat—some of the most successful moments were surprisingly dressed down. Robertsson, the Swedish couture client, exclaimed, “Chanel even had sweatpants!”
Shown on model-du-jour Amelia Gray Hamlin, the black Chanel sweatsuit was not technically a sweatsuit. It was a wool crepe jersey set trimmed in duchesse satin ruffles and organza. It was also shown in cream, and it will sell.
Dior’s Deceptively Simple Column
Maria Grazia Chiuri, one of the only female designers making couture, showed an elegantly restrained collection in a room filled with shimmering artwork by Faith Ringgold, who died earlier this year. Nodding to an Olympic year without being too heavy-handed, Chiuri presented Grecian-inspired draped dresses, flat lace-up sandals, and sporty tanks and bodysuits.
This long asymmetrical dress in cream-coloured silk jersey over a tank top is almost sporty, and a refreshing break from some of the more hobbling ensembles on display this past week. But that’s no ordinary tank top: It’s embroidered with silver-colored micro-tube beads that have hematite-clawed jewels on them.
Schiaparelli’s Faux Feathers
Daniel Roseberry, the charming Texan who’s revamped a dusty Parisian couture house, is a true believer in the art of couture. But he’s also savvy about its press potential, so this season, the show didn’t start until paparazzi magnets Kylie Jenner and Doja Cat had arrived.
The house’s founder, Elsa Schiaparelli, was a surrealist innovator who collaborated with her friend Salvador Dalí on one of the first trompe l’oeil garments . Roseberry continues his predecessor’s taste for trickery in his work. This jacket is embroidered all over with what appear to be small white feathers, but are in fact 10,500 silk-organza snippets. Because each “feather” is handmade, the jacket takes over 7,000 hours of work to create. Worn over a pair of smart black cropped pants, it’s almost work appropriate.
Jean Paul Gaultier’s Undressed Dress
Jean Paul Gaultier, which maintains a healthy and bustling couture business, has adopted the clever strategy of inviting buzzy non-couture designers to collaborate on its collections. Simone Rocha, Glenn Martens, Olivier Rousteing and Chitose Abe of Sacai have all worked it out on the remix with Gaultier. Nicolas Di Felice, the artistic director behind Courrèges’s Pinault-backed renaissance, was up this season.
Di Felice, whose friends span Paris’s creative industries, brought his cool-kid approach to Gaultier. Many pieces featured couture details like rows of hook-and-eye closures, and partially hidden tulle corsets. But there were Di Felice signatures, too: koala-pouch front pockets, narrow trousers, tiny party dresses. This cheeky gown is carefully constructed to look like the top slip is falling away to reveal a bustier.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices
Four decks, 34.5 metres and a made-to-measure interior: step aboard the new Custom Line Navetta 35, unveiled at Cannes.