The 7 lasting impacts of COVID for Australian investors
A leading Australian economist says two years on, the long term implications of COVID for the economy have emerged
 3 min
AMP chief economist Dr Shane Oliver says the effects of the pandemic continue to reverberate across the world, with seven key lasting impacts leading to “a more fragmented and volatile world for investment returns”.
“Perhaps the biggest impact is that the pandemic related stimulus broke the back of the ultra-low inflation seen pre-pandemic,” said Dr Oliver. “Together with bigger government and reduced globalisation, this means a more inflation-prone world. So, a return to pre-pandemic ultra-low inflation and interest rates looks unlikely.”
Here is a summary of Dr Oliver’s explanation of the seven key lasting impacts of COVID for investors.
1. Bigger government
The pandemic added to support for bigger government by showcasing the power of government to protect households and businesses from shocks, enhancing perceptions of inequality, and adding support to the view that governments should ensure supply chains by bringing production back home. IMF projections for government spending in advanced countries show it settling nearly 2 percent of GDP higher than pre-COVID levels.
Implications for investors: … likely to be less productive economies, lower than otherwise living standards and less personal freedom.
2. Tighter labour markets and faster wages growth
After the pandemic, labour markets have tightened reflecting the rebound in demand post-pandemic, lower participation rates in some countries and a degree of labour hoarding as labour shortages made companies reluctant to let workers go. As a result, wages growth increased, possibly breaking the pre-pandemic malaise of weak wages growth.
Implications for investors: Tighter labour markets run the risk that wages growth exceeds levels consistent with two to three percent inflation.
3. Reduced globalisation
A backlash against globalisation became evident last decade in the rise of Trump, Brexit and populist leaders …. Also, geopolitical tensions were on the rise with the relative decline of the US and faith in liberal democracies waning ... The pandemic inflamed both with supply side disruptions adding to pressure for the onshoring of production [and] heightened tensions between the west and China … we are seeing more protectionism (e.g.,with subsidies and regulation favouring local production) and increased defence spending.
Implications for investors: Reduced globalisation risks leading to reduced potential economic growth for the emerging world and reduced productivity if supply chains are managed on other than economic grounds.
4. Higher prices, inflation and interest rates
Inflation [due to stimulus payments to households and supply chain disruptions] is now starting to come under control … but the pandemic has likely ushered in a more inflation-prone world by boosting bigger government, adding to a reversal in globalisation and adding to geopolitical tensions. All of which combine with ageing populations to potentially result in higher rates of inflation.
Implications for investors: Higher inflation than seen pre-pandemic means higher than otherwise interest rates over the medium term, which reduces the upside potential for growth assets like shares and property.
5. Worsening housing affordability
… the lockdowns and working from home drove increased demand for houses over units and interest in smaller cities and regional locations. As a result, Australian home prices surged to record levels. Meanwhile, the impact of higher interest rates in the last two years on home prices was swamped by housing shortages as immigration surged in a catch-up. The end result is now record low levels of housing affordability for buyers …
Implications for investors: Ever worse housing affordability means ongoing intergenerational inequality and even higher household debt.
6. Working from home
There are huge benefits to physically working together around culture, collaboration, idea generation and learning but there are also benefits to working from home with no commute time, greater focus, less damage to the environment, better life balance and for companies – lower costs, more diverse workforces and happier staff. So the ideal is probably a hybrid model.
Implications for investors: Less office space demand as leases expire resulting in higher vacancy rates/lower rents, more people living in cities as vacated office space is converted, and reinvigorated life in suburbs and regions.
7. Faster embrace of technology
Lockdowns dramatically accelerated the move to a digital world. Many have now embraced online retail, working from home and virtual meetings. It may be argued that this fuller embrace of technology will enable the full productivity-enhancing potential of technology to be unleashed. The rapid adoption of AI will likely help.
Implications for investors: … a faster embrace of online retailing … at the expense of traditional retailing, virtual meeting attendance becoming the norm for many … and business travel settling at a lower level.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
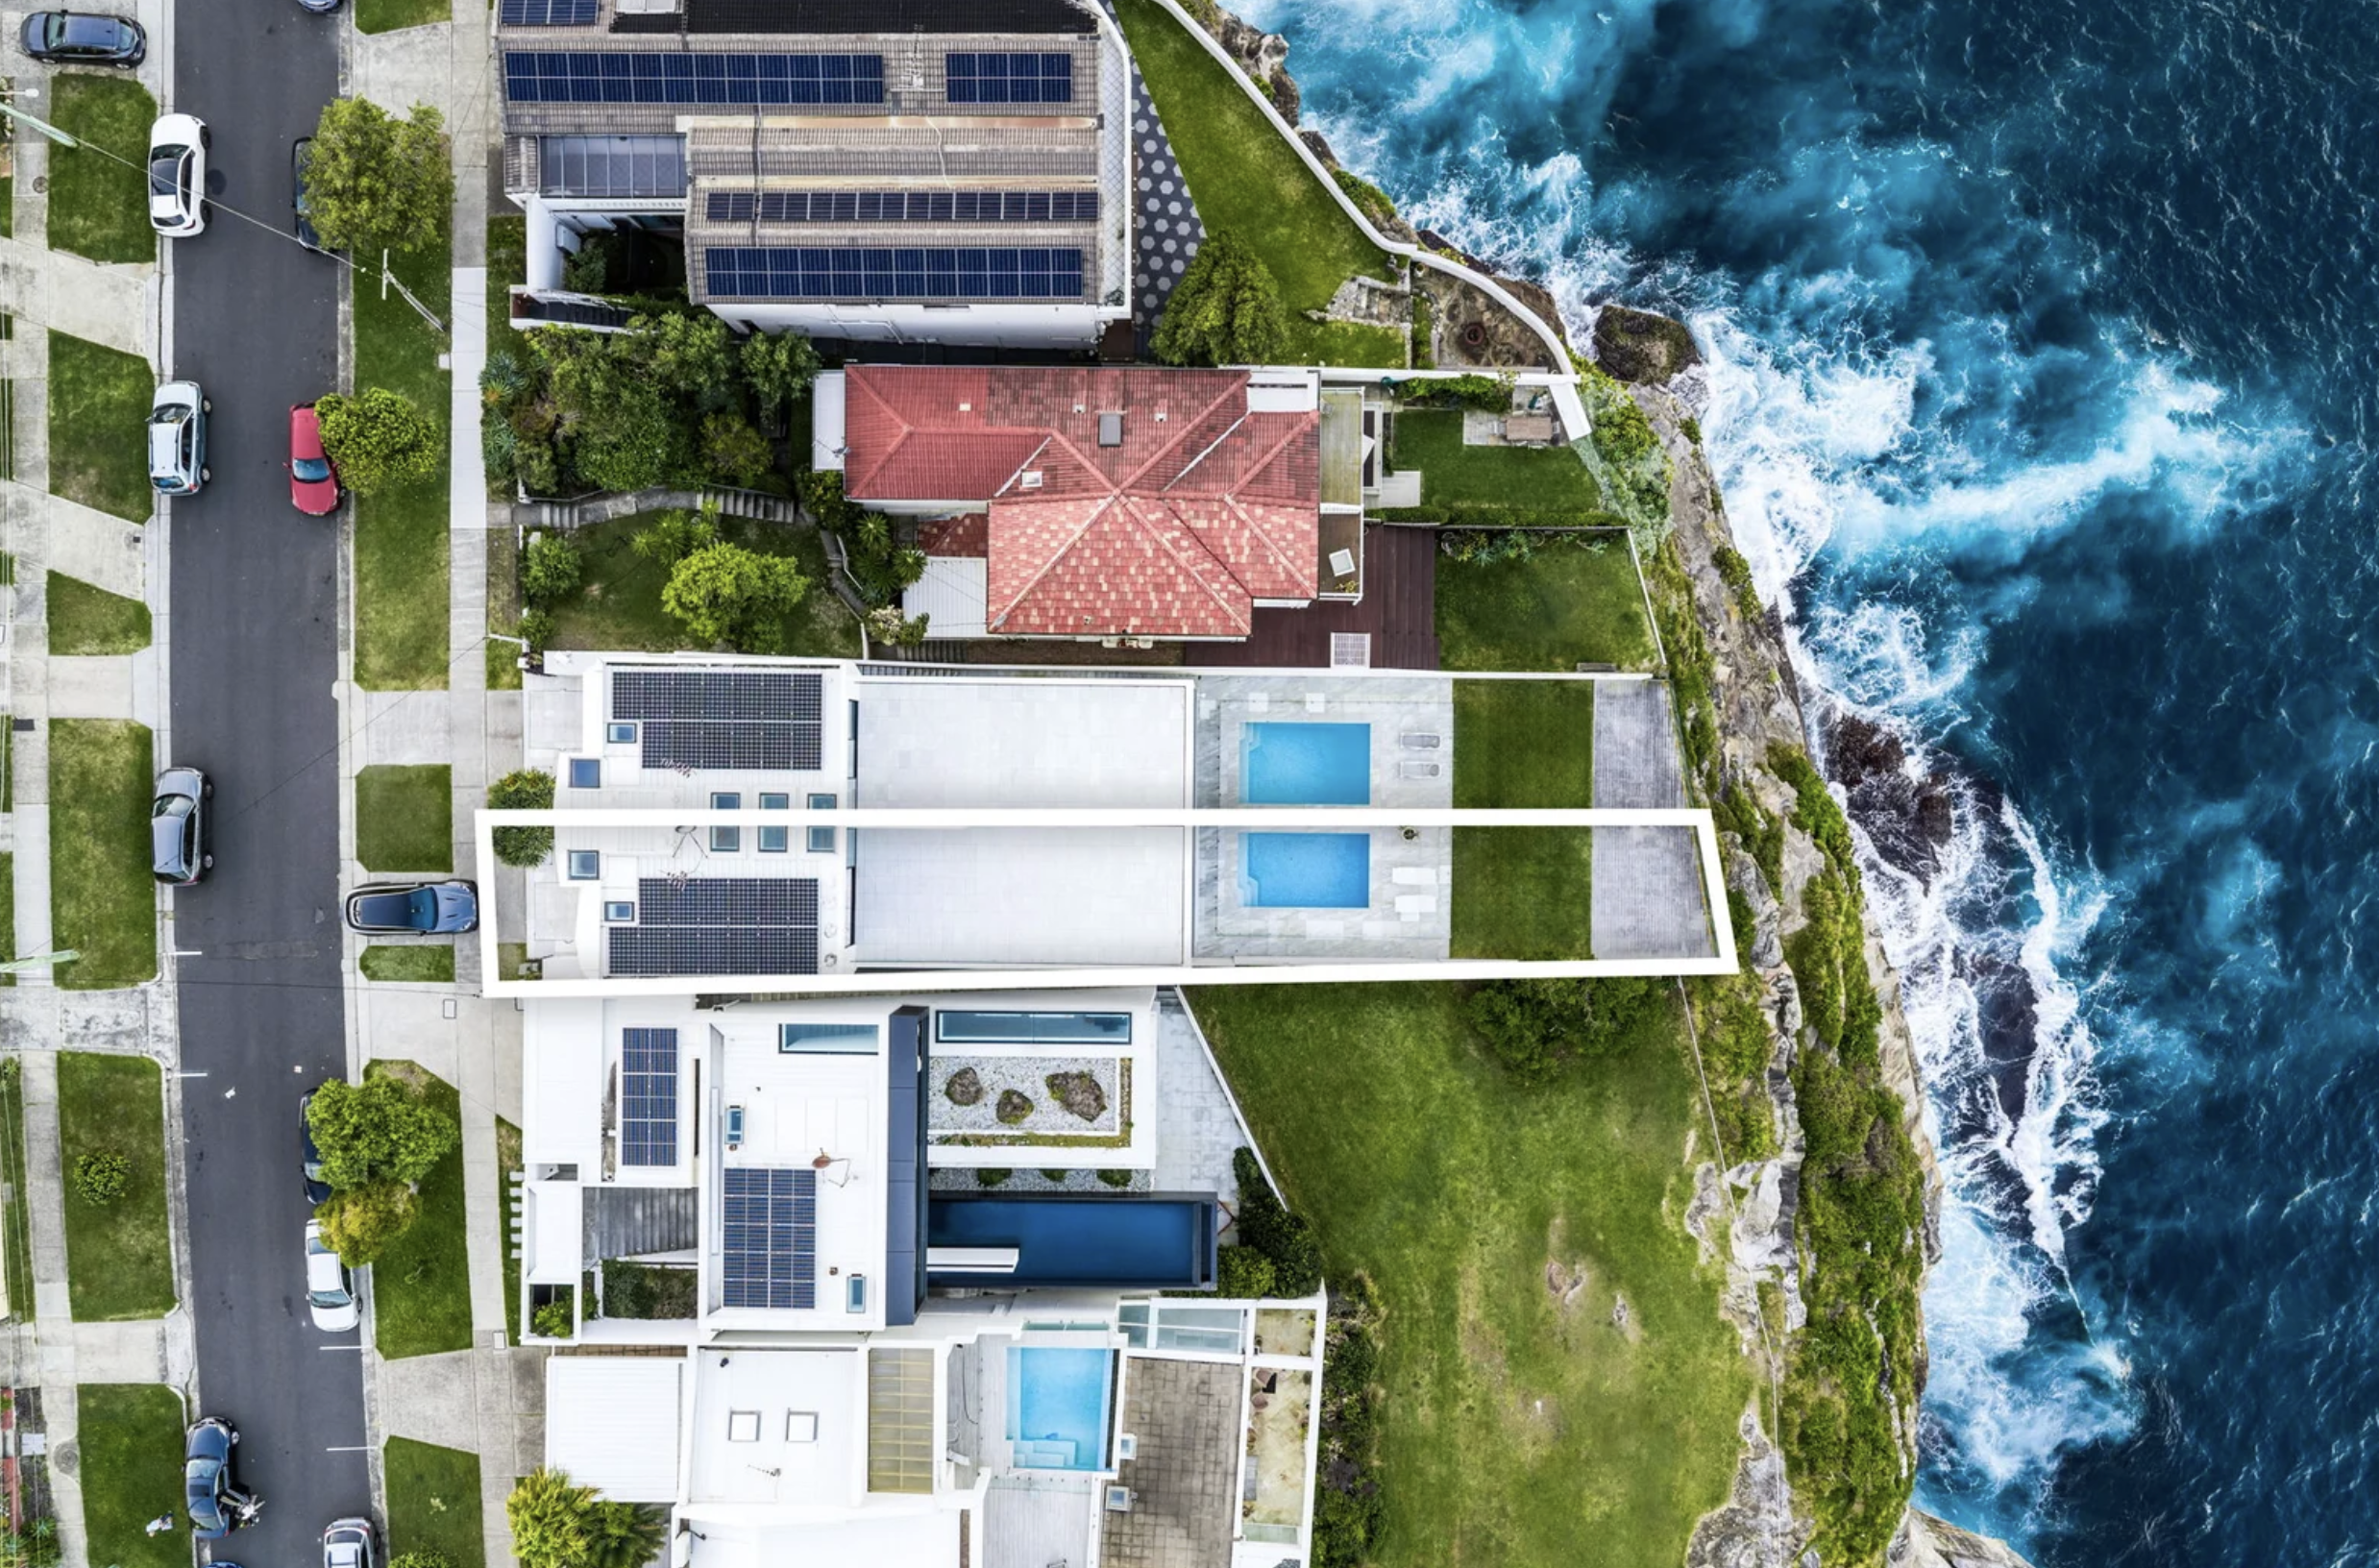
A Vaucluse masterpiece by MHNDU with interiors by Poco Designs brings architectural ambition and breathtaking ocean outlook to the auction block.
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.