The Best Stock Funds of 2023
The ‘Magnificent Seven’ tech stocks helped drive a rebound at many large-cap funds after a dismal 2022. The winner surged 65.2%.

 6 min
Large-cap companies led the way in 2023, benefiting the money managers who believed in them.
Driven by a rebound in large and megacap stocks, in particular the “Magnificent Seven” technology companies, mutual-fund managers who saw double-digit losses in the market rout in 2022 found themselves rewarded for their patience this past year.
Nine of the top 10 stock funds in The Wall Street Journal’s Winners’ Circle survey of mutual funds, which covers the 12-month period ended Dec. 31, are in Morningstar’s large-cap growth category—often with big weightings in outperforming sectors such as technology, communications services and consumer discretionary. Those S&P 500 sectors notched total returns, including dividends, of 57.8%, 55.8% 42.4%, respectively, easily topping the broader market’s 26.3% result.
Still, the Magnificent Seven paced the market. These stocks—Alphabet, Amazon.com, Apple, Meta Platforms, Microsoft, Nvidia and Tesla—all gained more than 48% last year.
Nvidia, whose chips have become synonymous with exploding interest in artificial intelligence, was the biggest winner among those stocks with a gain of 239%. It was followed by Facebook parent Meta at 194% and Tesla at 102%. These were popular holdings among the top-performing funds in the latest survey, though it varied by the individual manager.
Excluding those stocks, the S&P 500’s return was only 9.9%, according to S&P Dow Jones Indices. In other words, the Magnificent Seven accounted for more than half of the index’s 2023 performance and boosted the returns of many funds as well.
Still, there was plenty of good performance across mutual funds, and it wasn’t always contingent on those seven stocks. A rising tide lifts most boats.
Survey parameters
For the latest 12-month period, more than 1,000 of the 1,191 funds tracked in the Journal’s survey made double-digit gains. The average fund returned 19.7%, and only four funds registered declines.
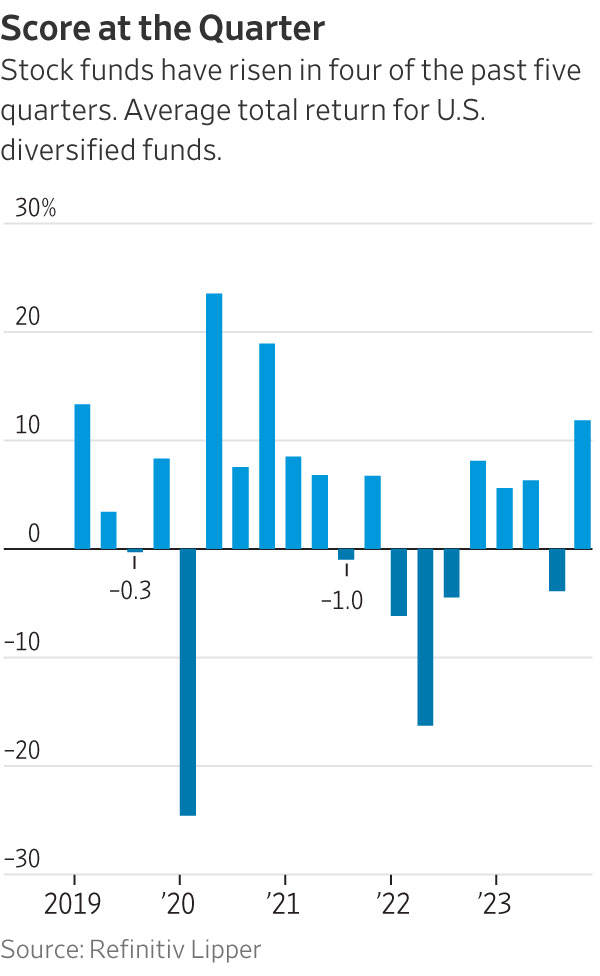
To qualify for inclusion in the Winners’ Circle, funds must be actively managed U.S.-stock funds with more than $50 million in assets and a record of three years or more, as well as meet a handful of other criteria. The survey excludes index and sector funds, funds that employ leverage strategies and most quantitative funds. The results are calculated by Morningstar Direct.
As always, this quarterly competition isn’t designed to create a “buy list” of funds for readers, but to demonstrate the ways that specific investment strategies benefited from recent market trends. Some of the funds that were highlighted a year ago have fallen in the rankings just as growth portfolios have grabbed the limelight—and that phenomenon isn’t uncommon.
Moreover, not all funds cited in these quarterly surveys may be available to investors, and they may have elements that make them unsuitable for some investors, ranging from their fee structure to their longer-term performance or volatility.
Take the latest No. 1 fund, for example. The $500 million Virtus Zevenbergen Innovative Growth Stock Fund (SAGAX) lost 55.4% in 2022 and 10.1% in 2021 as tech stocks tumbled amid the Federal Reserve’s rate-hike campaign and recession worry.
The fund returned 65.2% last year, however, thanks to the big turnaround for the large-cap growth stocks.
Patience paid off
“Markets and management teams spent all of 2022 fearing and preparing for a recession that has so far failed to appear, but that excess pessimism really swung the pendulum too far in terms of market sentiment,” says Joe Dennison, a portfolio manager of the Virtus fund. “That has created some great opportunities for patient long-term investors.”
It holds five of the Magnificent Seven, three of which—Tesla, Nvidia and Amazon—are among its top 10 holdings. Tesla, its largest holding, stands at 7.7% of the fund.
These stocks aren’t new to Dennison and his co-managers. The fund first bought shares of Nvidia in 2017. Its holdings in Tesla and Amazon date to 2010 and 2008, respectively.
Dennison says the biggest contributors to the fund’s 2023 performance besides Tesla and Nvidia were MercadoLibre, an e-commerce company in Latin America, and Shopify, an e-commerce business platform. Those stocks gained 86% and 124% last year, respectively.
The Virtus fund doesn’t shy away from high valuations. As of Dec. 29, the trailing price-to-earnings ratio of stocks it holds was 70.4, excluding negative earnings. This approach, however, can be volatile.
Indeed, Dennison acknowledges “there will be volatility and periods of underperformance,” but he adds that it’s important to focus on longer-term performance and stick with companies that the managers believe in.
Best of the rest
No. 2 in the latest survey, with a return of 59.1%, is the $290 million Value Line Larger Companies Focused Fund (VALLX), which holds all of the Magnificent Seven. They were initially put into the fund before 2023—though it did add to Amazon, Google parent Alphabet, Microsoft and Tesla in the first nine months of last year.
It trimmed its positions in Apple and Meta over that stretch.
The fund’s manager, Cindy Starke, says that 2023 was all about “adding to names that we had more conviction in,” rather than trying to unearth new stocks.
Starke looks for companies she thinks can increase sales at a three-year annualised compound rate of 10% or more and annualised earnings growth of at least 15% for three to five years.
She points out that the fund had broad stock appreciation last year: 25 of the holdings gained at least 50% over the year’s first three quarters. (That fund and others release quarterly holdings with a lag after the quarter ends, but performance is updated daily.)
Besides the Magnificent Seven, the fund’s winners included Uber Technologies, which appreciated 149% in 2023. It was put in the portfolio in the fourth quarter of 2021 and was the fund’s largest holding, at 6.5%, as of Sept. 30. Starke increased her holding in 2023.
When she added Uber to the fund in 2021, she recalls, “I just thought it was very undervalued” and that “the growth model would mature.”
Other top holdings include Nvidia, initially put into the fund in 2018; Microsoft (2020); Alphabet (2011) and Tesla (2021).
Two other big gainers for that fund: Advanced Micro Devices, which leapt 127% last year, and cybersecurity firm CrowdStrike Holdings, which rose 143%.
At the same time, Starke did plenty of selling. She trimmed the fund to 39 names from 47 over the first three quarters of 2023, jettisoning stocks such as Goldman Sachs, Walt Disney, Bank of America, Estée Lauder and Devon Energy. “I just got out of the names that didn’t offer me the same kind of growth opportunity,” she says.
Rounding out the top four funds are the $500 million Baron Fifth Avenue Growth Fund (BFTHX), which returned 57.2%, and the $11 billion Fidelity Blue Chip Growth K6 Fund (FBCGX), up 55.6%.
An outlier
A party crasher at No. 5 is the Morgan Stanley Inception Portfolio (MSSGX)—the lone fund in the top 10 outside of the large-cap growth category.
It toils in small-cap issues, which lagged behind large-caps last year. The Russell 2000 index of small stocks returned 16.9% in 2023, trailing the S&P 500 by nearly 10 percentage points.
But the Inception portfolio punched well above its weight, notching a return of 54.4%.
The fund’s managers aren’t afraid to make outsize bets. As of Sept. 30, its information-technology weighting was 38%, compared with 21.4% for the Russell 2000 Growth Index—the fund’s benchmark.
One of its best holdings as of Sept. 30 was Affirm Holdings, which runs a buy now, pay later platform. The stock gained more than 400 % last year.
But that small-cap fund is an outlier in the Winners’ Circle. It is the only one outside of the large-cap growth category among the top 24 finishers in the survey.
At No. 6 is the $25 billion Harbor Capital Appreciation Fund (HACAX), returning 53.7%. As of Sept. 30, the Magnificent Seven accounted for six of its top 10 holdings.
The fund’s managers did make some hay in healthcare, an unloved S&P 500 sector that otherwise eked out a 2.1% return last year, including dividends.
One such healthcare winner it held is Eli Lilly. The pharmaceutical company’s stock returned 61%, helped by its strong position in a nascent class of drugs for weight loss.
“We’re trying to find companies that can generate above-average growth rates sustainably over an investment cycle,” says Blair Boyer, a co-manager of the fund.
Another healthcare company that fit the bill for the fund is Novo Nordisk. Its portfolio includes the Wegovy weight-loss drug. The stock was up more than 50% last year.
The fund unloaded its positions in Thermo Fisher Scientific, which sells testing equipment and measurement tools to laboratories, and life-sciences company Danaher. Thermo Fisher Scientific’s stock fell 4%, and Danaher dropped by 2%.
One of the fund’s biggest sector bets last year was consumer discretionary, representing 25% of the fund at the end of the third quarter, compared with a 16% representation in the Russell 1000 Growth Index.
Shares of vacation-rental company Airbnb, another of the fund’s holdings, surged by 59%.
Ultimately, while large-caps mutual funds enjoyed the Magnificent Seven-led rebound last year, it’s impossible to say how they will fare in 2024 given uncertainty about the economy and the path of the Fed’s monetary policy.
But despite fickle market sentiment, managers of top-performing funds say the key to their success is patience and staying true to their strategy even when things look bleak, as in 2022.
“It was about staying the course, having the conviction and adhering to our investment philosophy in good times and bad,” says Starke of the Value Line fund.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

By improving sluggish performance or replacing a broken screen, you can make your old iPhone feel new agai

Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.