The Couples Embracing the DINK Label
The ‘dual-income, no kids’ moniker is suddenly everywhere, and the lexicon has ballooned to include DINKWADs, SINKs and DINOs

 4 min
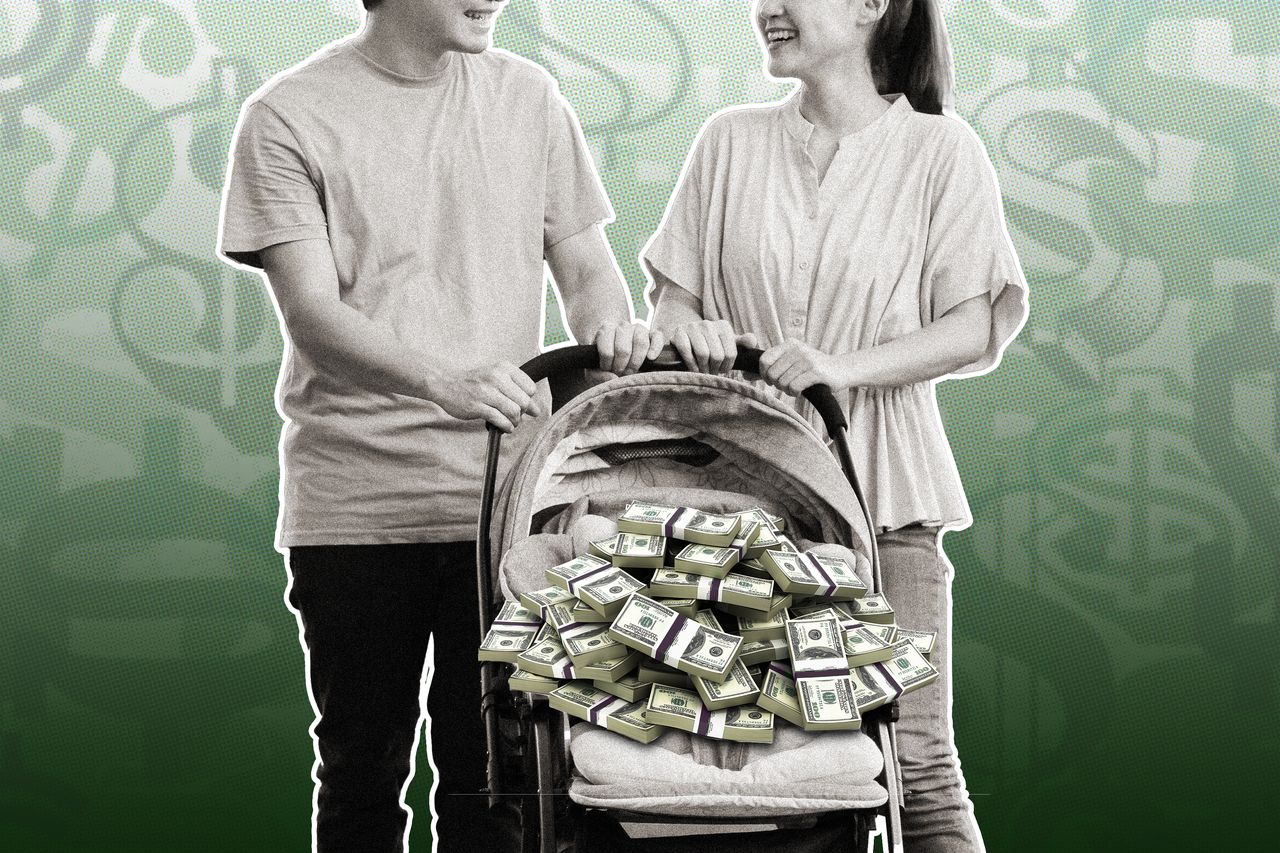
Natalie and Keldon Fischer have no debt other than the mortgage from their Seattle condo, where they live with their Pomeranian, Noble. They each have six-figure salaries and hefty savings accounts. Last year, they traveled nearly every other month, including to Italy, Mexico, Thailand and Finland.
“I really enjoy being a DINK,” says Keldon, a 30-year-old software engineer.
DINK, of course, stands for “dual income, no kids.” It isn’t new slang, but suddenly, vocal DINKs are everywhere as more couples like the Fischers not only embrace the label but boldly let their DINK flags fly.
“Being DINKs means we just have a lot of freedom, time and money,” says Natalie Fischer, 25, a full-time content creator. She’s open to having children, but is first focused on building a net worth of $1 million by age 30. “I know that once I have a kid I will have to assume a lot of the caregiving responsibility and work less.”
Videos touting the DINK lifestyle now rack up millions of views on TikTok and Instagram. Most feature married couples sending the message that they don’t have kids yet (so stop asking), possibly never will, and life is fantastic, thank you very much.
Life as ‘DINKWADs’
The lexicon has ballooned to include DINKWADs (DINKs with a dog), SINKs (single-income, no kids). Some DINKs prefer “DINO,” for dual-income, no offspring.
There is even DINKY—for dual income, no kids, yet.
The public pronouncements represent a shift, says Zachary P. Neal, a psychology professor at Michigan State University who studies child-free adults. Though not all DINKs are strictly child-free, as some may have kids later, he says there is overlap in the groups.
“It has been for a very long time a sort of stigmatised category,” says Neal. “There are all sorts of stereotypes—things like…they’re self-absorbed, they have no stake in the future, they’re too focused on their career.”
But these days, DINKs are leaning into the label, thanks in part to the snowball effect of social media, Neal says, where DINKs are finding safety in numbers. “As some people start to openly identify as child-free, it creates an environment more open and welcoming.”
In a 2021 Pew Research Center survey, 44% of non-parents ages 18 to 49 said they were not likely to have kids ever, up 7% since 2018. Reasons included economic obstacles, concerns about the state of the world and simply not wanting to. And many young adults who do want children are having them later in life than previous generations.
The recent vocal DINK-dom is also generating backlash.
On social media, parents argue they do much of what DINKs do, just with kids in tow. Internet commentators and comedians are using DINKs as material.
“Childless couples are even more annoying than the imaginary children they complain about not even having,” said Lewis Spears, an Australian comedian. “They don’t seem to do anything with their free time except make videos about how much free time they have.”
‘We go where the wind blows’
Brenton and Mirlanda Beaufils, both in their 30s, have been together for over a decade, and say that they’re often questioned about whether they plan to have children.
But they are not ready to give up the flexibility of the DINK lifestyle.
On a trip to Las Vegas, for instance, they partied poolside, dined at the renowned Nobu restaurant, visited casinos and totally lost track of time and went to bed after 5 a.m.
And when Brenton, who is 32 and works in property management, was offered a new job that started in two weeks in another city, the couple made the move—from Boston to Dallas—happen in one week.
“We go where the wind blows,” says Mirlanda, a 30-year-old real-estate agent. “We love that about our relationship.”
In Dallas, they’re closer to Mirlanda’s sisters, including Preciana Prinstil, 29, who often jokingly wonders when Mirlanda will give her children some cousins.
“I want her to feel the love of kids and how they bring joy,” says Prinstil. “Even though they can be a headache.”
Others in the couples’ orbit are also curious. Mirlanda, who wants to be a mom one day, but isn’t in a rush, has a stock retort. “I’m like, ‘Oh, you guys ready to babysit for us? If you can’t answer that question, then stop.’ ”
Free to give mom a car
When Norelle Marquez was younger, she imagined having children at around age 24 or 25. But lately, the 26-year-old hasn’t seen them in her future.
Norelle, a professional photographer, and her husband Robert Marquez, a 28-year-old Marine Corps service member, have no debt, and stick to a firm budget for their Dallas household. “It’s fairly easy being DINKs,” says Robert.
Norelle appreciates that DINK life allows her to provide for family, including her mother, who raised her and her brother as a single parent. She has given her mother a new washer and dryer, house floors, an almost new Toyota RAV4 and more.
The couple posted a video on TikTok about the benefits and quirks of being DINKs, such as, “When we tell people we’re going to Disneyland on vacation, they think we’re weirdos.” It drew nearly 4,000 commenters, including some critics, but many declaring themselves DINKs.
“That TikTok has solidified my feelings about being a DINK and knowing that it’s OK,” says Norelle. “Family doesn’t have to be bloodline,” Robert adds.
Ultimately, whether to have children is a decision that can evolve, says Holly Hummer, a Harvard University Ph.D. candidate who studies women without children.
“We’re all sort of a SINK or a DINK for a portion of our lives,” she says.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
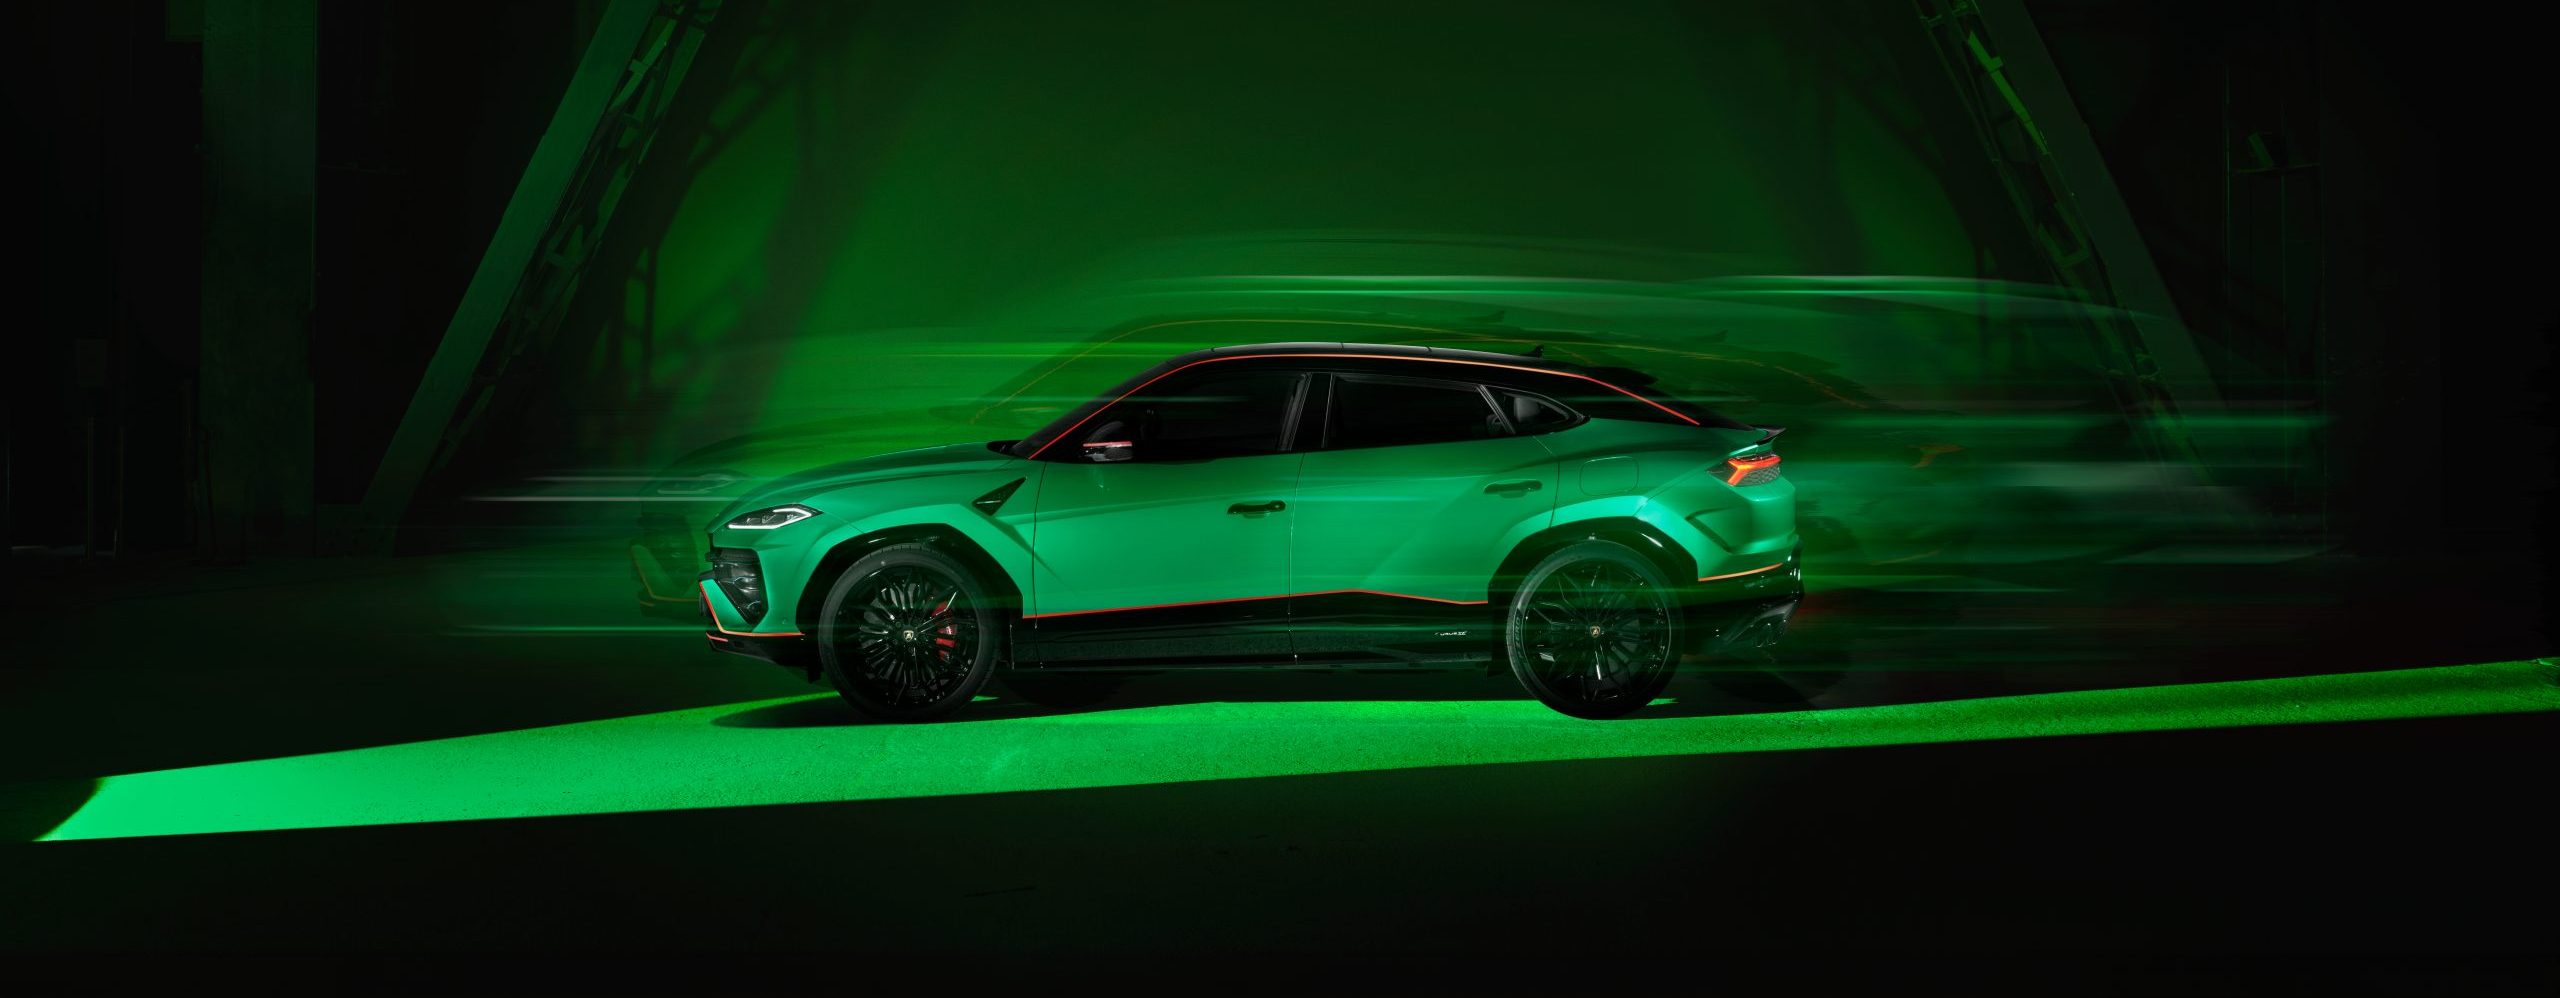
Limited to 630 units, Lamborghini’s latest Urus Capsule pushes personalisation further than ever, blending hybrid performance with over 70 bespoke design combinations.

Rugged coastal drives and fireside drams define a slow, indulgent journey through Scotland’s far north.