The Hunt for Crypto’s Most Famous Fugitive. ‘Everyone Is Looking for Me.’
After a $40 billion cryptocurrency crash, Do Kwon hopscotched across Asia and Europe to evade authorities

 10 min
Fallen crypto tycoon Do Kwon was ready to get out of Montenegro. He and his colleague arrived at the small Balkan country’s main airport, where a Bombardier business jet was waiting to take them to Dubai.
Inside the VIP terminal, Kwon handed his passport to an immigration officer, who swiped it. An alert flashed across the officer’s screen. Kwon, it said, was the target of an Interpol red notice—a request to police around the world to arrest him.
Kwon had been lying low in the Balkans for months, but his luck was running out. About two hours earlier that day, March 23, a tipster had separately warned Montenegro’s top cop, Interior Minister Filip Adžić, that Kwon was likely in the country.
The tipster sent Kwon’s passport details to the interior minister’s phone, according to Adžić, who recounted the arrest for The Wall Street Journal. When Adžić called the border police chief, officers had just detained Kwon at the airport.
“Do you know who that person is?” the interior minister said he told the chief. “He is famous and he has a lot of money.”
U.S. and South Korean authorities had been investigating Kwon over his role in one of the biggest disasters in cryptocurrency history. In May 2022, two tokens that he created, TerraUSD and Luna, crashed in value. The implosion erased $40 billion from the cryptocurrency markets and triggered a chain reaction that pushed other digital-asset firms into bankruptcy. Investors around the world lost their savings.
The investigators concluded that he lied to investors, and suspected he was secretly sitting on a crypto fortune. He now faces charges in both the U.S. and South Korea, including fraud and violations of capital-markets laws. Prosecutors in South Korea have said that if convicted there, Kwon would likely face the longest jail term for a financial crime in the country’s history.
Kwon denied committing fraud. But just before he faced potential arrest, he vanished from his home in a Singapore luxury high-rise. He taunted authorities by tweeting and giving interviews from his undisclosed location. Even after his capture, he kept stirring up drama: A letter he sent from prison to Montenegro’s prime minister unleashed a major political scandal in the tiny U.S. ally.
The 32-year-old Kwon now sits in a Montenegrin prison, where he is kept in isolation. Officials found that the Costa Rican passport he showed at the airport was a fake. The U.S. and South Korea are battling for his extradition. If sent to the U.S., he would likely end up in the same New York jail that now houses Sam Bankman-Fried—another disgraced crypto tycoon, whose companies were fatally weakened by fallout from the TerraUSD-Luna crash.
This account of Kwon’s life on the lam is based on interviews with officials in South Korea and Montenegro, current and former employees of his company, Terraform Labs, and people close to Kwon. He didn’t respond to requests for comment given to his Montenegrin lawyer.
‘Steady lads’
TerraUSD was a stablecoin, designed to maintain a price of $1. Crypto investors often use stablecoins as a haven to save profits from successful trades. TerraUSD differed from many other stablecoins because it wasn’t backed by dollars in a bank. A so-called algorithmic stablecoin, it relied on complicated financial engineering and the collective efforts of traders to keep its $1 peg.
Kwon hailed TerraUSD as the centerpiece of a new monetary system, uncontrolled by banks and governments. Some crypto observers warned it was a ticking time bomb.
On May 7, 2022, its price began to slip, spooking investors. The trigger for the decline was a few big withdrawals from Anchor Protocol, a sort of pseudo-bank that offered investors annual returns of nearly 20% for TerraUSD deposits.
“Deploying more capital – steady lads,” Kwon tweeted as TerraUSD tumbled. His team tapped a $3 billion reserve fund to bolster the stablecoin. He scrambled to arrange a bailout. Nothing worked. Within days, TerraUSD was worth pennies.
Investors were furious. They had poured billions into TerraUSD, putting most of it in Anchor, which many treated as a savings account. Others had gambled on Luna, a related coin that fell more than 99%.
While Terraform Labs was based in Singapore, Seoul was perhaps the crash’s epicenter. Kwon, a South Korean citizen who graduated from an elite foreign-language high school in Seoul and studied computer science at Stanford University in California, had been a figure of national pride. Some 100,000 South Koreans lost money on TerraUSD and Luna, officials there say. Complaints flooded into prosecutors’ offices.
It was Dan Sung-han’s job to lead the investigation. A boyish-looking 49-year-old, Dan heads the Financial Crime Investigation Bureau of the Seoul Southern District Prosecutors’ Office. Local media have dubbed the unit the Grim Reaper of Yeouido, referring to Seoul’s financial district, for its fights against stock-market fraud and manipulation.
“It took us a good amount of time to build a solid understanding of the crypto market,” Dan said.
The South Korean investigators raided Terraform’s local office. They questioned current and former employees. They seized evidence from seven South Korean crypto exchanges, hauling away blue boxes stuffed with documents, laptops, smartphones and external hard drives.
Crypto high roller

Kwon at the time was living with his wife and infant daughter in the Sculptura Ardmore, a ritzy Singapore high-rise. His duplex apartment included a 46-foot-long cantilevered outdoor swimming pool. He kept Japanese whisky and Cuban cigars on hand for guests.
The baby had been born just weeks before the crash. Kwon named her Luna, after his cryptocurrency. “My dearest creation named after my greatest invention,” he tweeted just after her birth, posting a picture of the newborn.
That summer, Kwon met friends at French and Japanese restaurants including Les Amis, with three Michelin stars. He mused to some associates about visiting Europe with his family on an extended trip, so he could be relatively anonymous in a new city.
At one party he attended in Singapore, not long after the crash, many of the attendees were crypto entrepreneurs who came to show their support for Kwon. Cristal Champagne and Martell XO cognac flowed freely, according to one person familiar with the event.
Meanwhile, Kwon’s investors were suffering.
In war-torn Ukraine, web designer Yuri Popovich said he lost $9,000 that he had stashed in TerraUSD because he didn’t trust his country’s banks. In Britain, a 36-year-old IT consultant lost more than $30,000. He said it took him two months to muster the courage to tell his wife. He took a job as a window cleaner to pay the bills.
In Taiwan, local media reported that a man fell to his death from his 13th-floor apartment in an apparent suicide, after telling friends and relatives that he had lost some $2 million on Luna.
Kwon told the Journal through a spokesman in June 2022, “I’ve been devastated by recent events and hope that all the families who’ve been impacted are taking care of themselves and those that they love.”
A Singapore law firm, Drew & Napier, prepared to sue Kwon on behalf of a group of TerraUSD investors who said they collectively lost more than $50 million.
On Sept. 6, 2022, Kwon marked his 31st birthday at home. His wife shared photos with friends of him enjoying a Korean meal with her and playing with their baby.
The next day, a representative of Drew & Napier arrived at the Sculptura Ardmore to serve him with lawsuit papers—but he was already gone.
Red notice
On Sept. 7, Kwon flew to Dubai, and then Serbia, South Korean prosecutors say. He settled in the capital, Belgrade, known for its nightlife scene and tech sector.
Days later, South Korean prosecutors obtained a warrant for Kwon’s arrest on charges that he had violated the country’s capital-markets law. They had worked long hours, feeling intense public pressure to bring Kwon to justice. Dan, their leader, sometimes napped on a black recliner in his office.
Among other alleged irregularities, Dan’s investigators zeroed in on the relationship between Terraform Labs and Chai, a South Korean payment app that at one point boasted two million users.
Before the crash, Kwon had repeatedly claimed that Chai used his firm’s Terra blockchain to move funds between users and merchants. The claim was a key selling point for investors, who saw Chai’s use of Terra as a rare real-world use of blockchain technology. Proponents see blockchain—the underlying technology behind bitcoin and other cryptocurrencies—as a way to empower individuals while cutting out banks and other traditional middlemen.
But Kwon’s claim was false, South Korean prosecutors alleged. In reality, they said, Chai used traditional payment systems to settle transactions and its use of blockchain was a sham. Lawyers for Chai founder Daniel Shin said Chai initially used the Terra blockchain to process payments, but stopped in 2020. Shin, a former business partner of Kwon’s, has denied wrongdoing. Lawyers for Kwon have defended his statements about Chai.
“I am not ‘on the run’ or anything similar,” Kwon tweeted on Sept. 17 after news of the arrest warrant. He still refused to reveal his location, citing threats to his security.
South Korean prosecutors filed a red notice through Interpol, the global policing body, effectively asking cops worldwide to capture Kwon.
From Serbia, Kwon told one crypto-industry associate that he had a deal with the local government. He told another that Serbian law enforcement allowed him to remain even after learning about the Interpol red notice.
Serbia’s Interior Ministry, Justice Ministry, Foreign Affairs Ministry and main public prosecutor’s office didn’t respond to interview requests.
Kwon continued to manage Terraform Labs from hiding, and pushed a long-shot plan to revive its Terra blockchain. He joked with colleagues in Terra Rebirth League, a group on the Telegram messaging app with over 300 members, according to messages seen by the Journal.
Early in his stay in Belgrade, Kwon lived in an apartment near Knez Mihailova, a pedestrian street in central Belgrade known for its shops, sidewalk cafes and 19th-century architecture, said Milojko “Mickey” Spajić, a politician from Montenegro who met Kwon there.
Spajić told the Journal that Kwon invited him for a visit, and the two spent about an hour chatting over coffee, including about Kwon’s ambitions to revive Terra.
The two had known each other since 2018, when Spajić—then a Singapore-based partner with venture-capital firm DAS Capital—agreed to invest $75,000 in Luna. He later returned to his homeland and entered politics, and hoped to turn Montenegro into a blockchain development hub.
Spajić said he didn’t know at the time that Kwon was a fugitive.
On Oct. 12, Kwon registered a company called Codokoj22 d.o.o. Beograd, listing himself and Chang-joon Han as directors, according to Serbia’s corporate registry.
Han was a former Terraform Labs and Chai executive who joined Kwon in the Balkans. Serbian real-estate records from December 2022 show Han owned a 4,300-square-foot apartment in an affluent neighborhood of Belgrade.
On Nov. 8, Kwon made an appearance on UpOnly, a livestreamed crypto podcast. He bantered with another guest: Martin Shkreli, the former hedge-fund manager who had been imprisoned on securities-fraud charges.
“Jail’s not that bad,” Shkreli told him. “It sucks, but it’s not the worst thing ever.”
“Good to know,” Kwon replied.
The pressure builds
Within days of Kwon’s departure from Singapore, investigators in South Korea learned through Interpol bureaus that he was in Serbia, said Dan, the head prosecutor. On Dec. 12, prosecutors in Seoul publicly confirmed his whereabouts. Kwon’s activity on Twitter dropped off sharply.
Later that month, South Korea formally asked Serbia to arrest Kwon and extradite him.
In late January, Dan and a South Korean Justice Ministry official flew to Belgrade. Over several days, they met Serbian law-enforcement officials. The Serbians shared details on the company Kwon had incorporated and his internet address, Dan recalled. They promised to hand over Kwon if he was caught.
On Feb. 16, the U.S. Securities and Exchange Commission sued Kwon for fraud, accusing him of lying about the stability of TerraUSD and Chai’s use of blockchain. The agency also said Kwon and Terraform Labs converted thousands of bitcoin into cash via a Swiss bank, and withdrew more than $100 million after the crash.
Lawyers for Kwon and Terraform Labs criticised the SEC’s lawsuit as government overreach. They denied the Swiss bank allegations, saying the money transfers were for business expenses, and disputed the SEC’s allegations about Chai.
On March 11, Kwon posted his final message in Terra Rebirth League. Replying to a message from an admirer in the private Telegram group, Kwon posted a picture of North Korean leader Kim Jong Un raising his hand in a triumphal greeting.
Two days later, the Journal reported that the U.S. Justice Department was also investigating the TerraUSD crash.
Arrest

Kwon slipped across the border into Montenegro in mid-March and hunkered down in Petrovac, a resort town on the Adriatic Sea, police say.
On March 23, he and Han took a taxi to the airport in the country’s capital of Podgorica, a drive that usually takes about an hour. They paid their driver 4,000 euros ($4,230), a huge sum for ordinary Montenegrins.
After Kwon’s passport triggered the alert, officers detained him and Han, who was also found to have a fake Costa Rican passport. Border police searched the men’s luggage and found three laptops, five phones and one more set of fake passports from Belgium.
“Everyone is looking for me,” a downcast Kwon told the officers, according to Adžić, the interior minister.
Han protested their detention, according to Adžić, saying, “We are VIPs everywhere that we go.” Han didn’t respond to requests for comment through his lawyers.
Hours later, federal prosecutors in New York filed fraud charges against Kwon. A South Korean ambassador soon showed up at Adžić’s office to discuss extradition proceedings.
A Montenegrin court convicted Kwon and Han for using forged passports. It sentenced them to four months in prison, but they can be held longer as they await extradition. Kwon has said he didn’t realise the passports were fake, and that he was swindled by the agency in Singapore that obtained them for him.
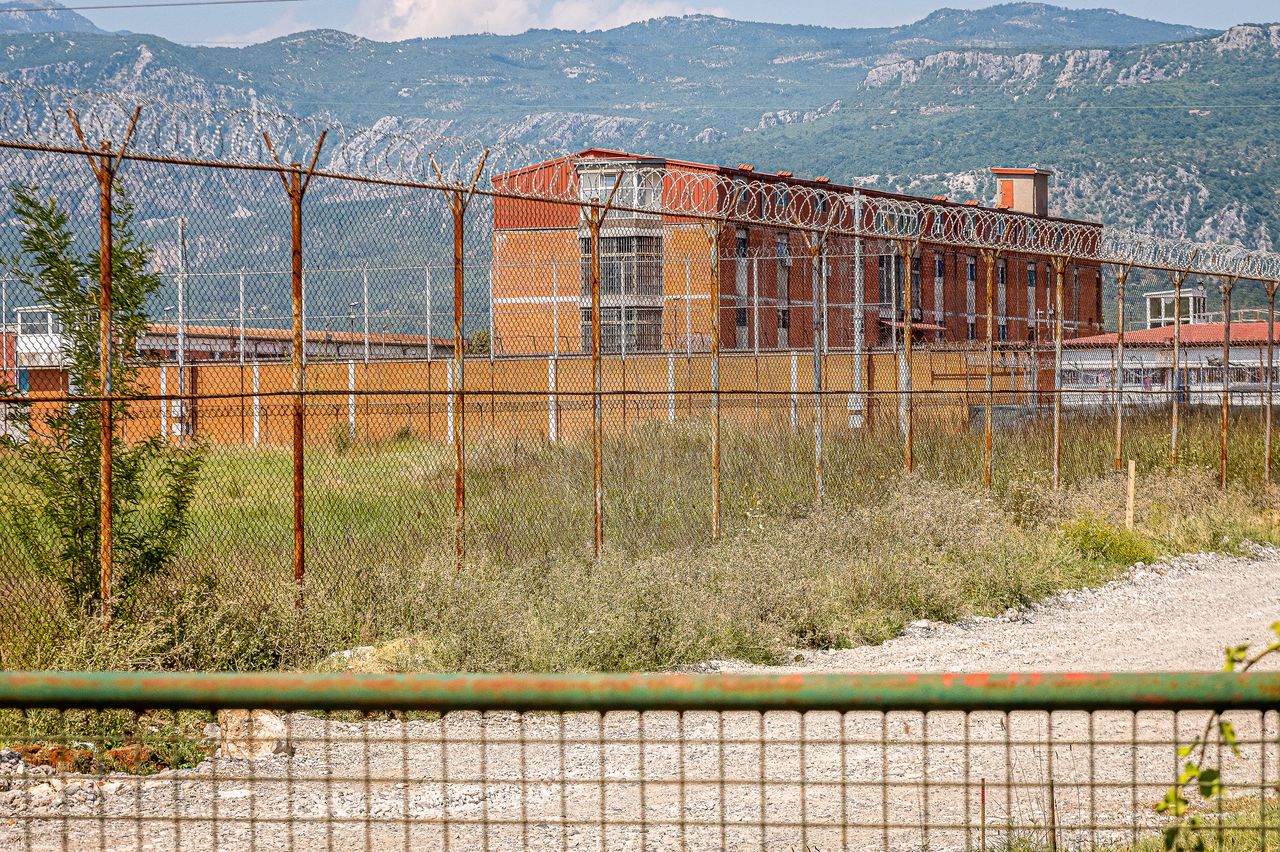
Since his arrest, Kwon has been confined to Spuž prison, a cluster of brick buildings in a valley near Podgorica. He is allowed outdoors for one hour a day in a yard surrounded by a barbed-wire fence, overgrown fields and a rock-strewn mountainside.
After being jailed, Kwon had a tearful reunion with his wife, in which he expressed regret for the trouble he had caused her and their young daughter, a person familiar with the matter said.
Kwon tried to post bail of 400,000 euros ($423,000), but prosecutors opposed his request, calling him a flight risk.
On June 5, a one-page letter from Kwon arrived at the office of Montenegrin Prime Minister Dritan Abazović. The letter, in Kwon’s tidy handwriting, described his friendly ties with Spajić, the politician who had met Kwon in Belgrade—and a rival of the incumbent prime minister. Spajić’s party was expected to win an election days away.
The letter said Spajić tried to raise funds from Kwon and other “friends in the crypto industry,” according to a copy seen by the Journal.
Spajić denied asking Kwon for money. He said the letter was a trick masterminded by his political foes and the Serbian secret police. He suggested that Kwon was duped into writing the letter with a promise that Montenegrin authorities would free him on bail and let him escape the country. Serbia’s intelligence agency didn’t respond to a request for comment.
The letter prompted an uproar. Rival politicians attacked Spajić, who had built up an image as a corruption fighter, saying he had cozied up to a crypto fugitive. Spajić’s party narrowly won the June 11 election, putting him on track to become Montenegro’s next prime minister.
Kwon hasn’t disputed that he wrote the letter. His Montenegrin lawyer, Goran Rodić, said Kwon didn’t donate to Spajić. The lawyer declined to share more details, citing an open investigation.
European officials who visited Spuž prison last year said its cells were poorly ventilated and stiflingly hot in the summertime. They also noted poor hygiene and overcrowding.
To occupy his time, Kwon watches television with a limited number of English-language channels in his cell, his lawyer said during a sweltering day this summer.
“Considering the current weather conditions, and considering the general nature of being in prison, I think he is doing OK,” Rodić said
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
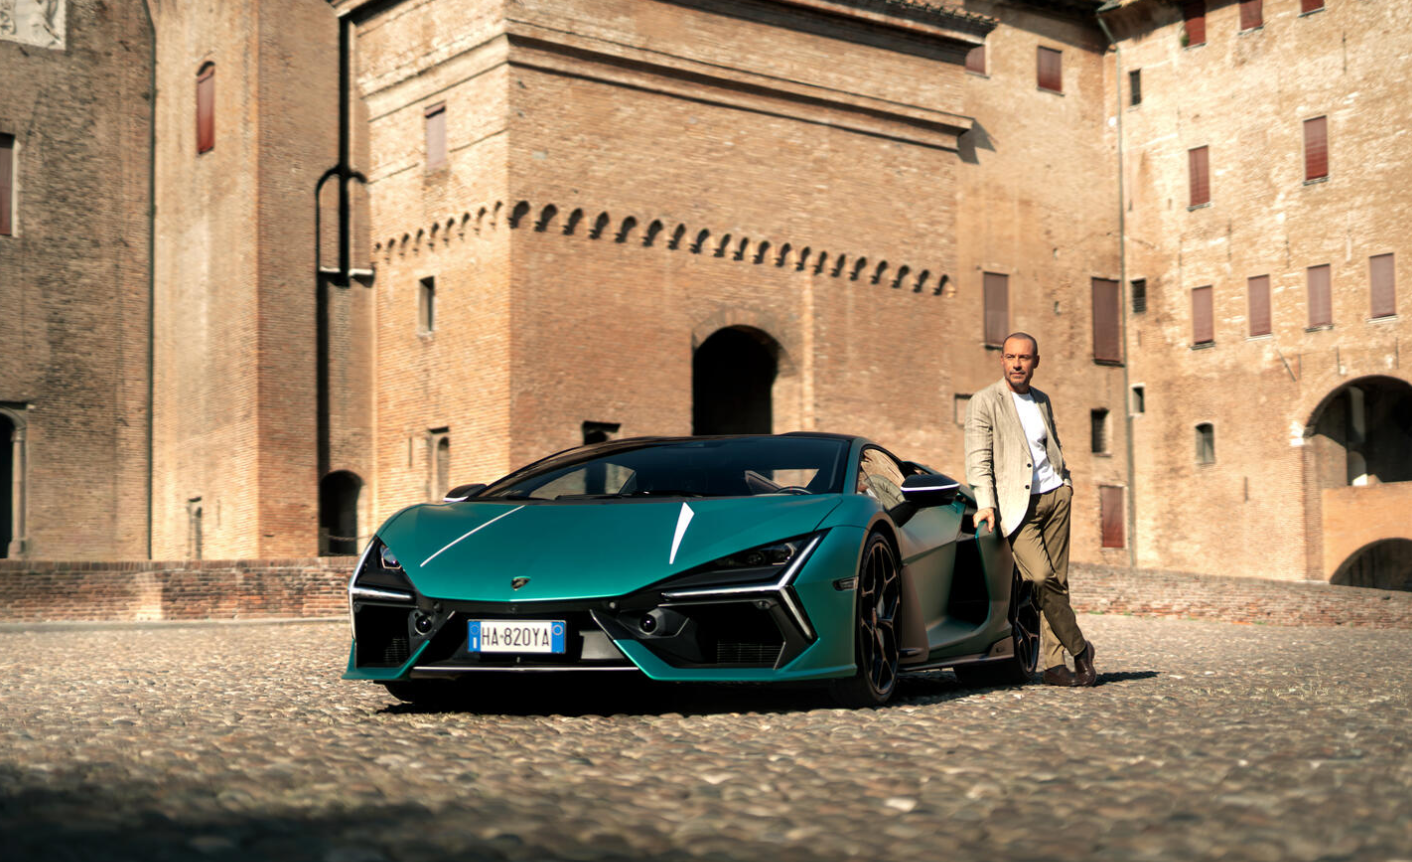
Automobili Lamborghini is turning its attention to something considerably more difficult to define: what makes Italian excellence uniquely Italian?


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 min
A sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
International AI strategist Justin Kabbani will headline the Kanebridge Property Summit in Sydney on June 18, with tickets selling fast.
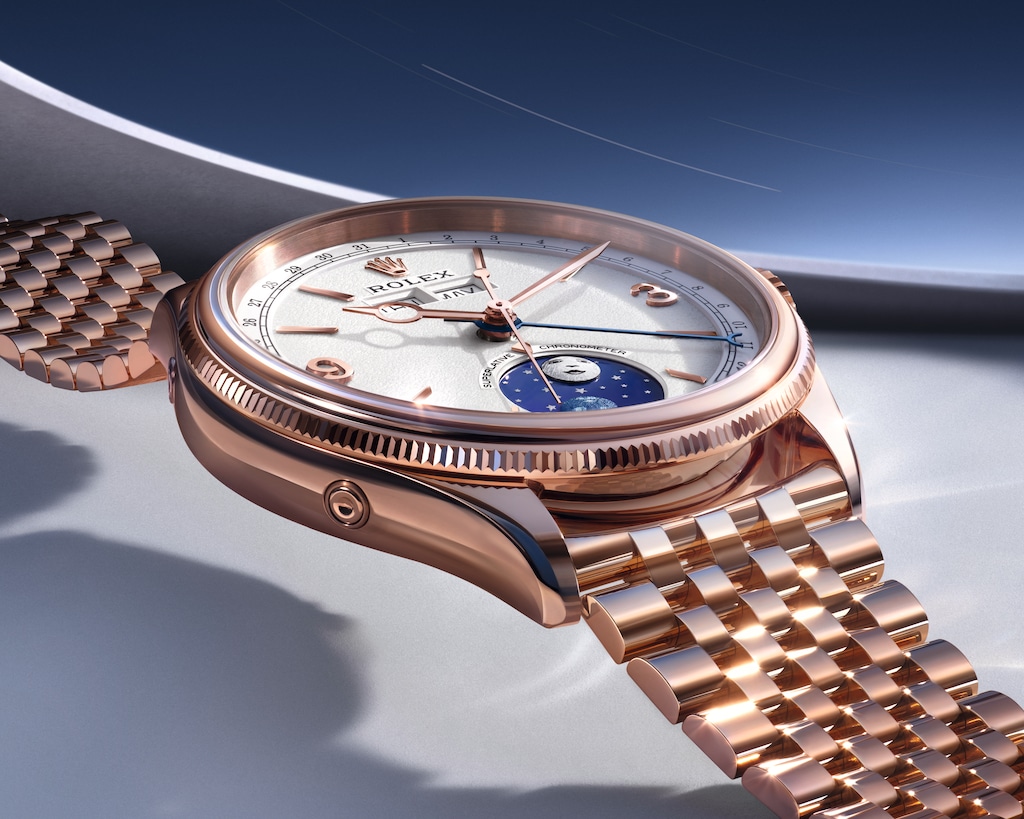
The Perpetual Padellone draws its name from the coveted reference 8171 while introducing an instantaneous complete annual calendar to Rolex’s modern Perpetual collection.