The Improbably Strong Economy
A lot had to go right for the U.S. to avoid a recession. So far, it has.

 3 min
The economy is still generating jobs. A year ago, a lot of economists and Federal Reserve policy makers thought that it would be shedding them by now.
On Friday, the Labor Department reported that the U.S. added a seasonally 150,000 jobs in October from the previous month, versus September’s gain of 297,000 jobs. Some of that step down was due to auto workers’ strikes, which have since been resolved but temporarily caused workers to not draw pay checks.
Average hourly earnings rose 0.2% from a month earlier, putting them 4.1% higher than a year earlier. That was the smallest year-over-year gain since June 2021, though unlike then wages are now outpacing inflation.
One takeaway is that the job market is moderating, but not buckling—a message reinforced by a variety of other data, including low levels of weekly unemployment claims and layoffs. Another is that the Federal Reserve is probably through with tightening: Futures markets on Friday morning indicated that the chance of the central bank raising its target range on overnight rates at its December meeting was below 10%. The yield on the 10-year Treasury note, which briefly hit 5% less than two weeks ago, continued to retreat Friday, falling to 4.53% midmorning.
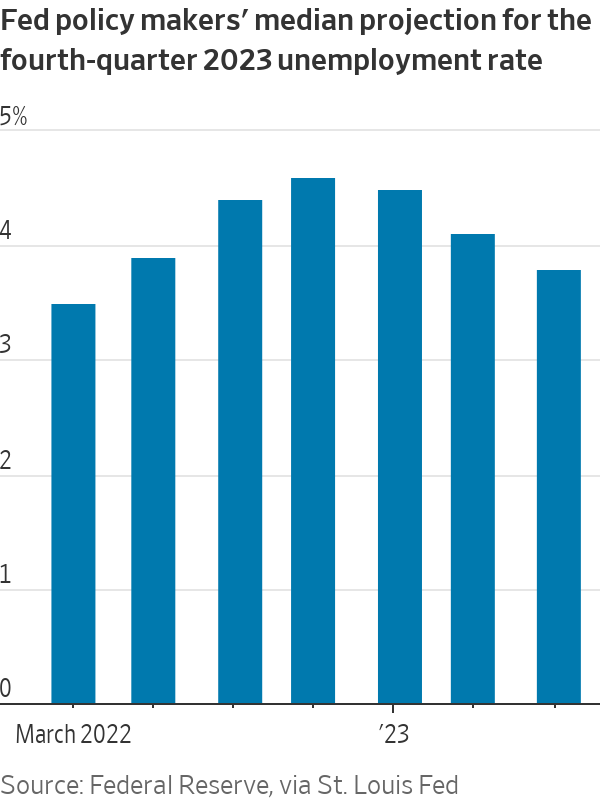
This wasn’t the sort of job market the Fed expected. When policy makers offered projections last December, they forecast that the unemployment rate would average 4.6% in this year’s fourth quarter, versus the 3.7% rate (since revised to 3.6%) they had seen in the November 2022 job report. That was tantamount to a recession forecast, though they didn’t put it that way, since such a large increase in the unemployment rate would count as a strong signal the U.S. is in a downturn. Friday’s report showed the October unemployment rate at 3.9%.
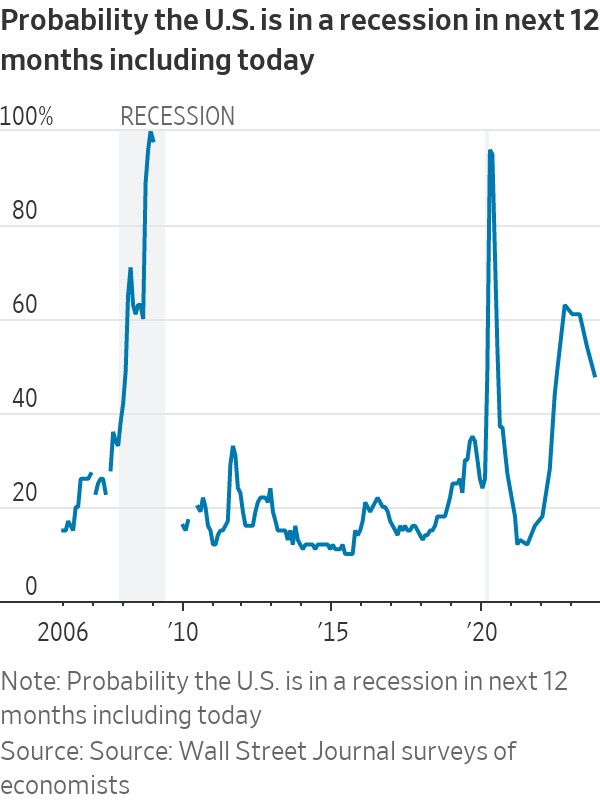
Economists got it wrong, too. In October of last year, forecasters polled by The Wall Street Journal estimated the unemployment rate at the end of 2023 to be at 4.7%, on average. They also put the chances of a recession within the next 12 months at 63%. By last month, they dropped the recession chance to 48%. Available data show that, as a group, economists have never forecast a recession before it has actually started. Now it looks as if the one time they did forecast one, they were either wrong or early.
It is easy to make fun of other people’s past forecasts, but considering the hurdles the economy has had to clear, it really is striking that it has done so well. A year ago there was some hope that the continued recovery in the service sector, and service-sector jobs, might help take up the slack as the goods sector adjusted to slowing demand. But there was also the concern that the service sector could run out of steam before the goods sector found its footing.
Another worry: That the excess savings that Americans had built up after the pandemic struck would run out, and that would cut into their ability to spend. But recent revisions to the available data suggest there was more money left in the tank than thought.
To these, add that inflation has cooled despite the addition of 2.4 million jobs so far this year, and gross domestic product is expanding much faster than economists expected. Plus, at least so far this year, the economy has made it through a regional bank crisis, a sharp increase in both short- and long-term borrowing costs, and the resumption of student-debt payments.
The jury is out on what happens next. The cooling in the job market could turn into a lurch lower, for example, as the full effect of the Fed’s past rate increases begins to take hold. Inflation, which is still too high, could accelerate, prompting the central bank to further tighten the screws.
But the chances of the economy avoiding a recession seem stronger now than they did even a few months ago. A lot of that would be down to luck, but it would nonetheless be something worth celebrating.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
Australia’s housing market rebounded sharply in 2025, with lower-value suburbs and resource regions driving growth as rate cuts, tight supply and renewed competition reshaped the year.
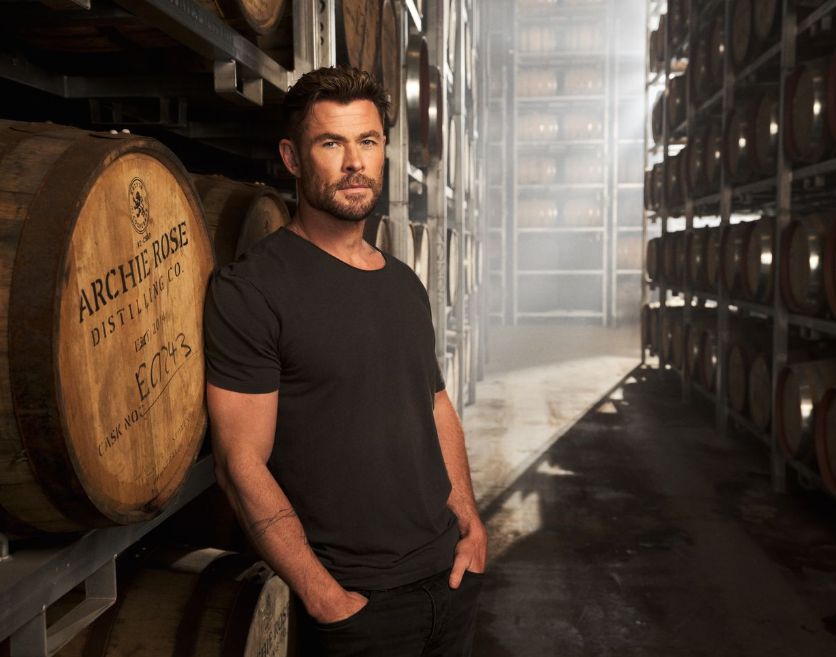
Australian actor Chris Hemsworth has joined Archie Rose Distilling Co. as co-owner and strategic business partner as the Sydney spirits company prepares to enter the United States. The partnership brings Hemsworth together with Archie Rose founder Will Edwards, with the pair aiming to build greater international recognition for Australian whisky. Founded in Sydney in 2014, …
Continue reading “Chris Hemsworth Joins Archie Rose as Co-Owner Ahead of Global Expansion”