The Crazy Economics of the World’s Most Coveted Handbag
The Hermès Birkin is one of the fashion world’s most conspicuous markers of wealth. Is it worth the investment?

 8 min
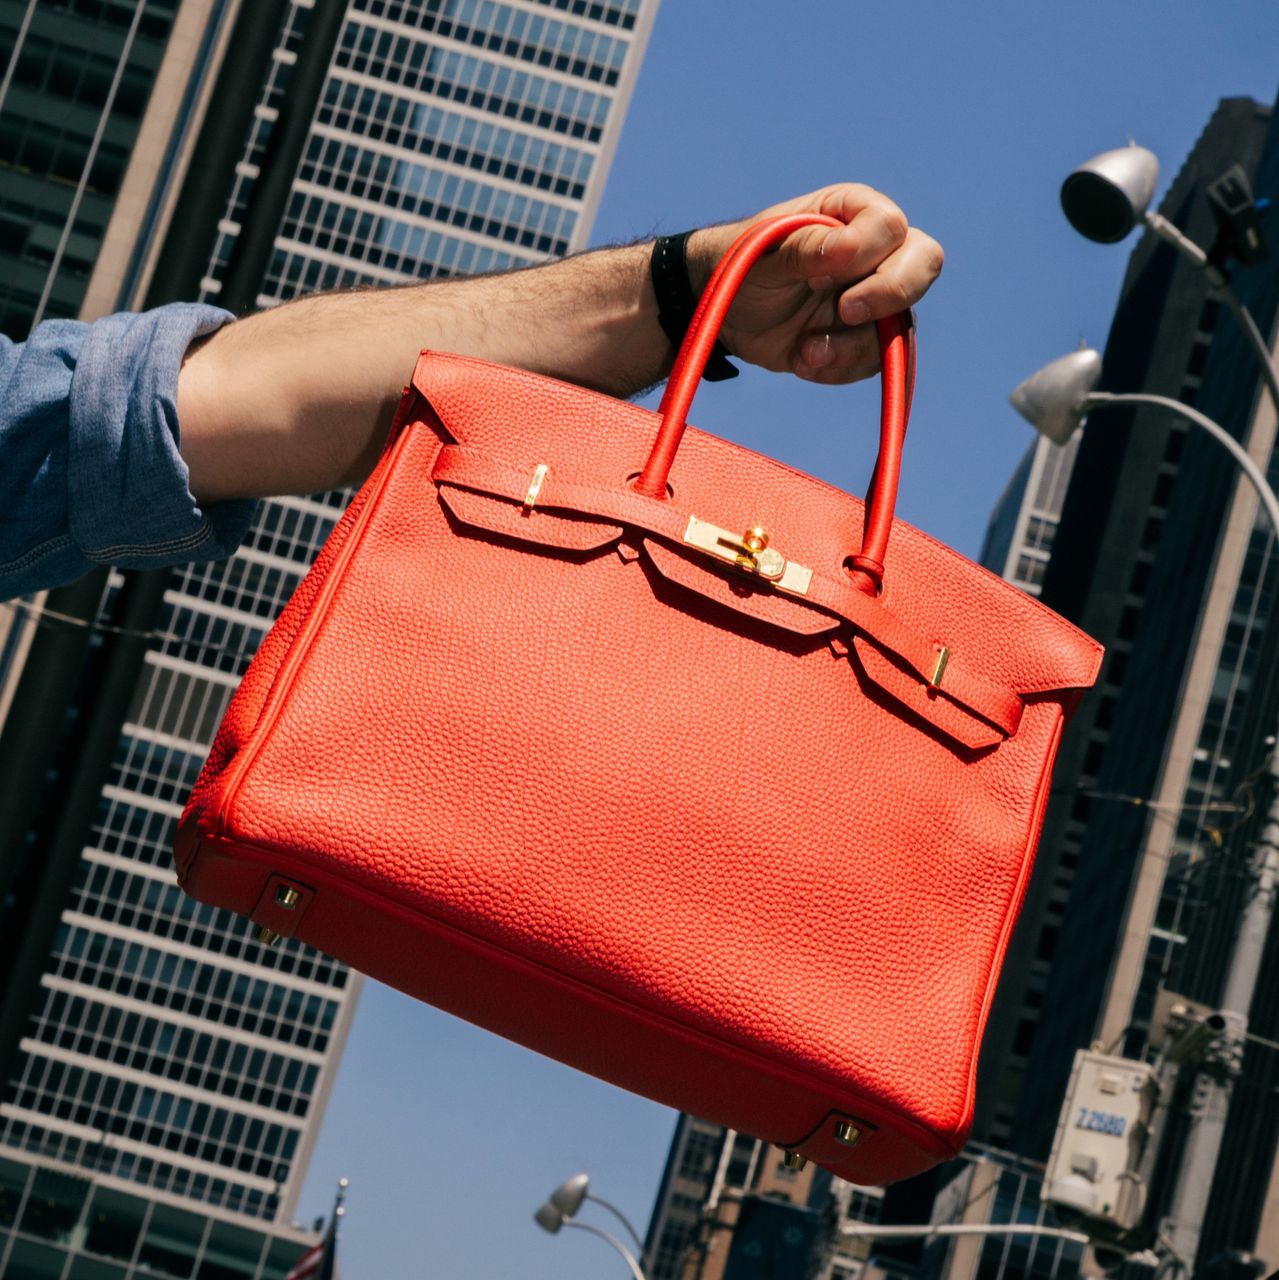
You could double your money in five minutes by buying a Birkin handbag at your local Hermès boutique and then flipping it. But getting your hands on the world’s most sought after purse is a lot more complicated than it sounds.
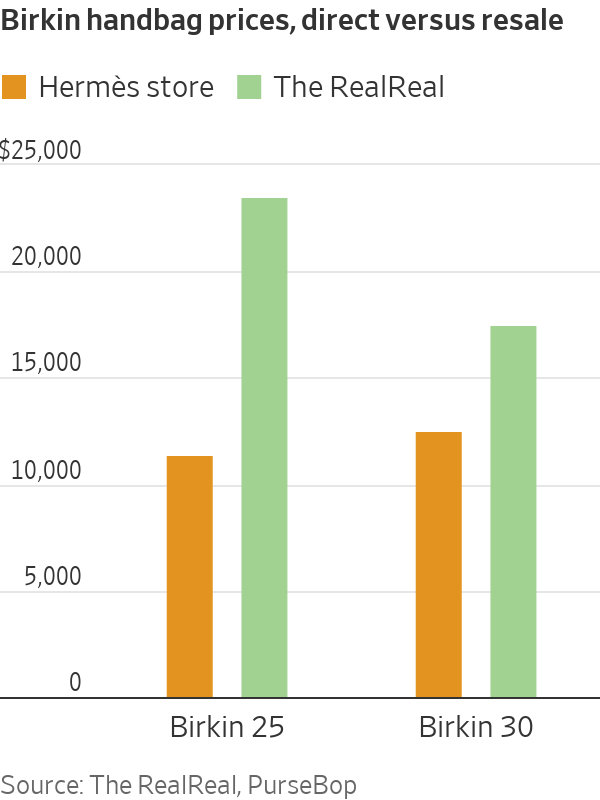
A basic black leather Birkin 25 costs $11,400 before tax at the Hermès store. Buyers can walk out and immediately give it to a handbag reseller like Privé Porter in exchange for $23,000 in cash. Privé Porter will then sell the Birkin on Instagram or at its Las Vegas pop-up store, possibly on the same day—box fresh, with receipt—for up to $32,000. All this for a bag that analysts estimate costs Hermès around $1,000 to make.
The unusual economics of the Birkin have upended the normal balance of power between shopper and store worker. At the Hermès boutique, it is the buyer who kowtows. Some of the wealthiest women in the world have brought homemade cookies to the store to cozy up to their sales assistant. They have offered tickets for Beyoncé concerts, trips to the Cannes Film Festival in a private jet and even envelopes stuffed with cash—all to get their hands on a Birkin.
Shoppers also spend tens of thousands of dollars on Hermès products they might not particularly want, such as an $87,500 canoe, to be in the running for a rare purse.
The Birkin turns 40 this year and is maturing into a phenomenon. To carry one is to signal that the wearer can afford to drop anywhere from $10,000 to $100,000 on a handbag. It appeals to the limelight-seeking Kardashians, who own extensive collections, but also to European Central Bank President Christine Lagarde , who is often photographed on her way to meetings carrying a Birkin.
The purse anchors the Hermès founding family’s $150 billion fortune. But they aren’t the only ones getting rich: An army of unofficial flippers all over the world profit from reselling the purse.
The Birkin first hit shelves in 1984, a couple of years after the late actress Jane Birkin and Jean-Louis Dumas, then chief executive of Hermès, met on a flight to London. After complaining that she couldn’t find the right-size handbag, the two sketched out a design together—on a drink napkin or an Air France sick bag, depending on the retelling. In return for lending her name to the new product, Hermès paid Birkin an annual royalty.
The story about the bag’s creation is part of its appeal and one of the reasons why competitors have found it hard to replicate its success. “It’s a great narrative,” said David Dubois, associate professor of marketing at the business school Insead. Shoppers like the “serendipity of the meeting” and that a woman who was admired for her style had a direct hand in its design.
The purse didn’t take off right away. During the early 1990s, shoppers could walk into an Hermès boutique and buy one off the shelf. Birkins weren’t reselling for more than their original price tag back then.
But something shifted in the years after the 2008-09 financial crisis, according to Matthew Rubinger, now chief commercial officer at the online marketplace 1stDibs and one of the first people to recognise the Birkin’s resale potential. Rock-bottom interest rates meant more money was sloshing around, and it began to find its way into alternative assets.
It also became bad taste to wear a new “it bag” every season when the economy was on the ropes. This played to the strength of no-logo designs like the Birkin. Rubinger established the handbag departments of both Heritage Auctions and Christie’s and built them into multimillion-dollar businesses. When rare Himalaya Birkins began to set records at auction, people took notice.
“Once they started getting above $100,000, things got more serious,” he said.
Today, shoppers who want a Birkin at the Hermès store must jump through hoops. First, they need to establish a good rapport with one of the brand’s sales assistants. The next step is to spend serious cash on other goods, such as silk scarves, watches and shoes, to “qualify” for a bag, according to Birkin collectors.
When a shipment of Birkins arrives at an Hermès store from France, the leather-goods manager assigns the purses to individual sales assistants, all of whom have a list of wealthy clients waiting to be offered a bag. The sales assistant must make a case for which individual on that list deserves to be offered a Birkin and get the manager’s approval.
This has created a perception among Hermès shoppers that the biggest spenders get access to Birkins first. Hermès is being sued in a California court by two wounded shoppers who allege that the brand only sells Birkins to “worthy” customers and makes purchases of the bag conditional on buying other items at the store. Hermès said in a recent court filing that it doesn’t require customers to buy other products before getting one of the coveted bags.
Just how much do shoppers need to drop to be offered a bag? Birkin collectors say that there is no hard rule but that most people can expect to shell out $10,000 or more on Hermès scarves, shoes and clothes before they will be offered a basic Birkin. To get a rare bag like the Himalaya Birkin, they might need to spend $200,000 or more.
This is known as the Hermès “prespend” or the “spend ratio” in Birkin-collecting circles. Hermès never spells this out explicitly, nor has it ever used these terms. But Birkin hopefuls say they have been told by their sales assistants that they need to visit the store more often. Resellers say that Hermès sales assistants don’t make commissions on Birkins, but that they can leverage hunger for the bag to sell other products for which they are rewarded.
Even after spending tens of thousands of dollars, Birkin hunters might not be offered the size or colour bag they want. This creates a golden opportunity for resellers.
Say a woman who shops regularly with the brand wants a red Birkin but is offered green. Rather than appearing ungrateful—because it is important to keep the sales assistant on her side in the Birkin-hunting game—she will buy the bag, knowing it can be sold to a reseller for a profit and hope to get the red later.
Hermès knows its top clients are flipping the bags. Read the fine print on a Birkin receipt, and the company asks that its customers will not, “directly or indirectly, resell Hermès products purchased in our boutiques for commercial purposes.” No Hermès shopper was willing to go on the record for this article about the experience of flipping the bags to a reseller, out of concern over being blacklisted by the brand.
The resale market has become a kind of “buy-now button” for Birkins, said Michelle Berk, founder of Privé Porter. Some shoppers are willing to pay a big premium to get their hands on a Birkin immediately, in the exact color they want. They might not have the patience for the steps needed to secure one of the bags at the Hermès store.
In the past, resellers recruited flight attendants or polished overseas students to buy Birkin bags in Hermès stores all over the world in return for a fee. Now, the flippers get most of their supply from Hermès’s VIP customers. They also get Birkins by trading with their peers on WhatsApp. If clients are looking for a size or colour that one seller doesn’t have in stock, they can put out a call on the resellers’ group chat to see if anyone has that model.
One way Birkin hunters can accelerate an in-store purchase is by splashing out on the brand’s furniture or fine jewellery, said Judy Taylor, founder of Madison Avenue Couture and a handbag reseller for 15 years.
They can pick up an $8,000 paper basket for the home office, a $70,000 gold bracelet or a $140,000 sofa. Taylor said Hermès’s sales in categories like fine jewellery or watches, where the brand isn’t known for its expertise, are at least partially driven by Birkin hunters.
“No offence to Hermès, but if you can buy a necklace from Van Cleef for the same price as Hermès, you’ll likely go to Van Cleef,” she said.
Really big spenders are offered bespoke goods. Hermès does a sideline in special-order skis, skateboards and fishing gear for superwealthy clients and can customise the interior of a yacht or chopper. Privé Porter’s Berk received a message from a customer who was offered an $87,500 canoe. These buyers get access to the rarest Birkins.
An unusually large amount of new Hermès inventory ends up for sale in the secondhand market—another sign that Birkin mania might be driving sales of products that customers don’t really want. Of all the nonhandbag Hermès items on The RealReal , 35% are in pristine condition, according to data supplied by the luxury resale website. The average for other designers on The RealReal, including Louis Vuitton, Gucci, Prada, Bottega Veneta and Saint Laurent, is 20%.
The Birkin’s popularity is very flattering for Hermès and might also help the company to keep its marketing budget low. It doesn’t need to promote itself when celebrities can be relied upon to freely splash photos of their bags on social media. In 2023, Hermès reinvested 4% of its sales back into promotions, compared with 12% at crosstown rival LVMH Moët Hennessy Louis Vuitton.
But the circus does cause problems for Hermès. Last year, the company had to fire staff at its Miami Design District store after some customers got more than their official allocation of Birkins, according to sources. Collectors say Hermès only allows two bags a year per individual, but employees might have been helping shoppers to get around this.
Shoppers and resellers have tried to bribe their way to Birkins. Hermès has strict rules about what customers can and can’t give sales assistants as gifts. Well-behaved Birkin hunters give goods that can be handed over openly at the store and shared among employees—hence the home-baked cookies. Trays of baklava are another go-to.
Hermès doesn’t like the flipping, but stamping out the resellers would harm the brand’s own interests. The company raised prices of its exotic-skin Birkins by around 20% in January. Resellers think the move was aimed at squeezing profits in the secondhand market, but it hasn’t worked. Dealers passed on the increase to their customers without a hitch.
Hermès could increase production and flood the market with new bags. This would end the financial incentive to resell Birkins, but it would also destroy their mystique.
Why are women— and increasingly men , too—so hungry for the Birkin? One justification for spending huge sums on a handbag is that the Birkin is a good investment. Except, it isn’t really. Any profit on reselling a bag purchased in store will be lower after factoring in the thousands of dollars spent on other goods to qualify.
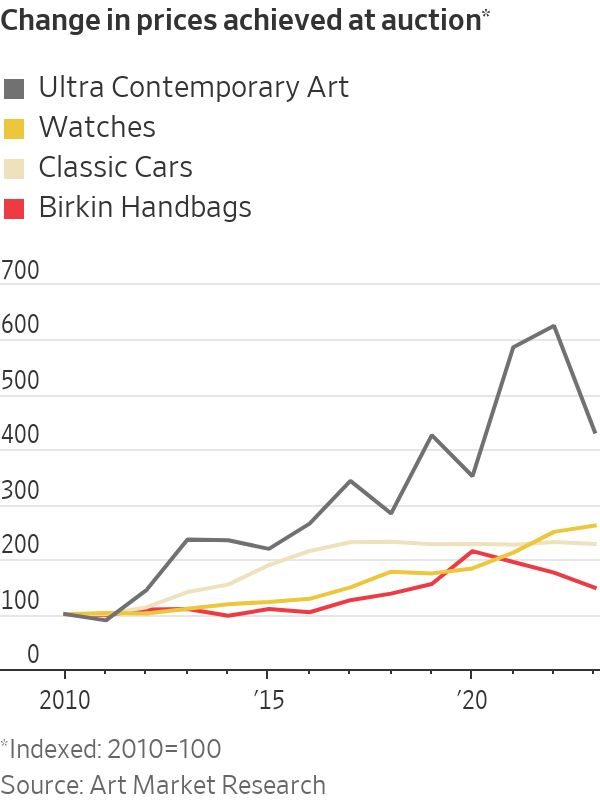
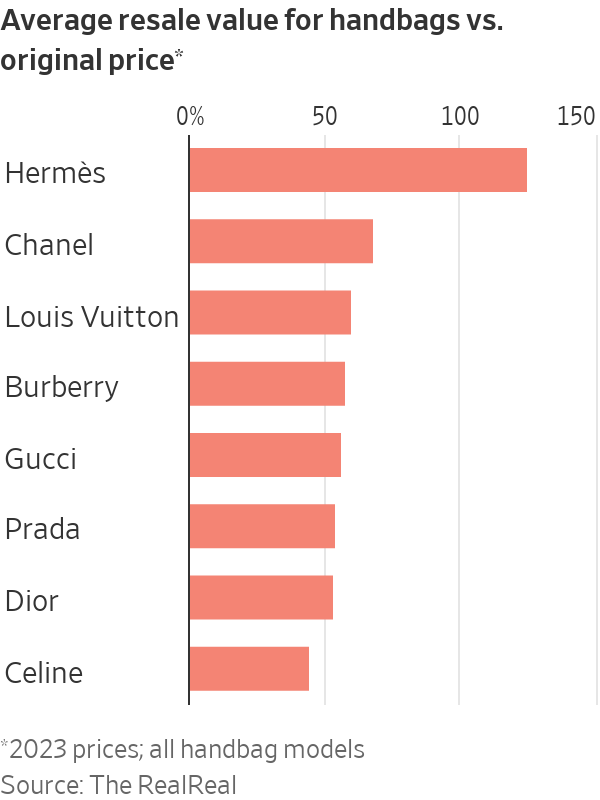
A bag sourced from a reseller or on the block at Christie’s has limited upside because a hefty markup is factored into the price. A Birkin bought at auction in 2010 would sell for around 50% more today, according to Art Market Research data. Contemporary art, watches and classic cars have all performed better. Hermès’s own stock has been a much smarter investment than the Birkin, rising more than 20-fold since 2010.
Shoppers seem to lust after the Birkin because it is rare, expensive and well made. There is no better status symbol for those who want to display their wealth. And the hunt involved in getting one might be the whole point. Wealthy shoppers tolerate waiting at the Hermès store in a way that wouldn’t be acceptable in other areas of their lives.
Even how a person treats the Birkin has turned into a kind of code. Some collectors store them in glass display cabinets, hardly ever using them. This preserves their resale value.
But the supermodel Irina Shayk was photographed last year carrying her dog in a black crocodile Birkin. According to Sasha Skoda, The RealReal’s vice president of merchandising, the subtext to the “messy Birkin” trend is that you have to be seriously rich to treat a $40,000 handbag this casually. Jane Birkin was also hard on her bags, covering them with political stickers and tying charms around the handles. One of her weathered black Birkins sold at auction for £119,000 in 2021, around $150,000 at current exchange rates.
Rival luxury brands are trying to come up with challengers. Louis Vuitton recently launched a $1 million handbag. Chanel has almost doubled the price of its classic flap purse in four years to make it more exclusive.
For now, though, the reign of the Birkin looks secure. If you want to own one, better dig deep at the Hermès store.
—Herme`s Birkin bag provided by The RealReal.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From citrus oils to warming spices, the classic G&T is being reimagined at home as a more thoughtful, seasonal ritual for modern entertaining.
On October 2, acclaimed chef Dan Arnold will host an exclusive evening, unveiling a Michelin-inspired menu in a rare masterclass of food, storytelling and flavour.