The Power Move of Working the 5-to-9 Before the 9-to-5
Working a regular day, even into the evening, is for mere mortals. Those out to impress start well before dawn.

 4 min
As a competitive rower in my long-ago prime I sometimes used a racing strategy called fly and die. Sprinting to an early lead often yielded a fast overall time, even if I couldn’t hold my torrid pace through the finish line.
Some professionals take a similar approach to their desk jobs, starting their workdays with a 5 a.m. to 9 a.m. shift. They are up before the sun—and, more important, before their co-workers—to get a jump on the workday and impress the boss.
Nothing screams go-getter like a predawn email! Getting stuff done early allows them to clock out midafternoon and still look like stars, even if their routines require Ben Franklin-esque sleep schedules and vats of caffeine.
Melissa O’Blenis rises by 4:30 a.m. for prayer and Peloton time before starting her job at the digital consulting firm Argano.
“I just love checking things off my list,” she says. “I need that focus time away from Teams messages, email notifications and text alerts.”
A mother with two sets of twins, O’Blenis, 48, often breaks for her kids’ afternoon sports without feeling guilty or judged. Colleagues jokingly call her Granny because her 9 p.m. bedtime makes the early starts possible. But Granny got the last laugh when she was promoted to a director-level role in March.
More than 90% of knowledge workers want to flex their hours, according to surveys by Slack’s Future Forum . In the pandemic many of us got in the habit of handling personal commitments during standard business hours, then catching up on work tasks later .
Now that the office battle is largely over, fighting a return to rigid, 9 a.m. to 5 p.m. schedules might be workers’ last stand. But managers complain about afternoon dead zones when employees are out of pocket.
The solution for more workers is starting sooner instead of finishing later. Workflow software maker Asana reports that 21.4% of users are logging on between 5 a.m. and 9 a.m. this year, up from 19.8% in 2021. About 12% of work tasks are completed before 9 a.m., the company says, compared with 10% before the pandemic.
Early-bird bosses
Gibran Washington and his basketball teammates at Hofstra University used to run at 6 a.m. He maintained his early wakeups while climbing the ranks in food-and-beverage management.
By 9 a.m. meetings, he had already exercised, meditated and put in a couple of hours of work.
“I always found myself more prepared than my colleagues who hadn’t had their first cup of coffee yet,” says Washington, 40, who doesn’t drink coffee. Now he is chief executive of Ethos Cannabis, a chain of 12 dispensaries in three states, and rises as early as ever.
Waking and working ahead of the pack is a common CEO habit, from Apple ’s Tim Cook to General Motors ’ Mary Barra . Even if your ambitions are less grand than the corner office, starting early could help you stand out for one simple reason: The boss is probably up, too, and taking notice.
Matt Kiger says being the first one into the office helped him catch his manager’s eye and advance after changing careers from education to media sales. He would set his alarm for 5 a.m., hop a train from Connecticut to New York and be at his workstation before 7.
“I thought, ‘What is it going to take to break through?’” he recalls. “‘It’s going to take being there when my boss comes in, already at my desk making phone calls.’”
Now a senior vice president for digital sales at Townsquare Media , Kiger, 47, says much of the daily communication among company leaders happens by text and phone from 6 a.m. to 8 a.m. It’s possible to succeed as a night owl, he says, but people who sleep in risk missing a window when many executives are awake and accessible. While some working parents can’t swing early-morning meetings, others like Kiger say they are the key to being present at kids’ after-school activities.
Getting the worm
Matt Sunshine—whose surname surely predestined him to be a morning person—wakes at 5:30 a.m. to read the news. Then he cycles or takes a Pilates class and is on his computer by 7.
Sunshine is CEO of the Center for Sales Strategy in Tampa, Fla., which helps healthcare, media and professional-services companies generate leads. He doesn’t expect his 55 employees to follow his schedule but says it becomes progressively harder to get his attention as the day goes on and his calendar fills up with meetings. He also tries to log off by 5:30 p.m. for family time, so working after hours won’t necessarily make an impression.
“If you want to get my attention, a good time to get me is first thing in the morning,” Sunshine, 55, says. “Because people know I’m an early riser, I think that does influence other people to do the same.”
Elvi Caperonis’s morning routine is next-level organised. Her alarm rings at 6 a.m. She goes for a run at 6:30. At 7 she showers and eats breakfast. At 7:30 she opens her laptop and sets a timer for 25 minutes. That’s her first block to focus on the most important task of the day before a five-minute break. She repeats the on-off work pattern throughout the day.
Caperonis, a technical program manager at Amazon , makes a daily to-do list with nine items. She rates one critical, three medium-level and five lower-priority. This helps her work efficiently and in the right order.
The 41-year-old works from home in Florida and often picks her daughter up from school at 2:30 p.m., freedoms she has preserved partly by being highly productive early in the day, she says. Much of her job involves identifying potential risks to a project’s success, and when she sends an early-morning alert it arrives really early for company leaders in the Pacific time zone.
“They appreciate having that information first thing when they open their email,” she says. “In my experience, leaders are also early birds.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A survey of people with at least $1 million in investable assets found women in their 30s and 40s look nothing like older generations in terms of assets and priorities
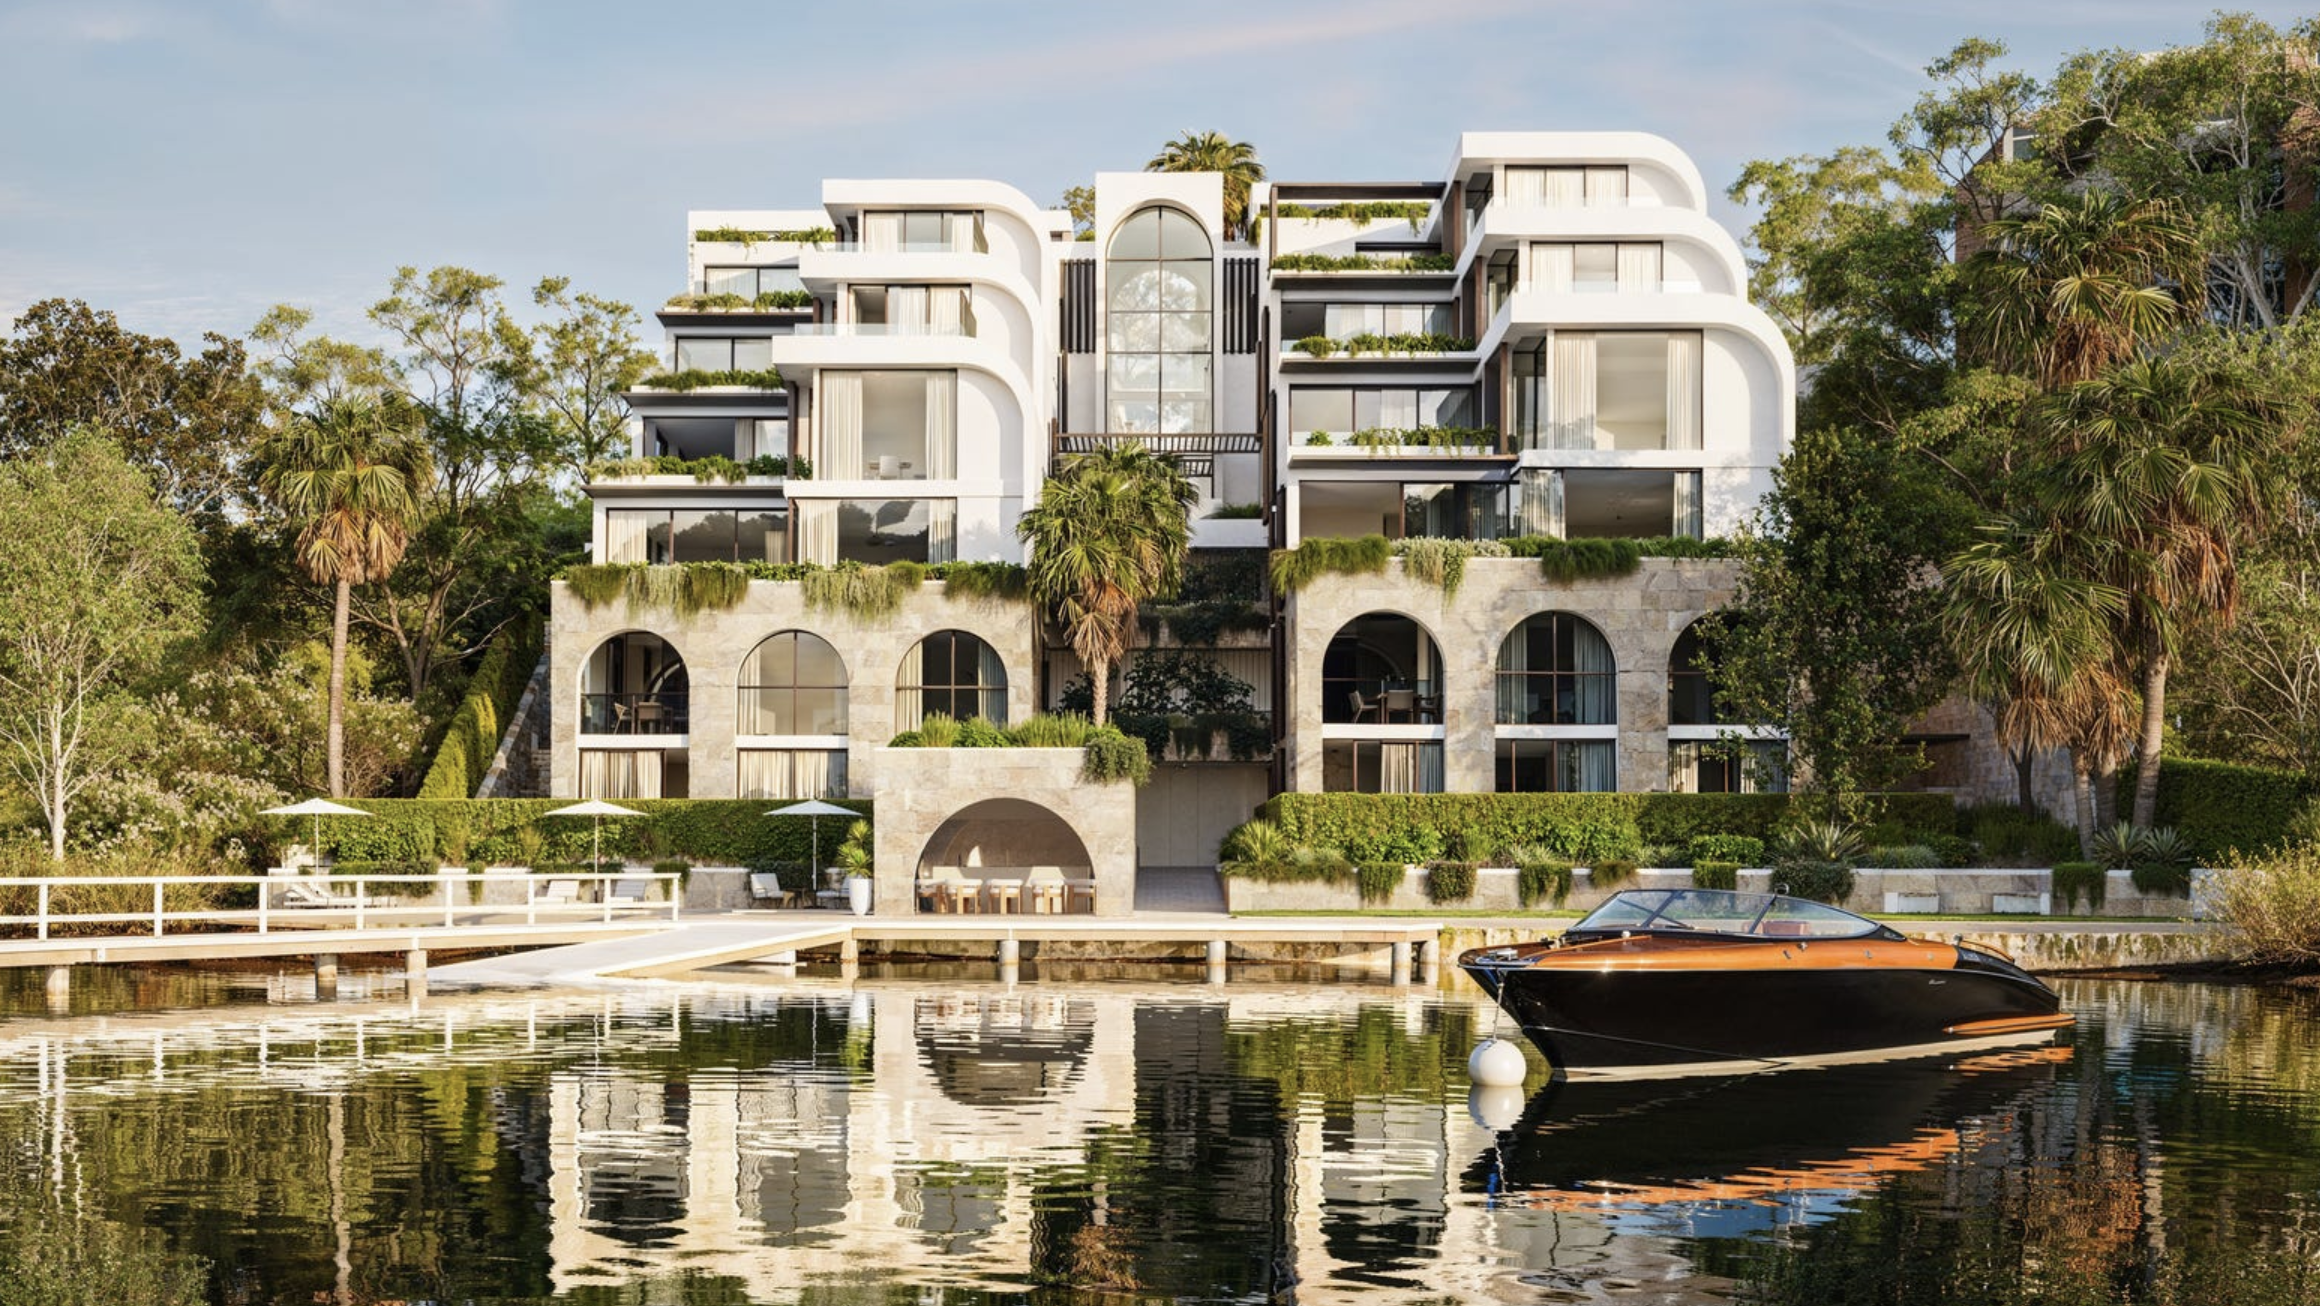
Advertising legend John Singleton unveils an exclusive 16-residence Caroline Bay development, marking his latest high-end property play on the Central Coast.