The Psychologist Who Turned the Investing World on Its Head
Daniel Kahneman gave people an understanding of what drives financial decisions

 6 min
Daniel Kahneman explained investors to themselves.
A psychologist at Princeton University and winner of the Nobel Prize in economics, Kahneman died on March 27, age 90.
Before the pioneering work done by Kahneman and his research partner, Amos Tversky, who died in 1996, economists had assumed that people were “rational,” meaning we are self-interested, use all available information to make unbiased decisions, and our preferences are consistent.
Kahneman and Tversky showed that’s nonsense. Their findings, directly or indirectly, inspired change across the business world, including the redesign of organ-donation programs and improvements in planning for multibillion-dollar infrastructure projects .
Kahneman was a pioneer of what became known as behavioural economics, although he always saw himself as a psychologist. Investors who take Kahneman and Tversky’s lessons to heart can minimise fees, losses and regrets. Kahneman may well have had more influence on investing than anyone else who wasn’t a professional investor.
I first met Danny, as everyone called him, at a conference on behavioral economics in 1996. For years, as an investing journalist, I had wondered: Why are smart people so stupid about money?
About five minutes into Danny’s presentation, I realized he had the answers—not only to that question, but to nearly every mystery of financial behavior.
Why do we sell our winners too soon and hang onto our losers too long? Why don’t we realize that most hot streaks are just luck? Why do we say we have a high tolerance for risk and then suffer the torments of the damned when the market falls? Why do we ignore the odds when we know they’re stacked against us?
Danny paced softly back and forth at the front of the room, his blue-green eyes sparkling with amusement as he documented these behaviors and demolished conventional economic theory.
For decades, he and Tversky had conducted experiments, almost childlike in their simplicity, to see how people really think and behave.
No, Danny said, money lost isn’t the same as money gained. Losses feel at least twice as painful as gains feel pleasant. He asked the conference attendees: If you’d lose $100 on a coin toss if it came up tails, how much would you have to win on heads before you’d take the bet? Most of us said $200 or more.
No, people don’t incorporate all available information. We think short streaks in a random process enable us to predict what comes next. We think jackpots happen more often than they do, making us overconfident. We think disasters are more common than they are, making us suckers for schemes that purport to protect us.
Ask people if they want to take a risk with an 80% chance of success, and most say yes. Ask instead if they’d incur the same risk with a 20% chance of failure, and many say no.
Noting that the stocks people sell outperform the ones they buy, Danny joked that “the cost of having an idea is 4%.”
I wasn’t just struck by his insights; I was stricken by them. I immediately bought all three of the books he had edited. For days, I sat in a windowless room, reading feverishly, red pen in hand, scribbling notes, underlining entire paragraphs, peppering the margins with arrows and exclamation points.
In 2001, a year before Danny won the Nobel, I wrote a long profile of him .
“The most important question to ask before making a decision,” he told me, “is ‘What is the base rate?’”
He meant you should begin every major decision by figuring out the objective odds of success, given the historical range of outcomes in similar situations.
If you’re thinking of starting a new business, your gut might tell you there’s no way you can fail. According to the Bureau of Labor Statistics, however, half of new businesses die within the first five years . That base rate comes from millions of startups, each of which also expected to succeed. You, on the other hand, are a sample of one.
Knowing that the base rate is 50/50 shouldn’t deter you from trying, but it should prevent you from being unrealistically optimistic.
Danny knew base rates weren’t quite everything. He told me that before he proposed to his second wife, Anne Treisman, he said to her: “I’m Jewish, you’re not. I’m neurotic, you’re not. Almost half of all marriages end in divorce. The base rates are against us.”
“Oh, who cares about base rates!” she replied. Their marriage lasted four decades; Treisman died in 2018.
In 1969, Danny was teaching at the Hebrew University in Jerusalem when he asked Tversky, a mathematical psychologist and colleague there, to visit his class.
In his guest lecture, Tversky argued humans aren’t that bad at estimating risks and probabilities.
“I just don’t believe it!” exclaimed Danny, who was studying visual perception. He already believed that just as optical illusions fool the eye, cognitive illusions fool the mind.
The two men continued their debate over lunch—and for many years after . Amos was organised, confident, quantitatively brilliant. Danny was untidy, self-doubting, astoundingly intuitive. Together, they were intellectual lightning in a bottle.
In 1971, to decide whose name would be listed as lead author on the first scientific paper they published together, the two men flipped a coin. Over the next quarter-century, they published more than two dozen papers together.
In 2006, Danny asked me to help him write a book . I auditioned for a few months, coming up with several different proposals for how to structure the project. We finally got started in early 2007.
What eventually emerged was “ Thinking, Fast and Slow ,” published late in 2011: an internationally bestselling memoir that also offered an encyclopedic explanation of how the human mind works.
Early on, Danny took me to lunch with his wife near the Princeton campus. When he stepped away, I asked Anne, “Do you think Danny is crazy for wanting to do this book with me?”
“No,” she said. “But you might be crazy for wanting to do it with him.”
In the beginning, I wrote the first drafts of chapters that never saw the light of day. Gradually, Danny took over the writing, agonizing over every sentence, as I rewrote and edited.
Late in 2007, as we were polishing the chapter called “The Illusion of Validity,” I woke up one night in an icy sweat, pulse racing, gasping for air. My wife rushed me to the emergency room. It turned out I hadn’t had a heart attack; I’d had a panic attack, the only one in my life before or since.
Danny was even more alarmed than I was.
In 2008 I moved on, joining The Wall Street Journal. Neither of us would ever publicly discuss our book divorce; Danny finished the final third of the book without me.
“Collaborations don’t always end well,” he’d warned me on our first day of work together, “so I want to make sure you will always think of me as a mensch,” a good person.
And so I do—the most complicated mensch I’ve ever known.
Working on the book exposed me to three of Danny’s qualities I hadn’t previously encountered in their full intensity. Only years later did I realize that I’ve internalized them as a journalist and an investor. Or so I hope.
First, Danny saw everything through a child’s eyes or, as some people call it, “beginner’s mind.” No one else I’ve ever known has so often asked: Why? Instead of assuming the status quo is valid, Danny always started by wondering whether it made any sense.
He was also relentlessly self-critical. I once showed him a letter I’d gotten from a reader telling me—correctly but rudely—that I was wrong about something. “Do you have any idea how lucky you are to have thousands of people who can tell you you’re wrong?” Danny said.
Finally, Danny could rework what we had already done as if it had never existed. Most people hate changing their mind; he liked nothing better, when the evidence justified it. “I have no sunk costs,” he would say.
One of his favorite words, while working on the book, was “miserable.” He used it to describe whatever we had just written; the process of writing a book; and, above all, himself.
Danny’s misery was largely rooted in the decades he and Amos had spent exploring the failings of the human mind by picking apart their own errors of thought and judgment.
Taking the outside view on everything else had given Danny the outside view on himself. He embodied the ultimate form of self-knowledge: to distrust yourself above all.
He knew full well how smart he was, but he also knew how foolish he could be. Noticing that he intuitively stereotyped a bespectacled child as “the young professor,” Danny realized people extrapolate the future from almost no data at all. After buying an expensive apartment, he laughed at knowing that he would also overpay to furnish it.
Born in 1934 in what today is Tel Aviv, Israel, while his mother was visiting there, Danny was raised in France. He spent much of his childhood hiding from the Nazis in barns and chicken coops in the French countryside.
He insisted that didn’t explain much about him; after all, not every survivor of the Holocaust had become a self-critical psychologist fascinated by financial behavior.
Instead, he credited his success to hard work—but even more to luck, especially meeting Tversky.
Danny also insisted that studying the pitfalls and paradoxes of the human mind didn’t make him any better at problem-solving than anybody else: “I’m just better at recognising my mistakes after I make them.”
For all his knowledge of how foolish investors can be, Danny didn’t try to outsmart the market. “I don’t try to be clever at all,” he told me. Most of his money was in index funds. “The idea that I could see what no one else can is an illusion,” he said.
“All of us would be better investors,” he often said, “if we just made fewer decisions.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
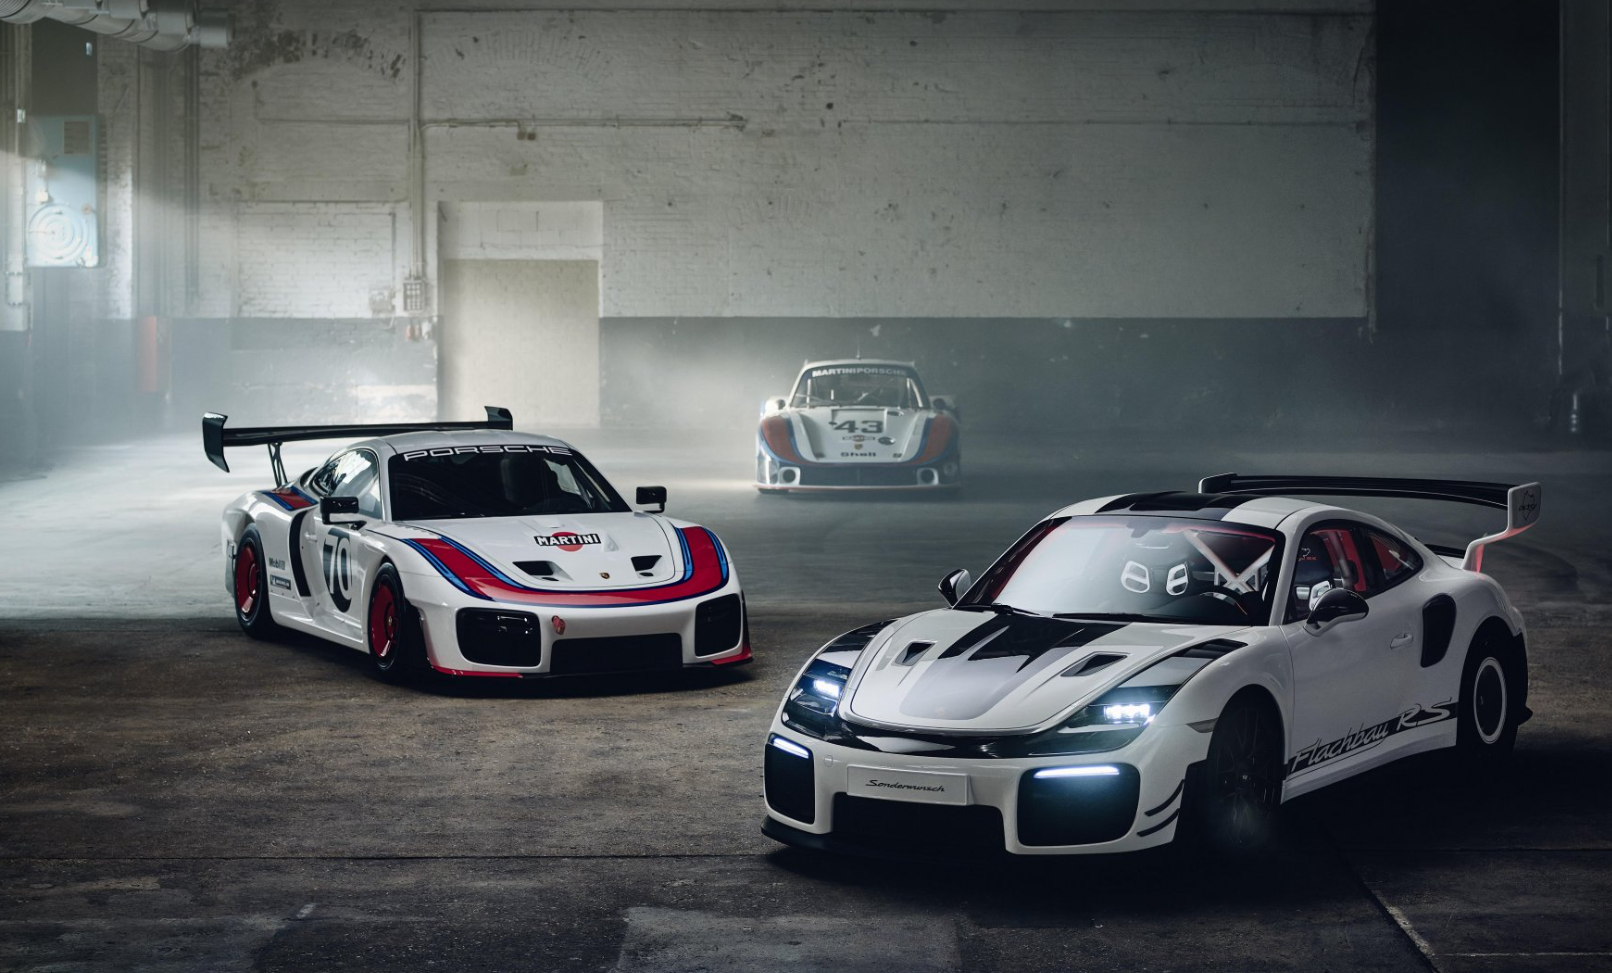
Porsche has revealed a one-off 911 GT2 RS that brings the extraordinary silhouette of its 935/78 “Moby Dick” racing car onto the road. Created by Porsche Sonderwunsch with Manthey, the commission began with a near-new GT2 RS. The owner requested greater performance, a Slantnose profile and a rear wing influenced by the limited 911 GT3 …
Continue reading “Porsche Builds a Road-Going “Moby Dick” From a 911 GT2 RS”

From citrus oils to warming spices, the classic G&T is being reimagined at home as a more thoughtful, seasonal ritual for modern entertaining.