





The Unexpected Ways a Big Raise Affects Your Happiness
Getting more money often leads to immediate satisfaction. The good feelings might not last.

 4 min
Up and down the income ladder, people say more money would make them happier. When they actually get it, that isn’t always the case.
Some people who have gotten big raises recently say the money hasn’t changed their day-to-day life or hasn’t provided them as much joy as the things in their life that have nothing to do with money. Others were hoping for a bigger raise or felt conflicted about making more money.
Jess Tapia, a 28-year-old accountant in Hoffman Estates, Ill., thought for years that $90,000 was a salary that would make her happy. When a raise of about $20,000 pushed her pay to that level last February, it did—at first.
To celebrate, Tapia booked a vacation to Germany the next month. The good vibes soon wore off.
“By the time I came back from that trip, it kind of fell flat for me because it was just back to normal, back to the routine,” she said.
The past few years have been good ones for workers seeking higher pay. Median year-over-year wage growth hit a recent peak of 6.7% in summer 2022, after mostly staying below 4% for more than a decade before 2021, according to the Atlanta Federal Reserve. Many of those who switched jobs, or threatened to, made substantial salary gains.
And people with higher incomes do tend to be happier, many studies show. Research looking at lotteries and random cash giveaways indicates that additional money can make people happier for months or even years.
But moving up the income scale, it takes more money to generate the same good feelings, said Jan-Emmanuel De Neve, an economics professor at Saïd Business School at the University of Oxford who studies well-being. The proportion of the increase matters.
“If an employer moves somebody from $15,000 to $30,000, that will have an impact on people’s life satisfaction that is the equivalent of them moving somebody from, say, $60,000 to $120,000,” De Neve said.
More is more
A pay increase that takes someone from financially stressed to financially stable often leads to more happiness. At the low end of the earnings spectrum, a higher income is associated more with squashing negative feelings than producing positive ones, according to a 2021 paper in the journal Proceedings of the National Academy of Sciences.
Randeep Chauhan, a 30-year-old nurse in Ferndale, Wash., went from making about $45,000 in 2021 to $90,000 in 2022 after completing a one-year nursing program.
“Doubling my income didn’t double my happiness, but it came close,” he said.
For Chauhan, much of the happiness boost came from being able to stop worrying about being able to cover his family’s monthly bills. He said his blood pressure dropped to a healthy level after his change in pay, which he attributes largely to the drop-off in financial stress.
If you get a raise, don’t just spend it, said Neela Hummel, a financial planner and the co-CEO of Abacus Wealth Partners.
“The worst thing that can happen with a raise is that that money gets immediately folded into cash flow and a client doesn’t even notice it,” she said.
Many people also jump ahead to how nice a car or how big a house they could afford with a new paycheck. Instead, Hummel advises, take the raise as an opportunity to up your savings or pay down debt.
Chauhan said he has avoided lifestyle creep, putting money toward retirement savings and student loans instead of buying a new computer or phone. “There’s a weird rush in making money and not spending it,” he said.
Austin Benacquisto’s pay has rocketed upward over the past few years. The 29-year-old commercial debt broker in Atlanta made roughly $60,000 in 2019, $110,000 in 2020, $180,000 in 2021 and $325,000 in 2022, including bonuses.
His steps up to $110,000 and $180,000 felt better than the one up to $325,000, he said.
“The last 50,000 I made in 2022 just was for stuff in my house that I wanted,” he said.
Benacquisto’s pay fell to about $200,000 last year as his industry slowed down. The drop felt worse than the recent increases felt good, he said.
“This being the first decrease, it definitely stings,” he said.
The paycheck next door
People’s happiness with their pay is strongly tied to how it compares with the pay of others around them, say researchers who study compensation. Sometimes, those comparisons rankle.
A 30% raise made Ryan Powell less happy at work.
Powell, a 38-year-old finance director for a manufacturer in western North Carolina, received that pay bump in 2022. He had been hoping for more based on the salary information he had heard from recruiters, peers in the industry and his M.B.A. cohort.
The initial thrill of the raise lasted about three months, he said.
“The further I got into it, the more I was realising that I was anchored to the higher number,” he said.
Executives are more likely to leave their companies if their pay is low compared with other top bosses, according to a 2017 study in the journal Human Resource Management.
Comparisons matter closer to home, too. Living in an area where people tend to make more money than you is linked to being less happy, according to a 2005 paper in The Quarterly Journal of Economics.
One reason that Tapia, the accountant in Illinois, isn’t happier after her raises is that she feels guilt about making more money than her parents ever did. Her dad works in construction and landscaping.
“I work from home mostly, I’m comfortable and I’m always indoors. During summertime, he’s sometimes outside working 10 hours in 100-degree weather,” she said.
Tapia recently got another raise of roughly $10,000. She again booked a vacation to Europe but is hoping to extend her joy further this time.
“I’m starting to feel like this is going to plateau, so let me try and make the feeling last a little longer with this trip,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

MAISON de SABRÉ’s new Spring Harvest Collection turns everyday produce into collectible leather charms and introduces fresh silhouettes in its cult Bucket bag family.
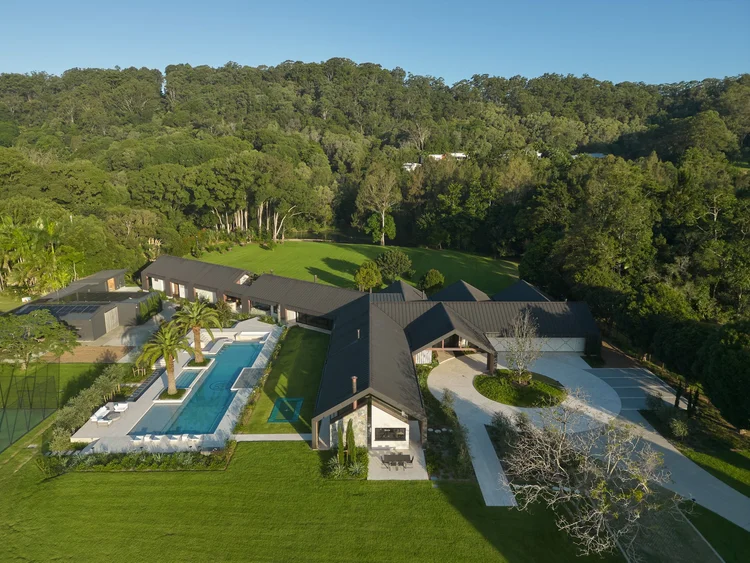
Margot Robbie may have travelled from a Queensland farm to the highest reaches of Hollywood, but a reported $28 million property deal suggests the Gold Coast has never lost its hold on her. The Australian actor and producer is believed to be the mystery buyer of Redwood, a seven-acre Currumbin Valley estate transformed into the …
Continue reading “Margot Robbie Reportedly Behind $28 Million Currumbin Valley Homecoming”


