‘Thrifting’ Extends to Holiday Shopping Too
Roughly 17% of gifts this holiday season will be a resold item, according to Salesforce data

 4 min
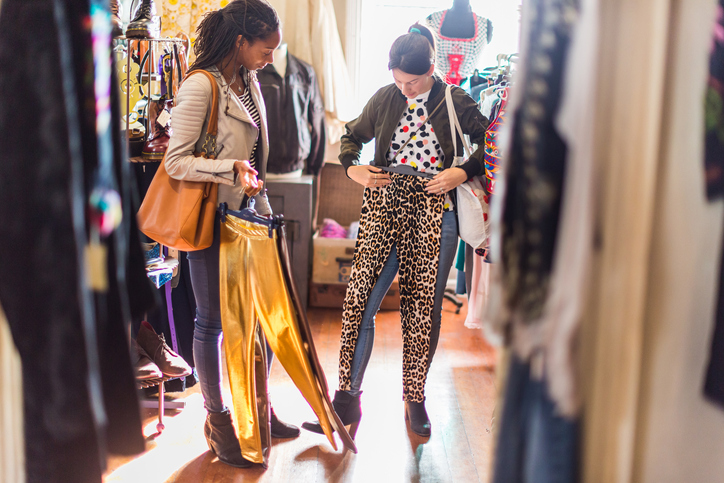
A new kind of present is gaining acceptance this holiday season. More consumers are picking secondhand items to gift each other, finding it to be an environmentally and budget-friendly option.
Thrift stores that sell used clothes and goods are springing up online and on street corners. Goodwill Industries International, the nonprofit behind the familiar chain of thrift stores, is ramping up its online efforts. Fashion brands are developing their own resale offering to keep up with clothing-reseller sites such as Depop and Poshmark. Roughly 17% of gifts this holiday season will be a resold item, according to software firm Salesforce.
“Consumers are choosing resale first because of the incredible value, the unique merchandise, and the incredible sustainability benefit,” said Matt Kaness, chief executive of GoodwillFinds, the nonprofit’s online e-commerce platform run in partnership with Salesforce.
Secondhand clothes, once seen as frumpy and embarrassing, are now keenly sought out by the fashion conscious. A popular vintage aesthetic dovetails with consumer calls for goods that do less harm to the world. About 85% of American shoppers have bought or sold preowned items over the past year, nearly a third for the first time, according to online marketplace OfferUp’s Recommerce report. In apparel alone, some 10% of the global market will be secondhand by next year.
GoodwillFinds is the only major nonprofit player in resale.
GoodwillFinds’ online platform allows a smarter operation than the traditional bricks-and-mortar store, said Kaness, formerly an executive with retailers including Walmart and Urban Outfitters. The platform uses artificial intelligence and large data sets to more accurately price and categorise items, creating a much more efficient system, Kaness said.
“In a store, it’s a human looking at the item. They have paper sticker tickets for the price and they have to process such a volume that it is somewhat random,” he said. In contrast, the company’s online system uses computer vision to take a picture, identify the item, create a listing and price it.
Moving online is the logical choice for secondhand sellers, said 25-year-old Brooke Bowlin, who runs lifestyle blog Nuance Required. “Secondhand stores just can’t sell enough,” said Bowlin, who started her own thrift store in Siloam Springs, Ark. “By moving online and expanding the audience, there is an opportunity to re-home more clothes,” she said.
Major fashion brands are also increasingly recognising that secondhand is as much a necessity as it is an opportunity. The fashion industry is responsible for up to 8% of global emissions, relying on resource-intensive raw materials and fast-moving trends that have contributed large amounts of waste. Around 11.3 million tons of textile waste go to landfills in the U.S. every year, according to environmental organisation Earth.Org.
Outdoor-clothing retailer Patagonia established its Worn Wear platform in 2017, one of the first resale channels by a major brand.
As much as adapting to trends, Patagonia Worn Wear aims to change consumer behaviour, said Asha Agrawal, managing director of the Patagonia venture fund that runs the platform.
“A lot of our messaging is around—‘you don’t need to buy something new,’” she said.
Worn Wear buys back used brand gear from consumers by paying higher prices than peer-to-peer apps or other marketplaces, Agrawal said. This strategy contributes to the bulk of the platform’s costs but also boosted its inventory fourfold this year alone, she said, adding Worn Wear has been profitable for the last two years.
Worn Wear is now integrated into the Patagonia brand. “You can now do your main shopping with Patagonia with our resale business in the U.S.,” she said. “That’s a huge evolution for us.”
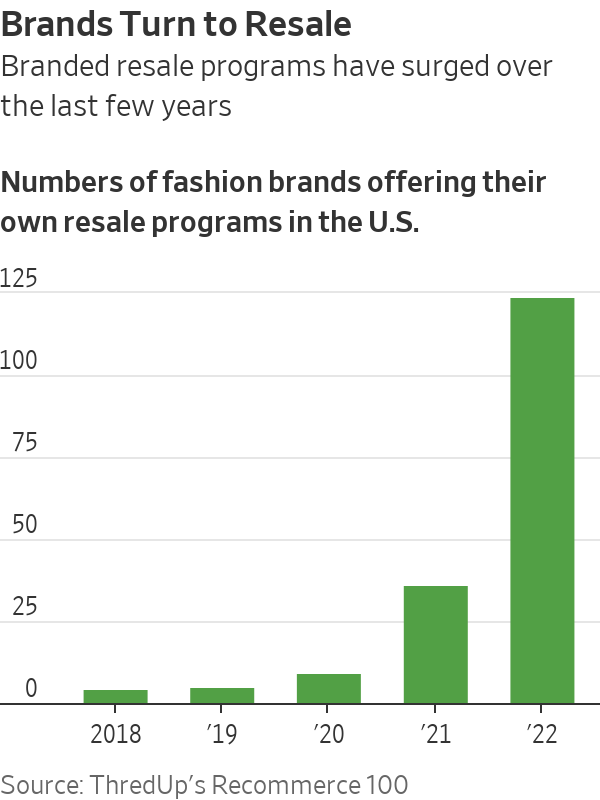
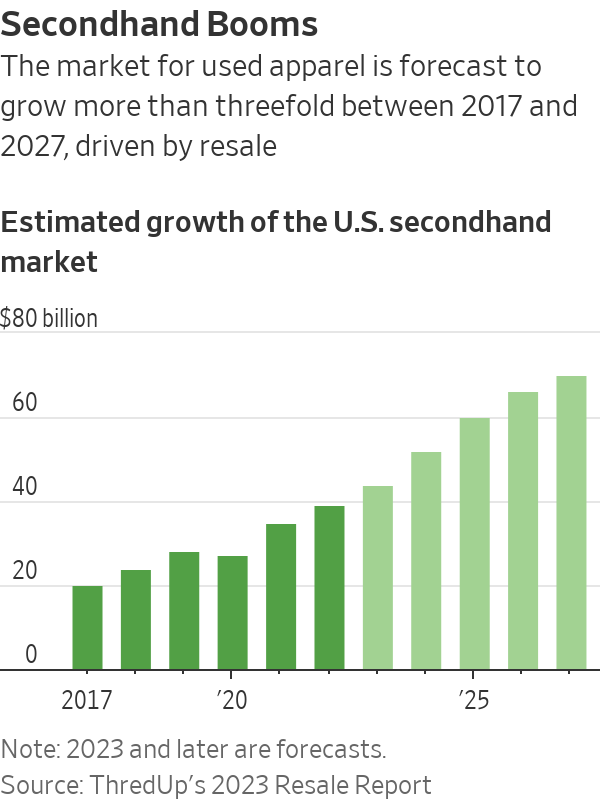
Resale by brands and third parties is expected to outpace traditional thrift sales and donations in the U.S., rising to 60% of a $70 billion total by 2027 from 15% of the $20 billion secondhand market in 2017, according to online thrift store ThredUp’s recent resale report.
Other fashion players have their versions. Sweden’s Hennes & Mauritz launched H&M Pre-Loved in the U.S. this year, in partnership with ThredUp. Inditex-owned Zara has launched a preowned platform that offers repair services, customer-to-customer sales and donations of used garments in the U.K. and France, with plans for a U.S. rollout by 2025.
Resale remains an imperative for fashion brands as a way to control distribution and retain the trust of shoppers increasingly alert to the fate of their old clothes. However, scaling up resale generates a raft of operational challenges such as authentication, returns and ensuring that secondhand doesn’t look like an afterthought, said Anita Balchandani, fashion lead at consultant firm McKinsey & Co.
Unlike nonprofits, such as Goodwill, that get their inventory from donations and don’t have to be accountable to shareholders, retailers are struggling to make business sense of resales, Balchandani said.
“No one has proven the path to scaling this up profitably,” she said. “You almost have to create a whole new end-to-end supply chain…. The retailer who cracks that journey is going to make a real difference in this space.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
When the Writers Festival was called off and the skies refused to clear, one weekend away turned into a rare lesson in slowing down, ice baths included.

Pure Amazon has begun journeys deep into Peru’s Pacaya-Samiria National Reserve, combining contemporary design, Indigenous craftsmanship and intimate wildlife encounters in one of the richest ecosystems on Earth.