Why the Drivers of Lower Inflation Matter
Competing effects of central banks, healing supply chains affect recession odds

 4 min
Recent good news on inflation has ignited a debate over how much central banks’ interest-rate increases are responsible.
The answer matters for where inflation and interest rates are headed. The Federal Reserve and the European Central Bank in the past week lifted their benchmark interest rates to 22-year highs and left the door open to additional increases.
If higher rates weren’t responsible for the progress on inflation to date, that suggests central banks may be able to lower them before a painful recession sets in.
Central banks generally see their influence on inflation coming through higher rates damping the demand for goods, services and workers, which leads to higher unemployment. That in turn puts downward pressure on prices and wages.
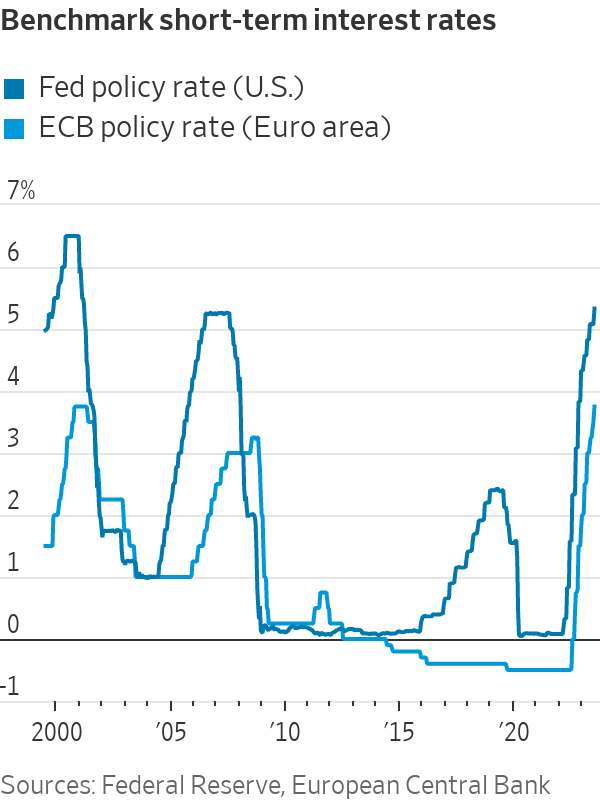
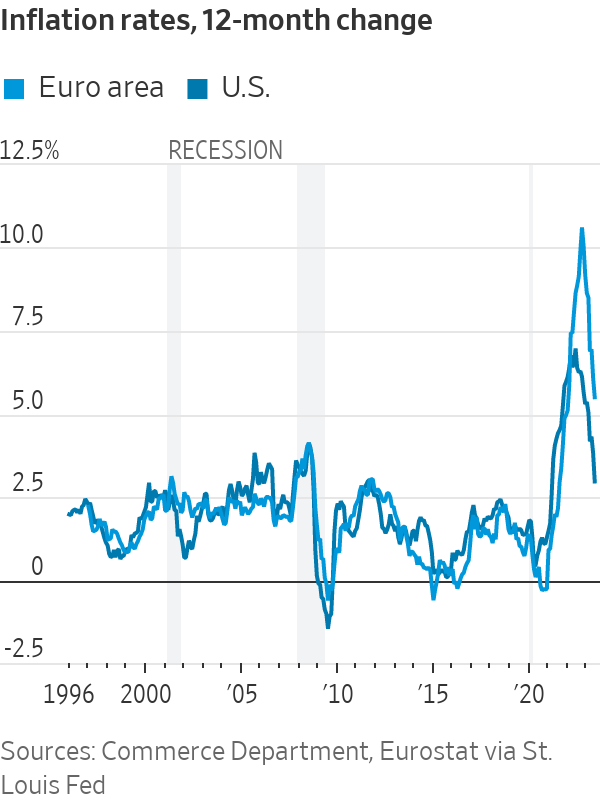
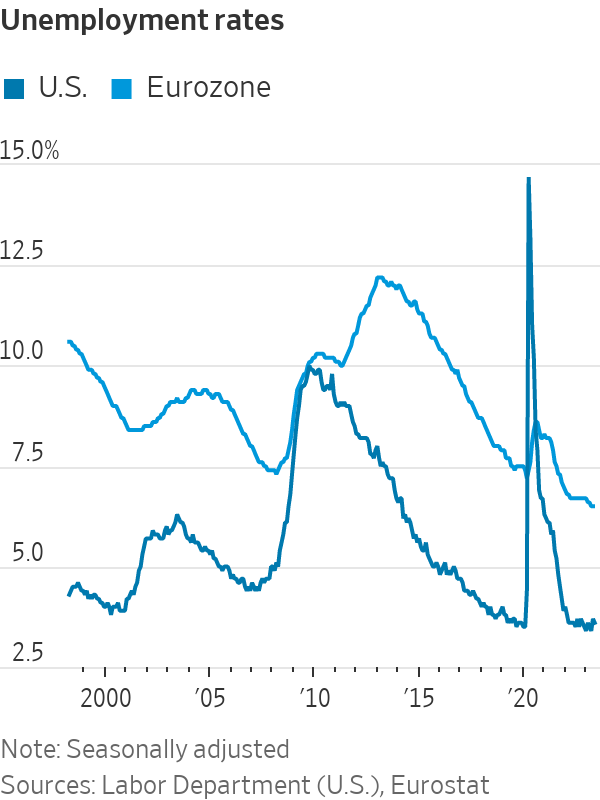
Only the second part of that sequence has occurred. Inflation fell to 3% in the U.S. in June, according to the Fed’s preferred gauge, the personal-consumption expenditures price index, down from 7% one year earlier. Yet the unemployment rate, at 3.6% in June, has held steady for the past year.
In the eurozone, inflation declined to 5.5% in June, the lowest level in nearly 18 months, and unemployment has drifted to the lowest in more than 25 years.
There are competing explanations for this.
One camp argues that inflation has been mostly driven by supply shocks that are going away on their own—much as a postwar surge in the late 1940s unwound by itself. The ripple effects gave the illusion of broader, more persistent price increases.
Take the auto market. Sellers weren’t able to meet pent-up demand two years ago, leading to huge price increases, which in turn spawned higher prices later on for car repairs and auto insurance.
Similarly, a surge in household formation during the pandemic sent up housing prices and rents.
The first camp attributes most of the recent decline in inflation to the ebbing of these one-time supply disruptions, not rate increases, which are supposed to work through the labor market. “It’s calling into question a lot of the old assumptions,” said Lindsay Owens, executive director at the Groundwork Collaborative, a liberal think tank.
A second camp, which includes most economists, disagrees. They say monetary policy kept demand for goods, services, and labor lower than otherwise, taking pressure off strained supply chains and allowing price pressures to ease.
Interest rates can also influence behaviour. The prospect that central bankers would risk a recession to bring down inflation may have influenced expectations of price- and wage-setters, including corporate executives who plan annual budgets for investment and hiring.
Jamie Dimon, chief executive of JPMorgan Chase, warned one year ago of an economic “hurricane” as central banks accelerated rate increases. “You’d better brace yourself,” he said in June 2022, and pledged the bank would be “very conservative” with its balance sheet.
“Inflation is coming down precisely because the Fed avoided more excess demand growth, and they anchored inflation expectations,” said Angel Ubide, head of economic research for global fixed income at Citadel, a hedge-fund firm.
Inflation would be higher now if not for Fed rate increases, “and maybe still rising,” said Karen Dynan, an economist at Harvard University.
In 2021, supply-chain constraints meant even marginal increases in demand led to unusually large price increases. The reverse might be true now: Marginal decreases in demand can bring down prices faster, particularly if more supply is becoming available.
The car market illustrates how monetary policy has been transmitted. Rising rates raised monthly payments, damping demand and robbing sellers of pricing power. In addition, since March, banks appear to be rejecting more car-loan applications.
“That’s leading to a new group of people getting squeezed out of the market, and therefore, it’s playing a role putting downward pressure on prices,” said Julia Coronado, founder of economic-advisory firm MacroPolicy Perspectives.
In Europe, economic growth has stalled since late last year. Business surveys in the past week suggest that growth is weakening sharply, especially in manufacturing, which is most sensitive to interest rates.
The net share of banks reporting increased loan demand declined to a record low in the three months through June, according to an ECB survey of banks. Credit growth to households is the lowest since mid-2016.
Asked at a news conference on Thursday about the transmission of ECB rate increases to growth and inflation, President Christine Lagarde said that in the financial system, “a lot has been transmitted. A lot. We know that. In the economy at large, not as much yet.”
A report published by German insurer Allianz identifies three different forces on the U.S. inflation rate since the second quarter of 2022. Higher inflationary pressures from consumption growth, strong labor markets and government spending added 4 percentage points; fading supply-chain disruptions subtracted five points, and Federal Reserve actions subtracted another five. The net impact was that inflation fell 6 percentage points, whereas it would have fallen only one point without the Fed’s actions.
Fed Chair Jerome Powell said rate increases are “working about as we expect, and we think it’ll play an important role going forward” in bringing down prices for the most labor-intensive services.
Monetary policy has also affected the labor market, but this has shown up in declining job-vacancy rates rather than rising unemployment, some economists say.
Hiring plans in the eurozone services sector are dropping rapidly, according to a survey this month by the European Commission, the European Union’s executive body.
“The labor market is normalising on both sides of the Atlantic, reflecting the impact of higher rates,” said Stefan Gerlach, a former deputy governor of Ireland’s central bank.
The debate over the effect of rate increases also matters for how much further, if at all, central banks need to lift them. Optimists underestimated how much strong demand lifted inflation two years ago. Pessimists may be overestimating the importance of constraining demand to bring it down now.
Gerlach expects inflation to continue declining as higher rates sap demand. “I’m worried central banks have done too much,” he said. “They may have felt embarrassed about having misunderstood inflation the first time.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.

A survey of people with at least $1 million in investable assets found women in their 30s and 40s look nothing like older generations in terms of assets and priorities
Advertising legend John Singleton unveils an exclusive 16-residence Caroline Bay development, marking his latest high-end property play on the Central Coast.