Why the Recession Is Always Six Months Away
Continued strong hiring and consumer spending are complicating Federal Reserve Chair Jerome Powell’s campaign to tame inflation.

 7 min
The next economic downturn has become the most anticipated recession in recent U.S. history. It also keeps getting postponed.
Recent strong hiring and consumer spending are the latest evidence that the pandemic and the unprecedented policy measures that followed are interfering with the Federal Reserve’s campaign to tame inflation.
The government’s stimulus measures left household and business finances in unusually strong shape. Shortages of materials and workers mean companies are still struggling to satisfy demand for rate-sensitive goods, such as homes and autos. And Americans are splurging on labor-intensive activities they avoided in recent years, including dining out, travel and live entertainment.
Wall Street economists began 2023 broadly anticipating a recession by mid-year caused by the weight of the Fed’s rapid interest-rate increases. Some still expect that could happen. Many now think it will take longer to cool the economy and will lead the central bank to raise rates to higher-than-expected levels.
“It’s the ‘Godot’ recession,” said Ray Farris, chief economist at Credit Suisse. Mr. Farris found himself among a small minority of economists last fall who predicted the economy would narrowly skirt a downturn this year. Every six months, economists have predicted a recession six months later, he said. “By the middle of the year, people will still be expecting a recession in six months’ time.”
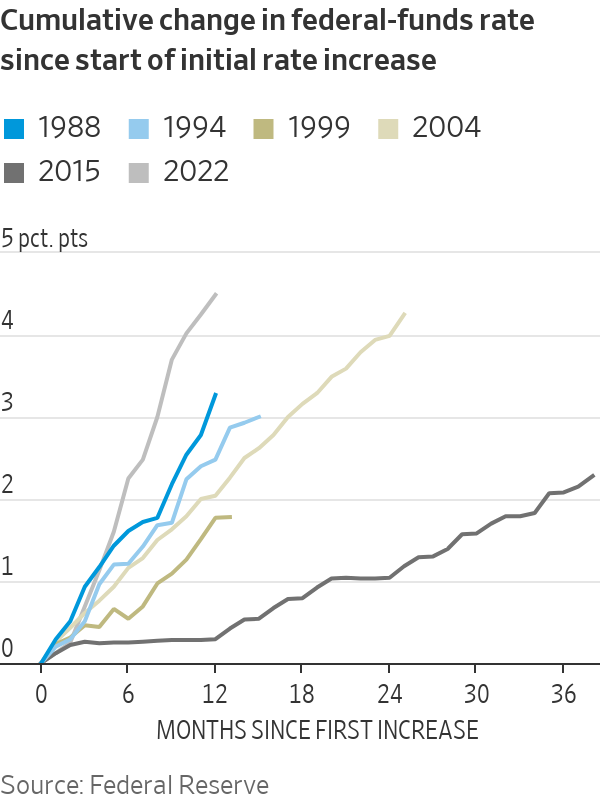
The Fed has been trying to slow investment, spending and hiring to combat inflation by raising rates, which makes it more expensive to borrow and can push down the price of assets such as stocks and real estate. After holding the benchmark federal-funds rate near zero during and after the pandemic, officials lifted the rate more over the past 12 months than any time since the early 1980s, most recently to between 4.5% and 4.75% last month.
The economy’s recent pickup will delay Fed officials’ deliberations about when to pause rate increases. Investors are instead looking for clues about whether they will raise rates by a quarter-percentage-point, as they did last month, or a half-point, as they did in December, at their next meeting, March 21-22.
Fed Chair Jerome Powell is set to begin two days of congressional testimony Tuesday, where he’ll have an opportunity to explain the central bank’s most likely response to a more resilient economy. In December, most Fed officials expected to lift rates this year to between 5% and 5.5%, and officials have indicated those projections could rise at their next meeting.
The economy remains weird
Three factors illustrate the peculiar nature of today’s economic recovery.
First, Washington’s reaction to the initial shock of Covid-19 in March 2020, including holding interest rates at very low levels and showering the economy with cash, left household, business, and local government finances in unusually strong shape.
Through last June, U.S. households had around $1.7 trillion more in savings accumulated through mid-2021 than if income and spending had grown in line with the pre pandemic economy, according to estimates by Fed economists. Even after it is spent, money can still slosh through the economy (one person’s spending is, after all, someone else’s income).
“We are going through the second, third, and fourth-round effects of the initial savings spurred by all these transfer payments during the pandemic,” said Peter Berezin, chief global strategist at BCA Research in Montreal. Rate increases can slow the economy more immediately when expansions are fuelled by credit growth, as opposed to incomes and stimulus, the big drivers of the post-pandemic recovery.
Businesses were able to lock in lower borrowing costs as interest rates plumbed new lows in 2020 and 2021. Just 8% of junk bonds, or those issued by companies without investment-grade ratings, mature over the next two years, according to Goldman Sachs.
Secondly, shortages of materials and workers have made the rate-sensitive housing and auto markets more resilient to higher interest rates—for now. Home builders are resorting heavily to what’s known as buydowns, where they pay to lower the buyer’s mortgage rate for the first year or two. Many current owners are reluctant to sell because they’d have to give up a much lower rate, a phenomenon that is holding for-sale inventories at historically low levels.
Typically when the Fed raises interest rates, demand for housing and cars fall, leading builders and automakers to cut production and lay off workers. This time around, companies are still playing catch-up.
Construction employment hasn’t fallen despite a severe slump in home sales. Builders are still completing homes and apartments started before the Fed increased interest rates. Supply-chain disruptions have extended the amount of time it takes to complete construction. In addition, apartment building ramped up sharply after the pandemic, and those take longer to finish.
In the auto sector, brands of popular fuel-efficient cars are benefitting from pent-up demand after shortages of semiconductor chips kept inventories of new cars at very low levels.
That could make the usual rate-induced slowdown in autos and housing more gradual, said Eric Rosengren, who was president of the Federal Reserve Bank of Boston from 2007 until 2021. “It may take higher interest rates or interest rates higher for longer to get supply and demand back in alignment.”
Thirdly, U.S. consumers, throwing off their pandemic caution, have ramped up spending on services that require lots of workers—think dining out and travel—another example of pent-up demand interfering with the typical business and interest-rate cycle.
Those sectors are often among the first to see demand fall, prompting job cuts, when consumers worry about losing theirs. The easiest way for households to reduce their expenses is to stop eating out and taking vacations.
Consumer spending has enjoyed a rebound in recent months thanks to lower gasoline prices and an additional boost in January from bigger Social Security checks, which are indexed to prior-year inflation. Gas prices jumped last spring after Russia’s invasion of Ukraine. They then steadily declined over the second half last year, easing a cash-crunch for some households that may have offset higher rates on auto loans, credit cards, and mortgages, said economists at Morgan Stanley in a recent report.
Economists at Goldman Sachs said Sunday the Fed could end up raising rates to just below 6% this year if consumer spending runs at higher-than-anticipated levels. That could extend a string of quarter-point rate increases into September.
Labor market conundrum
The labor market sits at the centre of Mr. Powell’s worries about inflation. That’s because steady income growth will sustain consumer spending power and allow companies to keep raising prices.
In the 2000s, then-Fed Chairman Alan Greenspan called it a conundrum that longer-dated bond yields stubbornly refused to rise as the Fed increased rates. For Mr. Powell, the labor market’s strength represents his version of the conundrum. Recession calls keep getting delayed because companies keep hiring and holding on to workers rather than letting them go.
Employers added 517,000 jobs in January, a big figure that shocked economists who were anticipating a slowdown, and pushed the unemployment rate down to 3.4%, a 53-year low. Revisions to earlier reports also pointed to less weakness than initially thought.
The Labor Department’s report on February hiring, due for release Friday, will offer clues as to whether January’s was a one-off blip or a sign of an economy that’s accelerating. A separate report Wednesday could show whether workers continue to quit their jobs at historically high rates, which can indicate greater confidence in their ability to find new jobs with better pay.
Economists at Morgan Stanley estimate that staffing levels across the U.S. are still slightly below what would have been if the pandemic hadn’t hit. They expect that gap to close this year, which could lead hiring rates to slow.
M. Keith Waddell, chief executive of recruiting firm Robert Half International Inc., highlighted a disconnect between a resilient labor market and business surveys that point to signs of easing demand for workers. “Having said that, orders have not dried up,” he said on a Jan. 26 earnings call. “It’s just taking longer to get them closed. Our clients are less urgent. They’re taking more steps. They want to see more candidates.”
Fed officials are in a race to slow down the economy before inflation becomes entrenched. They are also trying to guard against raising rates too much and causing unnecessary economic pain.
Some Fed officials say it could take time to see the effects of their moves, because they had pursued such ultra-stimulative policies until a year ago. Because interest rates have only very recently reached levels that could be considered restrictive, “there is a plausible case to suggest that we’re going to see” more slowing to come, Atlanta Fed President Raphael Bostic told reporters last week.
Business owners report confidence about their own prospects but unease about the broader economic backdrop, said Mr. Bostic. “Everyone is wondering if and when the shoe will drop, but they’re all expecting it to drop for somebody else,” he said.
The need for speed
Uncertainty over when and how much the economy will slow is due in large part to Mr. Powell’s decision to raise interest rates rapidly. The Fed previously spaced out increases, such as in the periods 2004 to 2006 and 2015 to 2018, when lower inflation allowed officials to move more gradually.
The strategy appeared to work because it prevented households and businesses from expecting higher future inflation, which would have kicked off a destructive price spiral, said Kristin Forbes, a professor at the Massachusetts Institute of Technology and former member of the Bank of England’s monetary policy committee. Now, the downsides of that strategy are coming into view.
“If you front-load hikes, it makes it harder to tell whether you need to wait a little longer to see the effects, or whether the economy is just more resilient,” she said.
Officials slowed the pace of rises in December and again last month to have more time to study the effects of their past moves. Despite reports of hotter growth and inflation over the past month, Mr. Rosengren sees the slower rate-rise pace as appropriate. “You still are waiting for information about when the previous tightenings are going to have more of an impact,” he said. The timing of a recession “is impossible to predict, but the likelihood remains quite high,” he said.
Since October, the Fed has faced a challenge in which bond investors began to anticipate inflation would fall quickly without a serious downturn. As a result, they expected the Fed would cut rates sooner and faster than central bank officials said they anticipated.
That risked an unhelpful feedback loop for the Fed. While the central bank controls short-term interest rates, long-term rates are influenced by broader market conditions, and they ticked lower between October and February, leading borrowing costs to ease slightly. The 30-year fixed rate mortgage slid to around 6% from 7% last fall.
That has led to a perverse sequence where expectations that the economy will slump are holding down long-term rates, which can stimulate economic activity and make it harder for the economy to slump.
Long-term Treasury yields have since ticked up as investors become more concerned about inflation and stopped believing the Fed would cut rates anytime soon. A big question is whether the run-up in yields will be enough to shift the economy into the slower gear the Fed seeks.
“The Fed needs to get long-term yields high enough to slow the economy,” said Mr. Berezin. “There won’t be a recession until more people are convinced that there won’t be a recession.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From Italian vegetable-tanned leather to real-world training insight, Australian brand PK9 Gear is redefining what luxury means for discerning dog owners.

Rugged coastal drives and fireside drams define a slow, indulgent journey through Scotland’s far north.