Boost for World Economy as U.S., Eurozone Accelerate in Tandem
Surveys point to a fresh acceleration in the U.S., even as growth in the eurozone strengthens

 3 min
Global economic growth is becoming more broad based, with surveys indicating that business activity in both the U.S. and the eurozone gained momentum in May.
The eurozone economy contracted in the second half of 2023 following a surge in energy and food prices triggered by Russia’s invasion of Ukraine, and the subsequent rise in interest rates intended to tame that inflation.
By contrast, the U.S. economy expanded strongly over the same period, opening up an unusually wide growth gap with the eurozone. That gap narrowed as the eurozone returned to growth in the first three months of the year, while the U.S. slowed.
However, surveys released Thursday point to a fresh acceleration in the U.S., even as growth in the eurozone strengthened. That bodes well for a global economy that relied heavily on the U.S. for its dynamism in 2023.
The S&P Global Flash U.S. Composite PMI —which gauges activity in the manufacturing and services sectors—rose to 54.4 in May from 51.3 in April, marking a 25-month high and the first time since the beginning of the year that the index hasn’t slowed. A level over 50 indicates expansion in private-sector activity.
“The data put the U.S. economy back on course for another solid gross domestic product gain in the second quarter,” said Chris Williamson, chief business economist at S&P Global Market Intelligence.
Eurozone business activity in turn increased for the third straight month in May, and at the fastest pace in a year, the surveys suggest. The currency area’s joint composite PMI rose to 52.3 from 51.7.
The uptick was led by powerhouse economy Germany, where continued strength in services and improvement in industry drove activity to its highest level in a year. That helped the manufacturing sector in the bloc as a whole grow closer to recovery, reaching a 15-month peak.
By contrast, surveys of purchasing managers pointed to a slowdown in the U.K. economy following a stronger-than-expected start to the year that saw it outpace the U.S. The survey was released a day after Prime Minister Rishi Sunak called a surprise election for early July, banking on signs of an improved economic outlook to turn around a large deficit in the opinion polls.
Similar surveys pointed to a further acceleration in India’s rapidly-expanding economy, and to a rebound in Japan, where the economy contracted in the first three months of the year. In Australia, the surveys pointed to a slight slowdown in growth during May.
Businesses reported that they were raising their prices at the slowest pace since November, which should reassure the European Central Bank. However, the eurozone continued to add jobs in May, suggesting that wages might not cool as rapidly as the ECB had hoped.
The ECB released figures Thursday that showed wages negotiated by labor unions in the eurozone were 4.7% higher in the first quarter than a year earlier, a faster increase than the 4.5% recorded in the final three months of 2023
The ECB has signalled it will lower its key interest rate in early June, while the Fed is waiting for evidence that a slowdown in inflation will resume after setbacks this year.
Nevertheless, eurozone businesses and households shouldn’t bank on successive cuts to borrowing costs, ECB Vice President Luis de Guindos said. “There is a huge degree of uncertainty,” he said. “We have made no decisions on the number of interest rate cuts or on their size,” he said in an interview published Thursday. “We will see how economic data evolve.”
Continued resilience in the eurozone economy would likely make the ECB more cautious about lowering borrowing costs after its first move, economist Franziska Palmas at Capital Economics wrote in a note. “If the economy continues to hold up well, cuts further ahead may be slower than we had anticipated,” she said.
– Edward Frankl contributed to this story.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
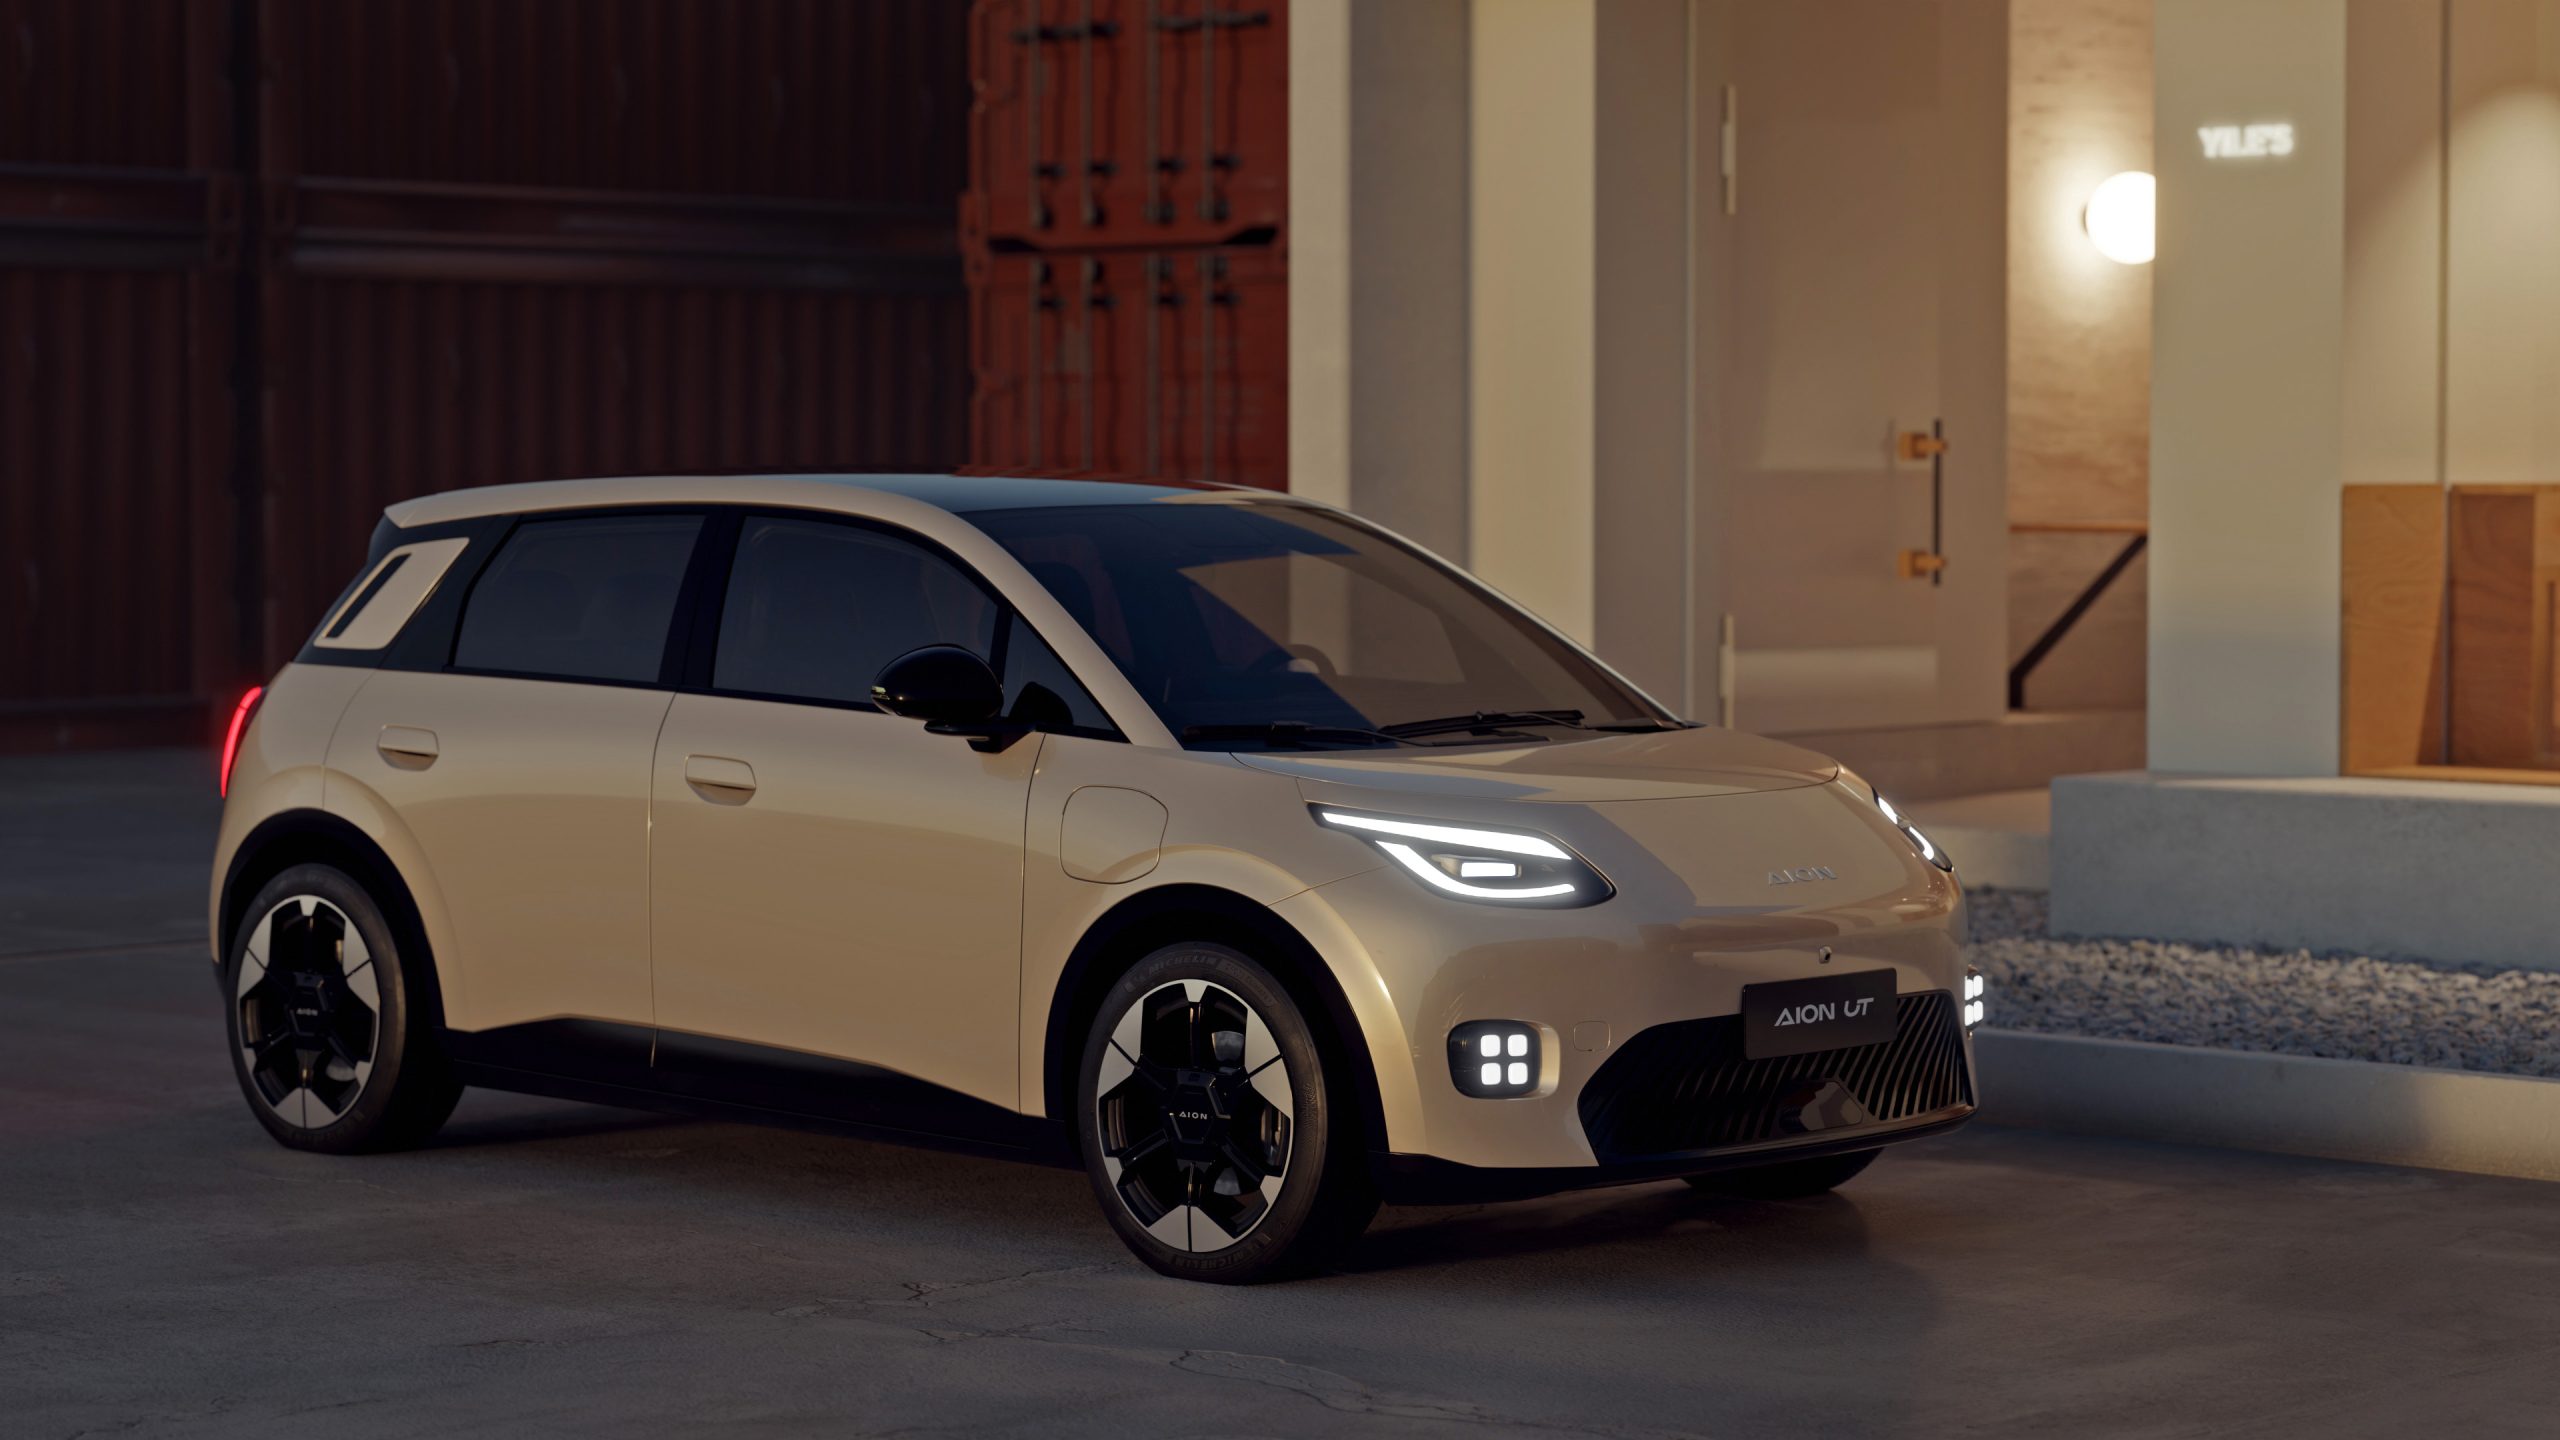
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.
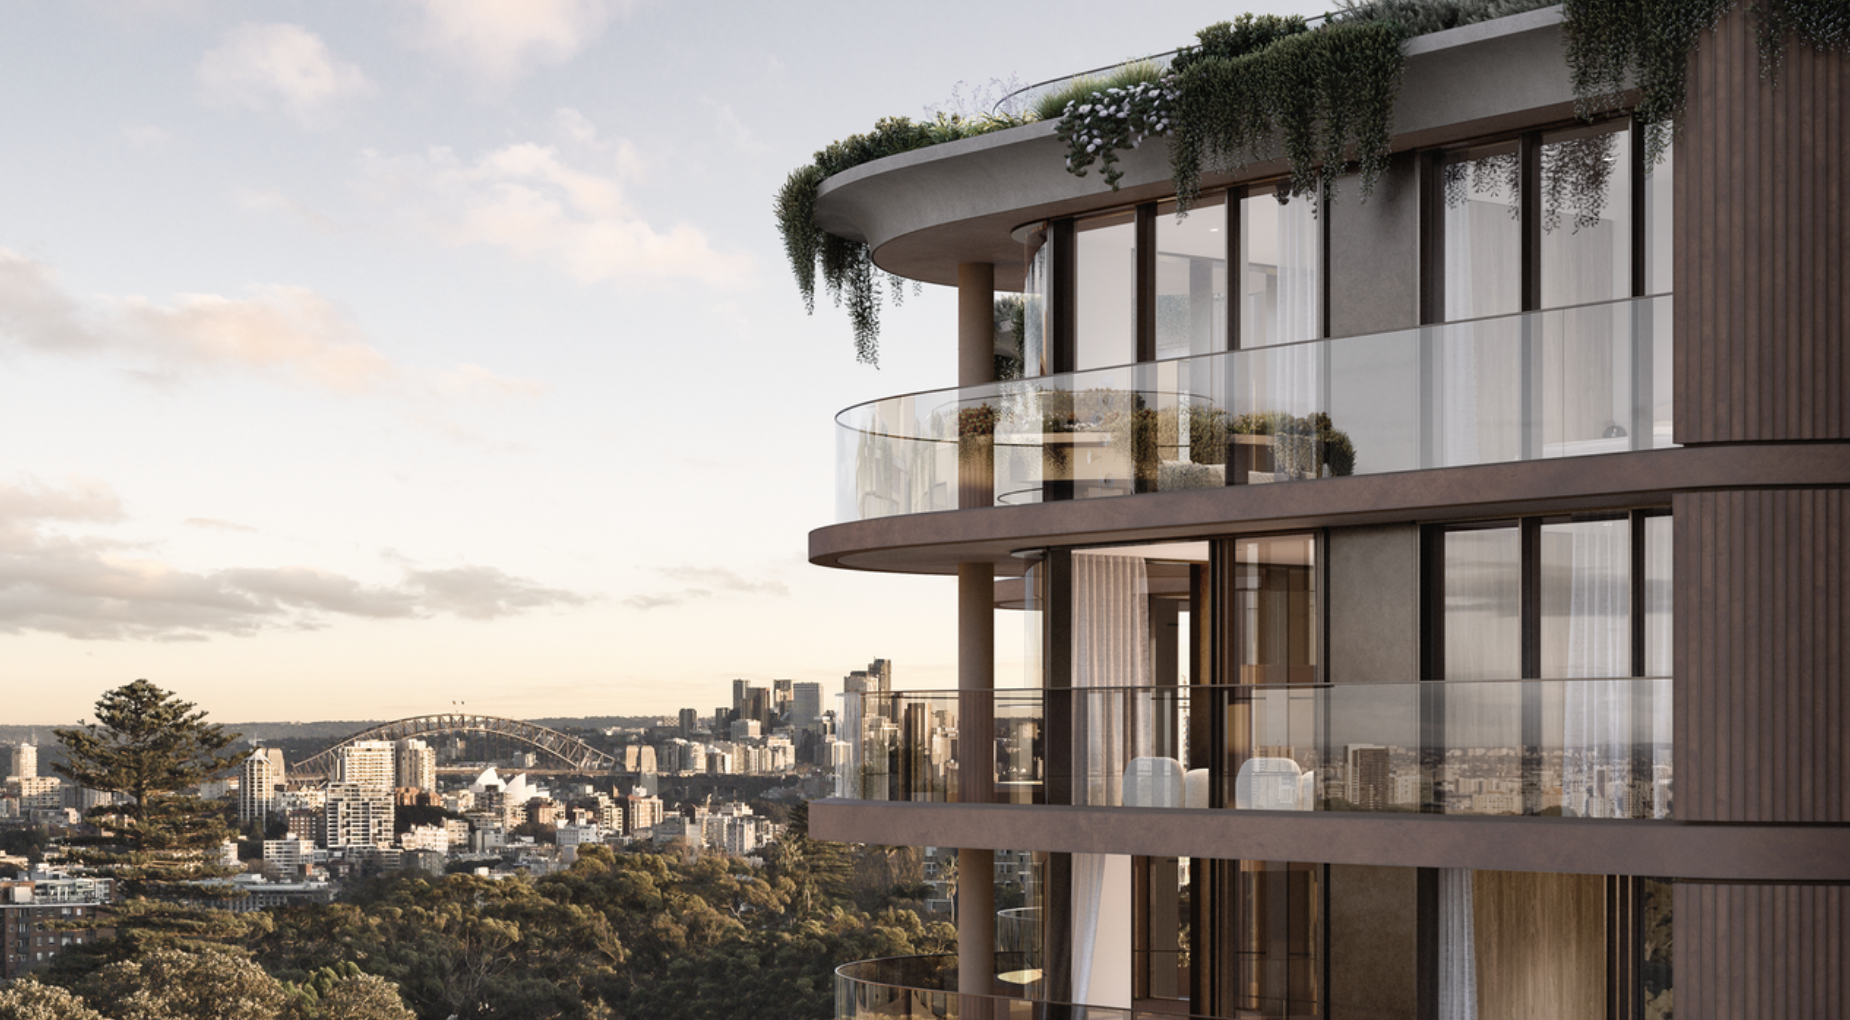
A record-breaking $11 million sale at The Centennial Collection has set a new benchmark for luxury apartment living in Bondi Junction.