As Generation X Approaches Retirement, Reality Still Bites
The ‘forgotten generation,’ born between 1965 and 1980, launched their careers at the start of a massive shift in how Americans work.

 7 min
The oldest members of Gen X are turning 60 next year. Many can’t afford to stop working any time soon.
Born between 1965 and 1980, Gen Xers launched their careers at the start of a massive shift in how Americans work. Companies moved from pensions that promise steady income after years of service, to plans such as 401(k)s that place employees’ retirement destiny in their own hands.
Some Gen Xers were hit hard in their prime working years during the 2008 financial crisis. Others are still paying off student debt. Their children are increasingly living at home well into adulthood, while their own aging parents often require care. Few believe they can rely on Social Security to make ends meet later in life.
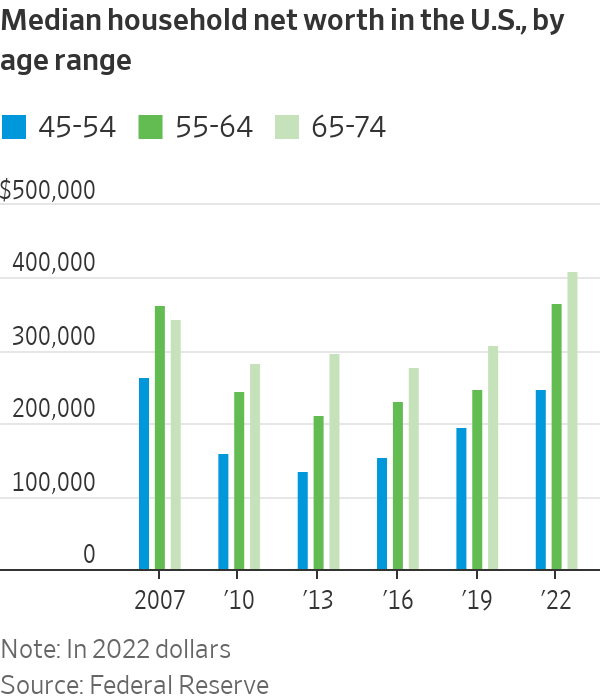
By some measures, Gen Xers are worse off financially than their baby boomer predecessors. The median household net worth of Gen Xers between 45 and 54 years old was about $250,000 in 2022, about 7% lower than that of baby boomers at the same age in 2007, according to inflation-adjusted Federal Reserve data. That was the only age group that experienced a drop in median wealth over the 15-year period.
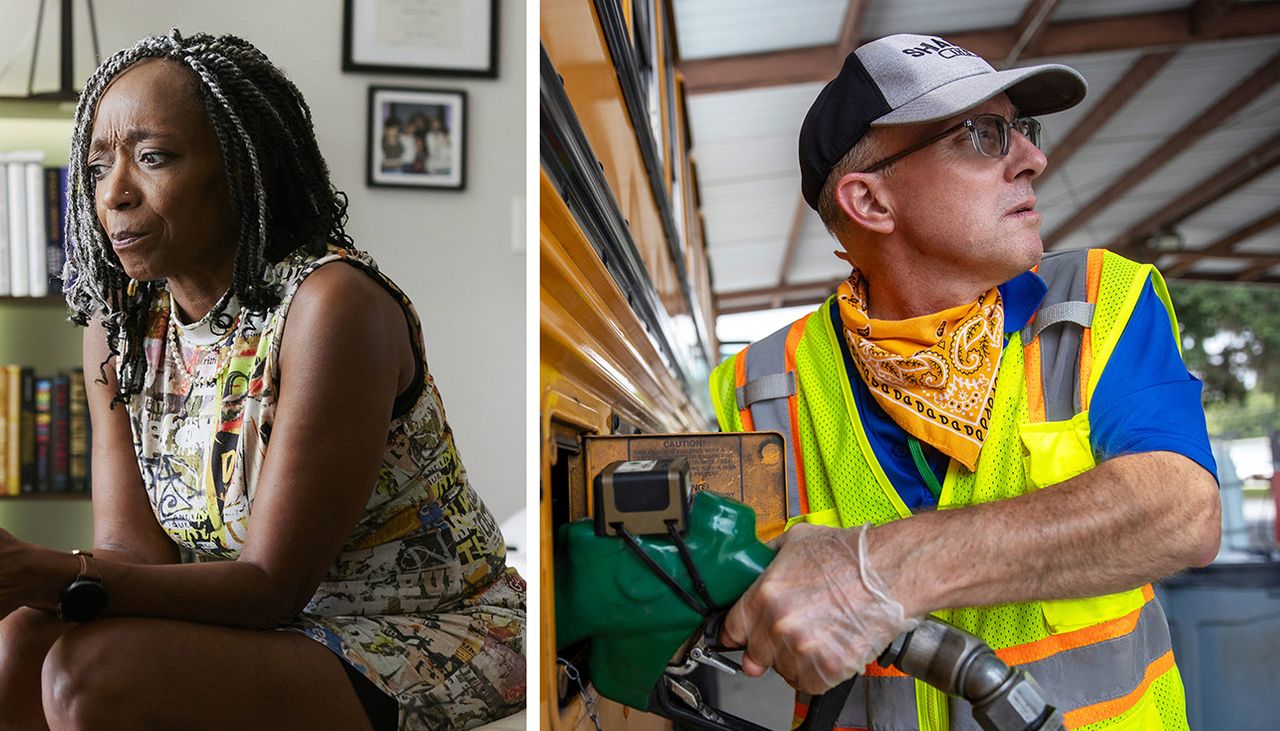
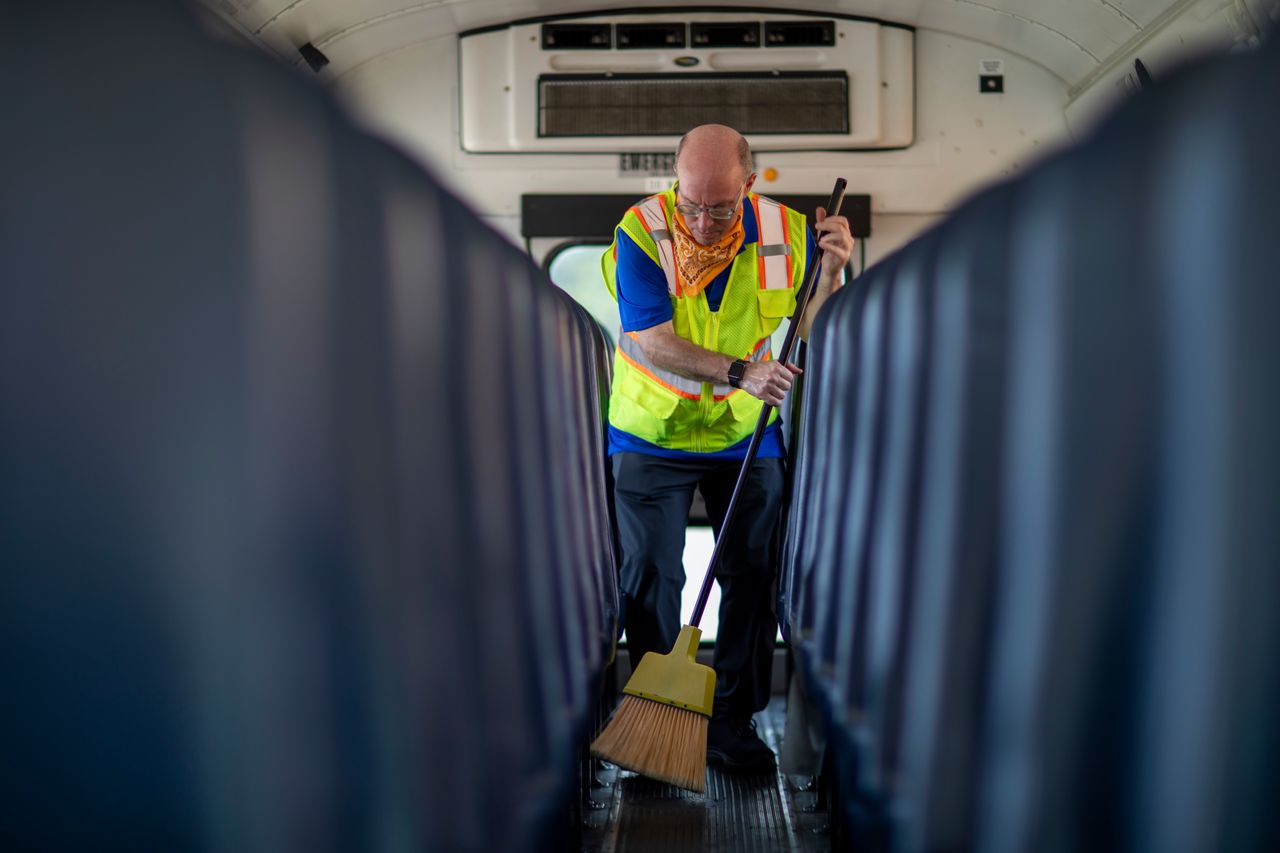
David Bryan, 55, earns about $35,000 a year as a school-bus driver and lives on Tybee Island, Ga. He doesn’t own property and has about $100,000 in retirement savings from his previous jobs as a railroad conductor and a researcher at a college foundation.
It’s a different life than that of his parents, who worked for decades for the sheriff’s department and the post office and received steady pension checks when they retired.
“As long as my body will let me, it’s better I keep working,” said Bryan.
The roughly 65 million Americans in Gen X are sometimes referred to as the “forgotten generation,” sandwiched between the larger and louder baby boomer and millennial generations. They are also called the “latchkey generation,” often coming home from school as children to an empty house. Goldman Sachs Asset Management in a recent report called Gen X the “‘401(k) experiment’ generation.”
For decades, employers often supported loyal workers in old age through traditional pensions with set payouts for life. The advent of the 401(k) system pushed the responsibility on to the individual—and Gen X was caught squarely in the transition.
“Gen X is the first generation where they were mostly expected to figure out their retirement on their own,” said Jeremy Horpedahl , an economics professor at the University of Central Arkansas and director of the Arkansas Center for Research in Economics.
The early champions of the 401(k) never thought that it would become the dominant way most Americans save for retirement. It is named for a line in the tax code changed in 1978 that gave executives a tax-free way to defer compensation from bonuses or stock options. Human-resources executives and economists jumped on the 401(k) as a way to encourage saving for rank-and-file employees.
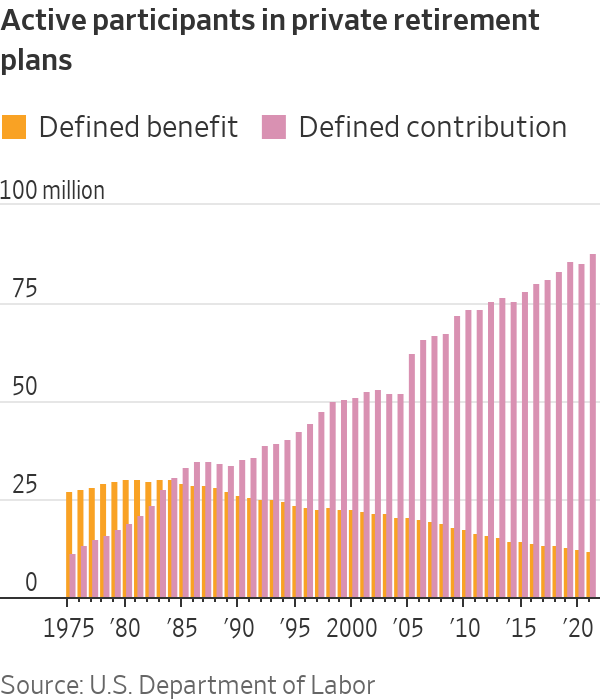
By the mid-1980s, the number of active participants in defined-contribution retirement plans—such as 401(k)s—overtook those in defined-benefit plans—such as traditional pension plans—in the private sector. Now, private pensions are rare.
When Gen Xers entered the workforce, the 401(k) was a new concept. Features such as automatically enrolling employees in a workplace plan and automatically increasing contributions every year didn’t become commonplace until later.
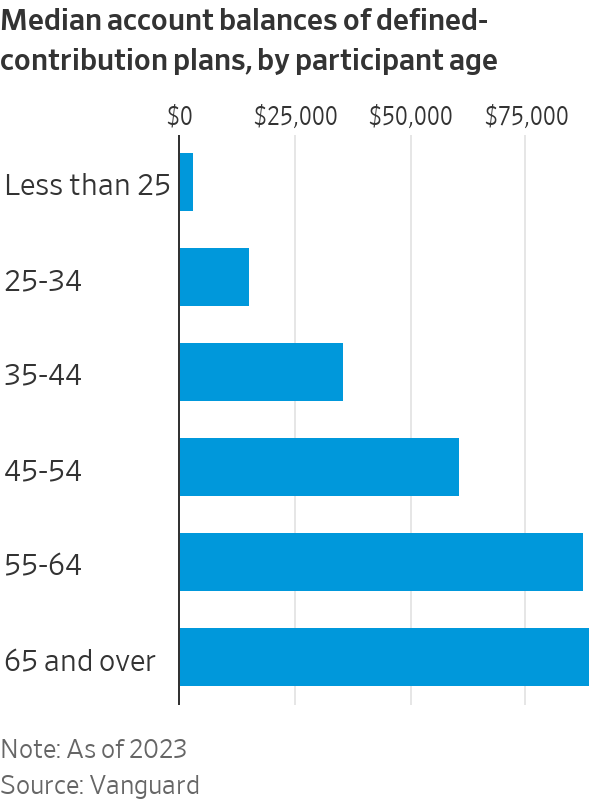
Other common private retirement savings tools were also introduced in the last half-century. The individual retirement account—a tax-deferred investment vehicle—was authorised in 1974, while the Roth IRA—funded with posttax money, but tax-free when withdrawn—was established in 1997.
Gen Xers between 45 and 54 years old had a median account balance of roughly $60,000 in defined-contribution retirement plans at Vanguard Group in 2023, according to the firm. For most Americans, that is well below the target some financial experts recommend of having roughly six times one’s salary saved for retirement by age 50.
John Kotrides, a 54-year-old living near Charlotte, N.C., had contributed to 401(k)s ever since he started his career in banking about three decades ago. But whenever he moved to a different employer, he usually cashed out his 401(k) because there was a more urgent expense, such as a home repair or moving costs.
Keeping the money invested in the stock market didn’t seem worth it after witnessing crashes like the bursting of the dot-com bubble. Retirement seemed far away.
“You no longer have a generation of people whose employer took you from your first job into your retirement,” he said. “When we were offered 401(k)s, I don’t think that was a great deal.”
Kotrides says he doesn’t have much in retirement assets, besides the home he owns, where he lives with his wife and two daughters, who are 12 and 20 years old. After quitting his job as a mortgage lender during the pandemic, he now works as a bartender part-time and earns most of his money making social-media content, mostly nostalgic videos about the 1970s through 1990s. He likes having more time to spend with his family.
“This is basically my retirement plan,” he said. “I truly assume that I’ll continue to work to provide for my family as long as I need to.”
Even those who have benefited from the 401(k) system say it hasn’t been easy.
Scott Zibel, a 56-year-old in Leominster, Mass., started putting money in a 401(k) when he began working at a grocery store at 15. His father encouraged him to contribute. The account grew as he continued working at the store through college and became a manager. In his early 30s, he became an English teacher and expects to receive a pension after retiring.
When the stock market crashed in 2020 at the onset of the Covid pandemic, he and his wife pulled the money in his wife’s 401(k) out of the market and into a money-market fund. Now they have reinvested the money, but put a greater portion of it into bonds than before.
“I’m grateful for the 401(k), but there’s no guarantees as well,” he said, estimating his household retirement savings at a little over $1 million.
Zibel feels prepared for retirement but says he has to live frugally to save. He has driven the same car for 12 years and has avoided pricey expenses such as new carpeting for his 30-year-old home.
“My wife and I have done so much planning for the future with our money, it’s made living in the now difficult,” he said.
For some Gen Xers, the 2008 financial crisis was a hit that took years to recover from.
Around 2007, Darling “Diva” Moore was at the peak of her career as a managing partner at a title company in West Palm Beach, Fla. Then the housing market collapsed and her company went under. She couldn’t make rent on her apartment and had to crash with her significant other at the time, sometimes turning to sleeping on the beach or in the car.
“The Great Recession changed everything for us,” said Moore, who is 57. “After that, I don’t know how many Gen Xers trusted that system.”
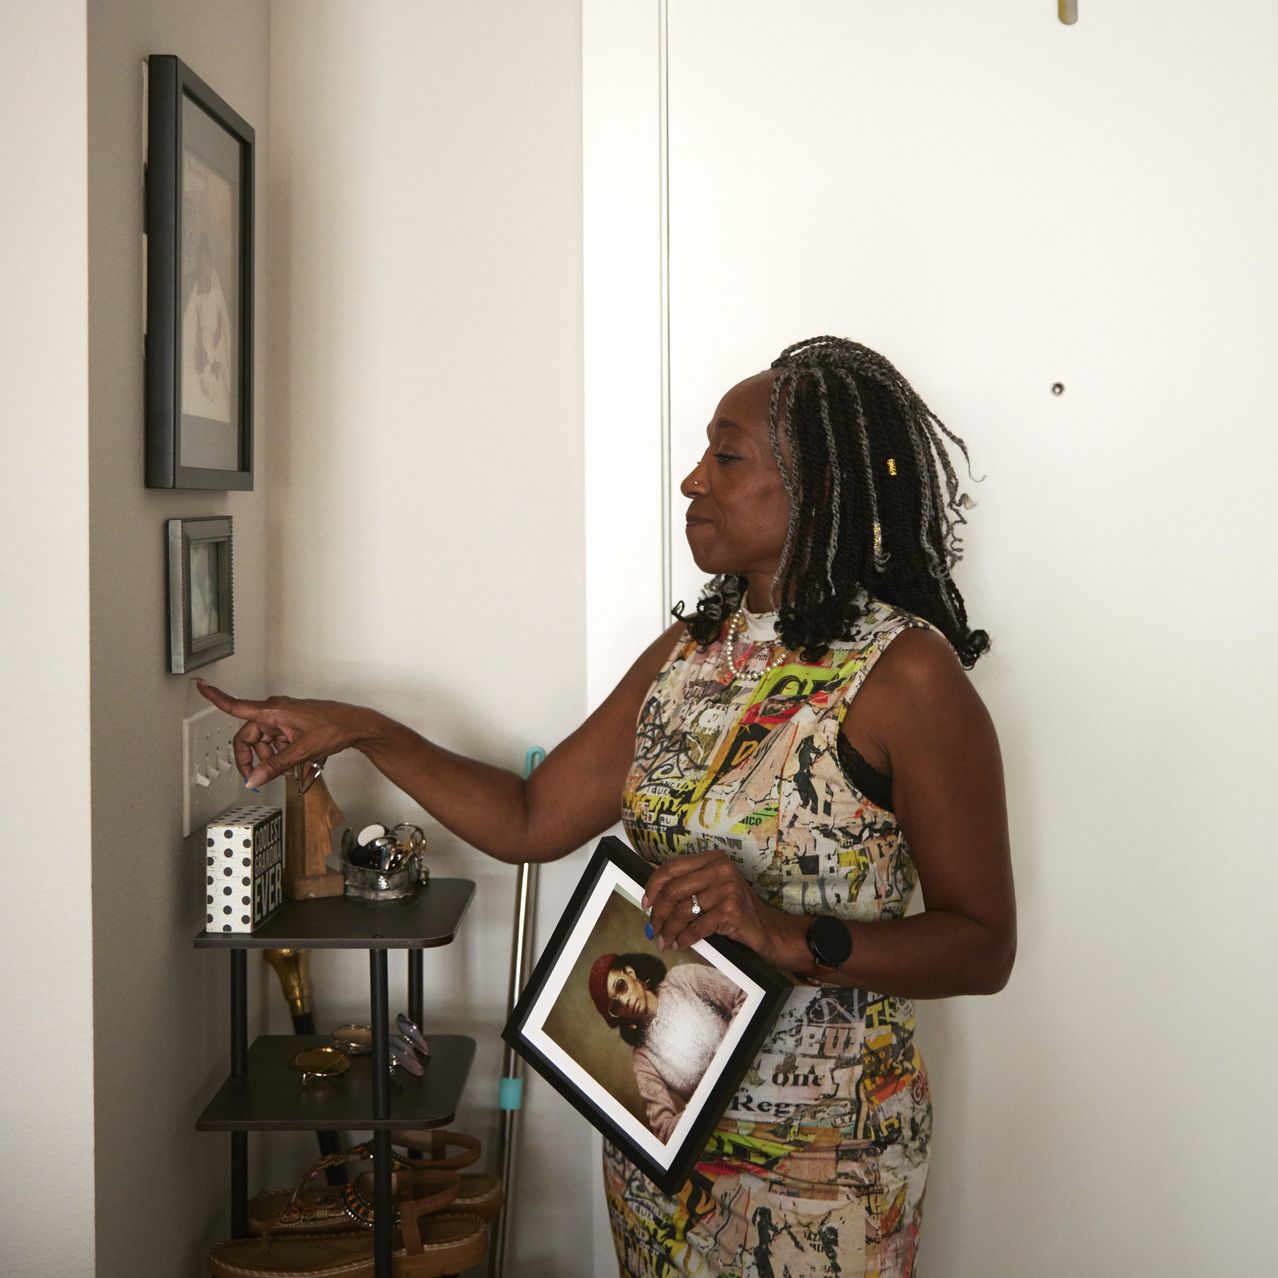
After settling in Denver, more than two years went by before she landed a new job. She went back to school, getting an online bachelor’s degree in business management and master’s degree in human relations and organisation development. Now she is self-employed as a career counsellor.
As she is approaching her 60s, Moore is trying to locate money she contributed to various 401(k)s from jobs earlier in her career. Whenever she switched jobs, she didn’t rollover her balance to an IRA or new 401(k), so those accounts are scattered across plan providers. “In the ‘90s, they didn’t make it easy to find out where that money is,” she said.
She is also contending with student debt from a for-profit associates-degree program she completed in her 20s that has swelled to nearly $90,000 from around $27,000 due to interest.
More than a quarter of U.S. households led by Gen Xers between the ages of 45 and 54 had education loans in 2022, compared with about 15% of baby boomers at the same age in 2007, according to Fed data.
Soaring tuition costs, sky-high rents and other inflationary pressures for Gen Z are also Gen X’s problem. Many Gen Xers have forked over tens of thousands of dollars for their children to attend college. Young people are also increasingly living with parents, or relying on them for financial support, well into adulthood .
Pamela Likos’s 21-year-old son lives at home with her in the suburbs of Madison, Wis., while another son and daughter are at college.
“My kids are still definitely not grown and flown,” Likos said.
Some Gen Xers are simultaneously caring for aging parents, who are living longer than previous generations.
Likos isn’t in that situation yet, but her stepmother, who has Alzheimer’s, and her father are in their 80s.
“I need my parents to hang on healthwise for another five to 10 years because we are not ready to help financially, really,” she said.
Likos, who is 54, was the first person in her family to go to college, but didn’t work for about two decades after she got married and became a stay-at-home mom. When she got divorced about seven years ago, she found herself with no savings of her own and no resume to apply for jobs. She got a license to work as an esthetician for a few years and now is remarried. From her divorce, Likos received about half of her ex-husband’s 401(k), which comprises most of her plan for retirement.
The youngest members of Gen X are in their mid-40s, offering more time to boost savings ahead of retirement. Tyler Bond, the research director at the National Institute on Retirement Security, wonders if there will be diverging retirement experiences between the older and younger ends of the cohort.
“The older Gen Xers simply may not have time,” he said.
Avery Nesbitt, a 44-year-old operations manager in the Atlanta area, isn’t waiting for retirement to go on nice vacations or buy a new car because he wants to enjoy them now—and he doesn’t expect to be able to save up a cushy nest egg for later in life. If the Covid pandemic taught him anything, it was that anything can happen.
He and his wife have contributed modestly to employer-sponsored retirement accounts but didn’t feel like they could afford to save more. They own a home, where they live with their two children. That makes up the bulk of their wealth. He said he has put more money into life-insurance policies than in retirement accounts.
“I fully expect to work until I die,” Nesbitt said. “It is what it is.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
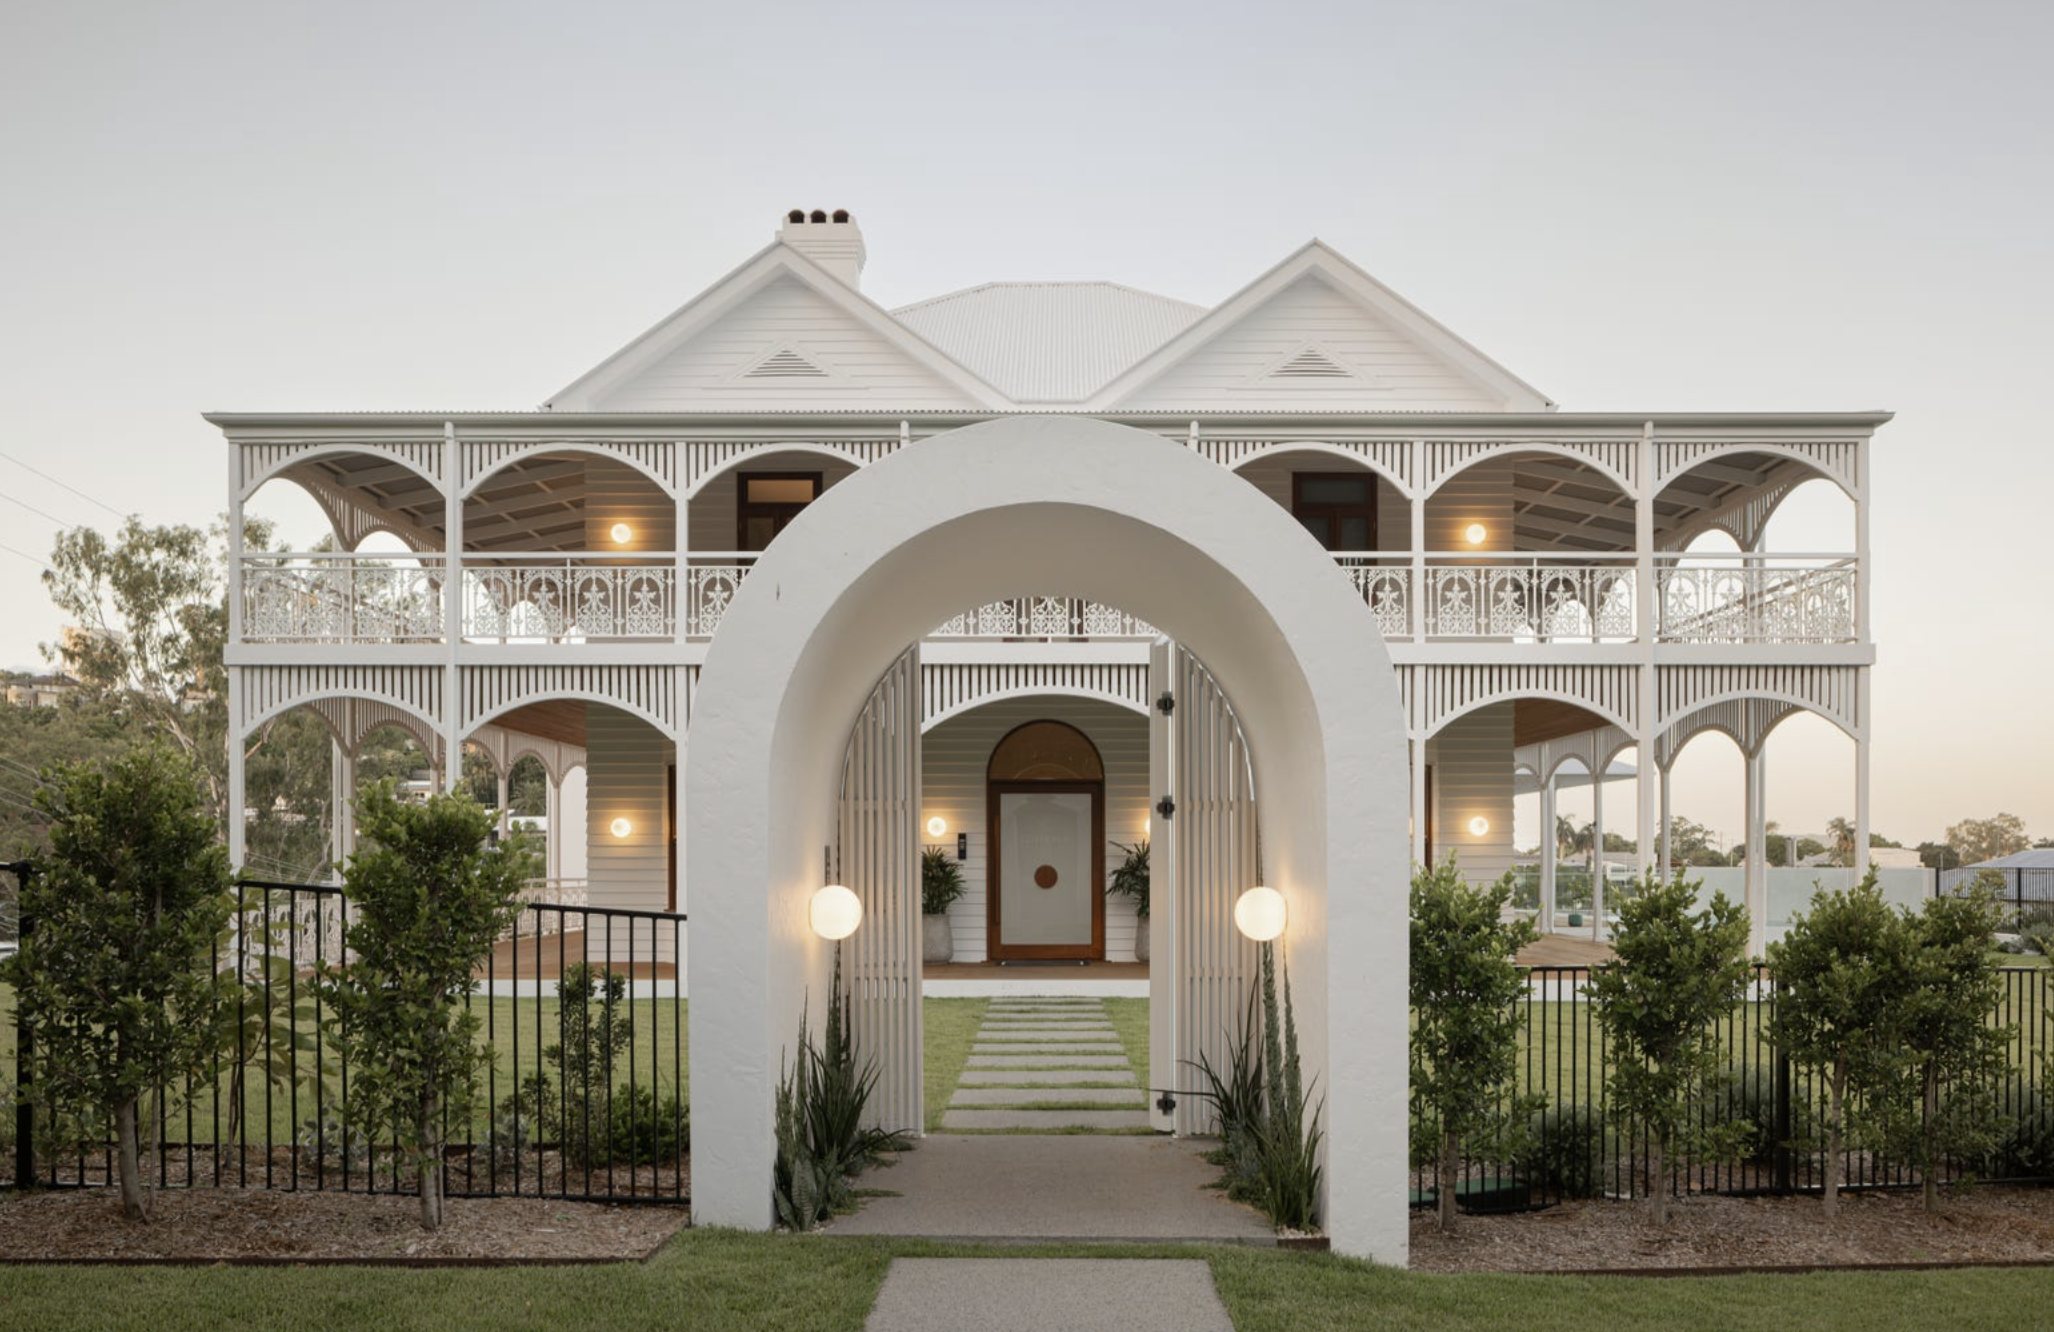
A restored 1860s Brisbane residence transformed by GRAYA has smashed Paddington’s house price record, selling for more than $12 million.
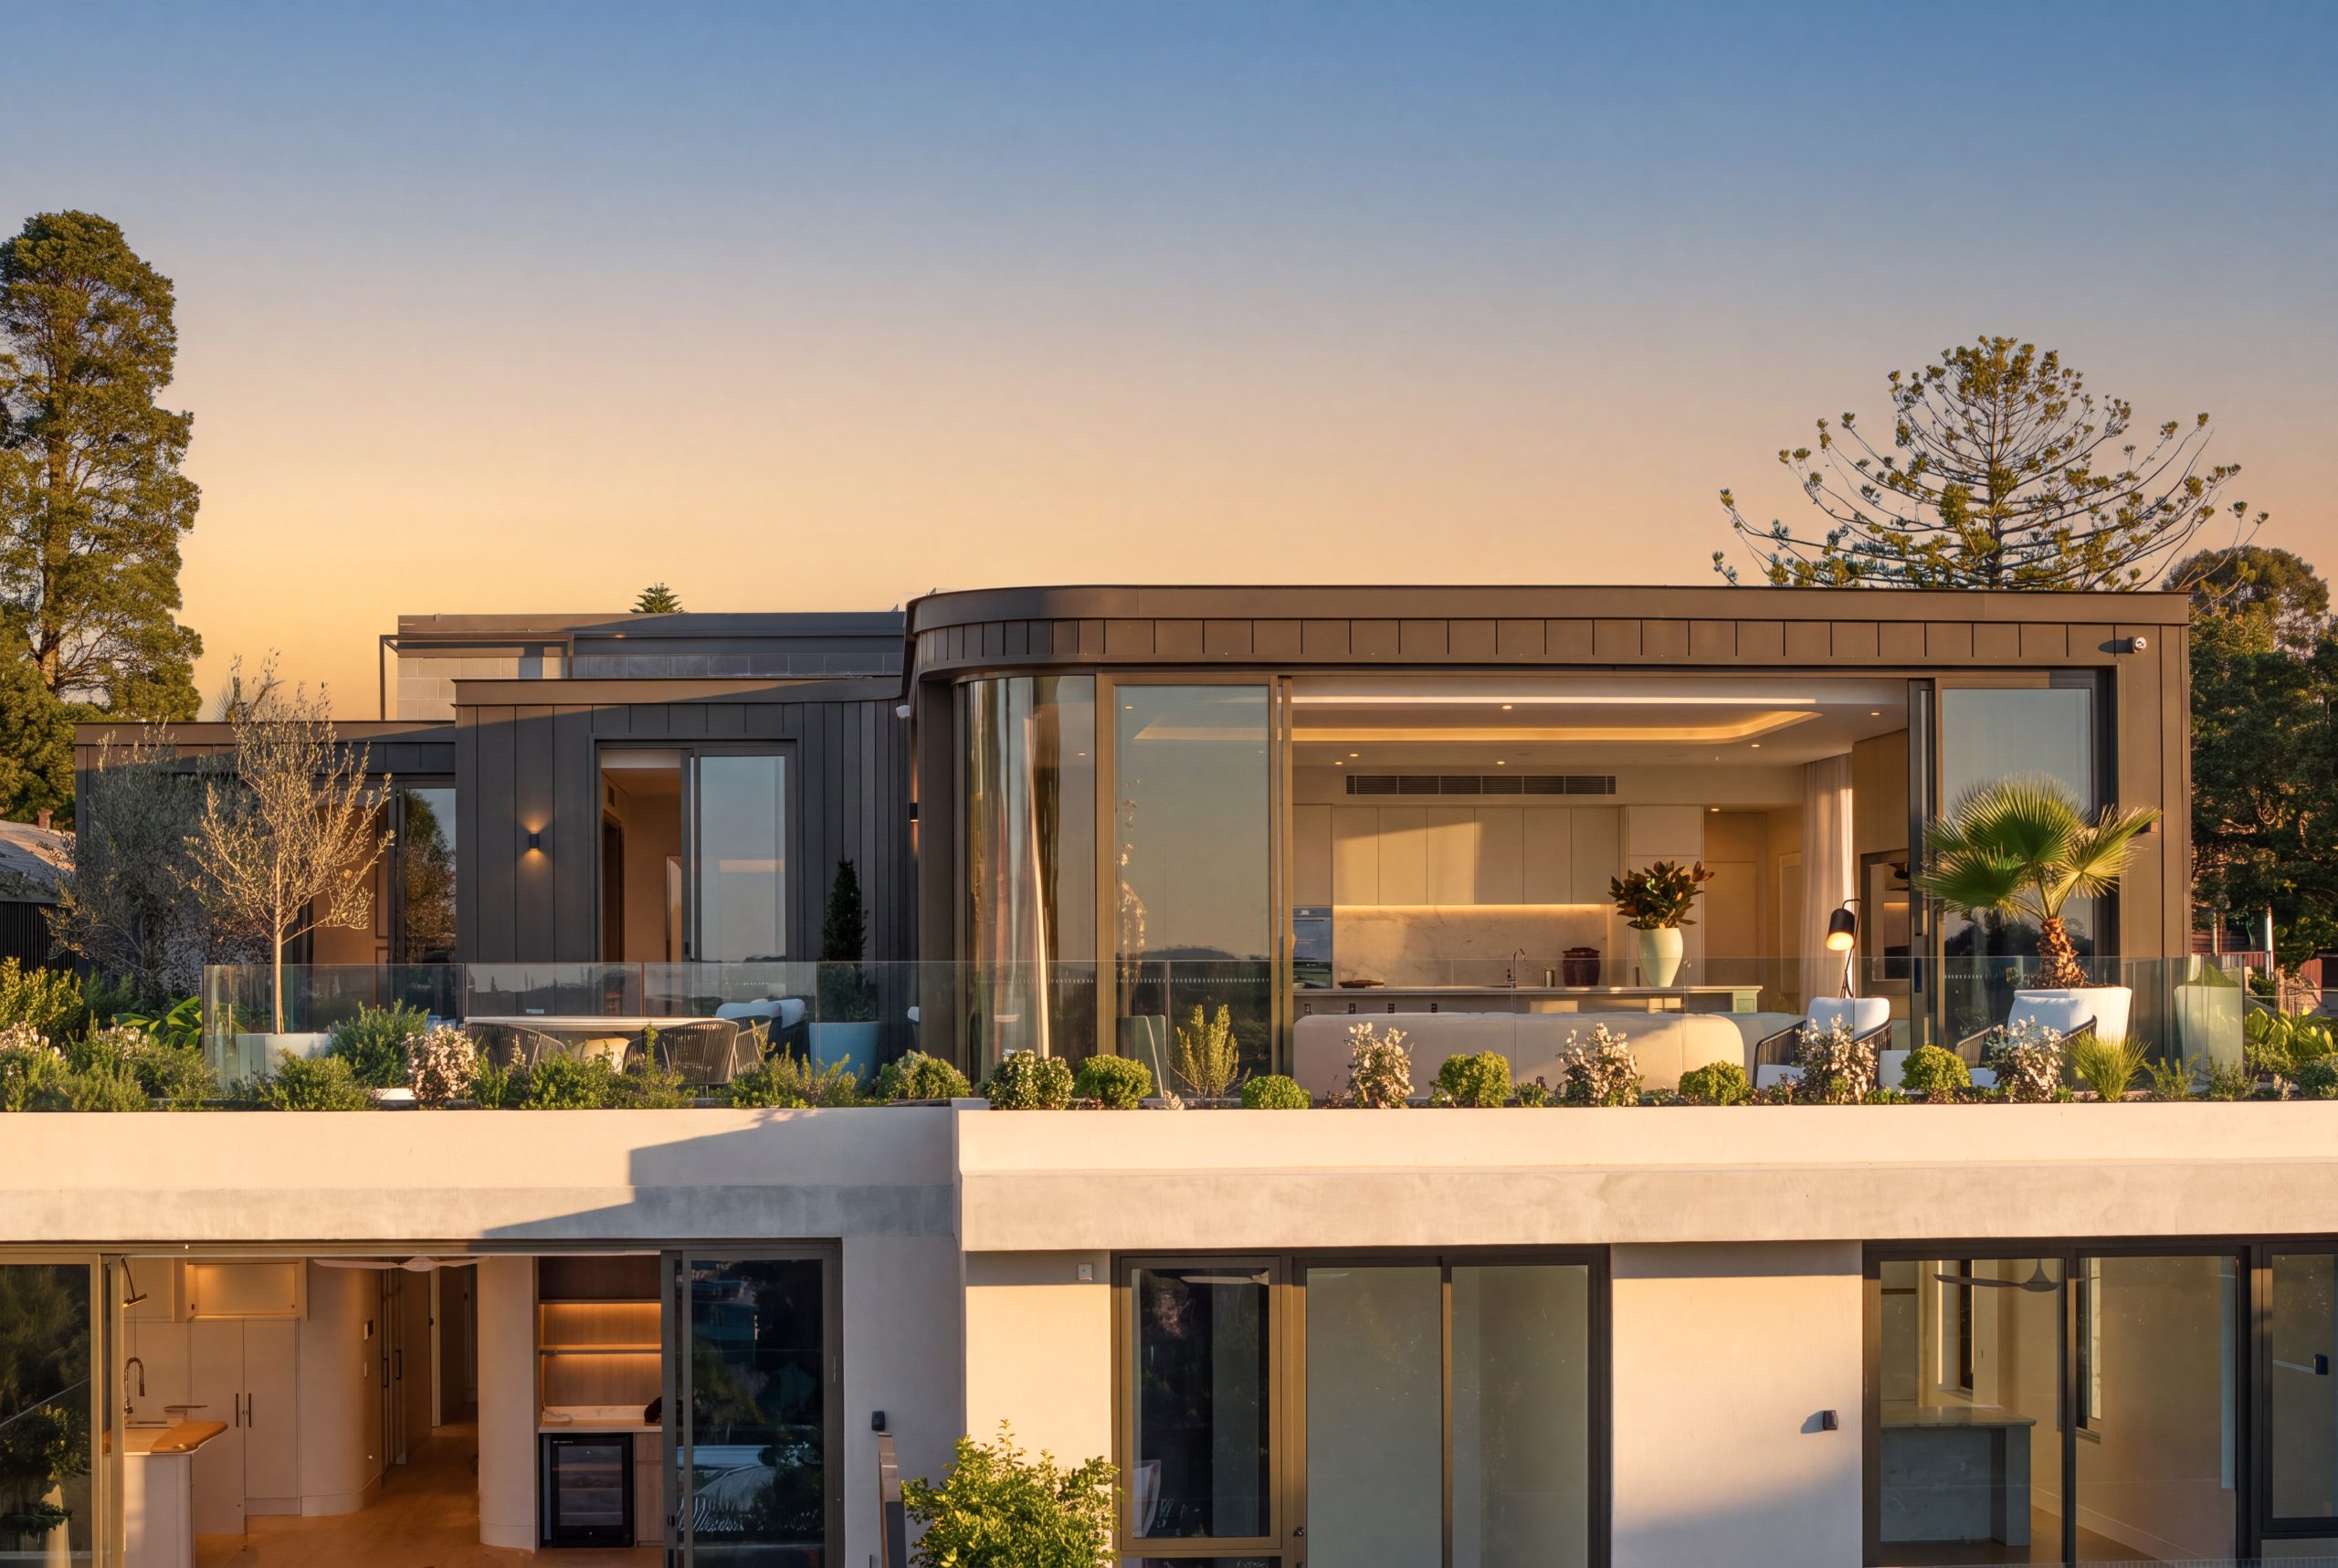
The completed penthouse at Park Residences showcases a considered approach to luxury apartment living, combining northern light, curated interiors and the privacy of a whole-floor residence.