Bosses Are Finding Ways to Pay Workers Less
After a tumble in pay for white-collar job openings, wages for new hires in many blue-collar sectors are now falling

 5 min
Bosses are quietly trying to reset worker pay levels, saying the era of overpaying for talent is over.
Pay for many white-collar recruits shrank last year , and now wages for new hires in construction, manufacturing, food and other blue-collar sectors appear to be ebbing too, according to an analysis of millions of jobs posted on ZipRecruiter.com .
Job seekers report seeing roles that once offered salaries between $175,000 and $200,000 a year ago now being advertised for tens of thousands of dollars less, a change that has had them rethinking their pay expectations. Companies are also moving job openings to lower-cost cities or offering them as lower-paying contractor roles, recruiters and corporate advisers say.
The push to reset employee salaries reflects a power shift in the cooling hiring market. Employers have more choice of who they can hire, and at what pay level, and are questioning whether they really need star hires when a workhorse will do . Even hourly jobs that were until recently the toughest for employers to fill are being advertised at lower pay than a year ago, as are some professional roles, according to business leaders and recruiters. undefined undefined “A lot of companies are thinking they can get away with paying a cheaper salary because they know us job seekers are desperate,” said Eric Joondeph, 31 years old, who has been looking for a senior customer-experience role for nine months. He has lowered his pay expectations by at least $20,000 a year since he started looking.
Among listings for more than 20,000 different job titles on ZipRecruiter.com this year, sectors including retail, agriculture, transportation and warehousing, manufacturing, and food all registered drops in average posted pay. The biggest was retail, where average wages advertised for new hires is down 55.9%; agriculture is down 24.5% and manufacturing, down 17.3%.
Tom Locke, a McDonald’s franchisee who owns 56 restaurants in Ohio, Pennsylvania and West Virginia, starts hourly workers at $13 an hour, but the signing bonuses and other hiring incentives he offered during the pandemic are gone. He said he is constantly asking his managers if they can reduce hourly wages to $12 an hour.
Labor expenses at Locke’s McDonald’s locations now exceed his food costs—something he said hasn’t happened in his 24 years with the company.
“I want everybody to do well in America, but there’s cost pressures,” he said. “It’s just a constant battle.”
‘Geographic arbitrage is real’
Pay resets continue to ripple through the white-collar world too. Joondeph has been looking for a senior role in customer experience since he was laid off from a customer-experience associate role.
“I’ve seen salaries slowly dropping little by little for roles I’ve been targeting,” he said.
Based in Boise, Idaho, Joondeph said he is struck by the number of jobs he has applied for that now advertise salaries not much higher than $60,000. Many used to advertise with a range between $80,000 and $100,000 in the past six to nine months, he added.
In some cases, companies are looking to attract less experienced, but still coachable, people who can be paid less than industry veterans, corporate advisers say.
Brooke Weddle, a senior partner at McKinsey & Co., said one client recently decided to stop recruiting stars, putting in place a “no more unicorns” hiring strategy, in part, to lower costs. (Unicorns are top performers with specialised skills who can command outsize salaries.)
Other businesses are considering moving jobs overseas, said Weddle, a leader in McKinsey’s group that advises on personnel issues. Instead of hiring data analysts in the U.S., for example, companies want to add people in Mexico and cheaper parts of Europe, like Poland, to save on labor costs.
“Geographic arbitrage is real,” she said.
In the U.S., some Fortune 1000 companies are moving enterprise software jobs from expensive cities such as Chicago and San Francisco to places with a lower cost of living, such as Cincinnati and St. Louis, Mo., said Keith Sims, president of Integrity Resource Management, a recruiting firm based in the Indianapolis area.
Sims, who for 25 years has helped companies recruit professionals who work with software systems like SAP and Oracle , said he hasn’t seen bosses so intent on reining in pay since the recession of 2009.
Salaries for tech jobs working with back-office and core operations business software that paid between $110,000 and $130,000 a year ago now go to less experienced hires for $85,000 to $100,000, he said. Some companies are laying off entire service areas, renaming the division and populating it with new hires at much lower compensation levels.
Hiring managers gain leverage
Overall pay for new hires in white-collar sectors increased this year, after falling in 2023, buoyed by gains in certain corners of the professional world, including law, engineering and healthcare, according to Julia Pollak , ZipRecruiter’s chief economist.
Although some tech roles that require artificial intelligence skills still offer hefty pay, many other tech jobs are advertised at lower salaries than two years ago, according to some Silicon Valley recruiters.
“Most people we interview are seeing lower salaries,” said Jill Hernstat, chief executive of Hernstat & Co., a tech recruiting firm based in the San Francisco Bay Area. “Hiring managers know they are more in control now.”
Other white-collar professions with declining new-hire salaries include finance, down 9.2% in the past year, other professional services, down 2.4% and insurance, down 1.6%, according to Gusto, a payroll and benefits software company with more than 300,000 small and midsize businesses as customers.
Pay adjustments are easing some tensions among colleagues who may have resented how much new hires were making, and the fact that tenured employees’ pay hadn’t kept up, said Tom McMullen , a senior client partner at Korn Ferry , a global organizational consulting firm.
“A lot of leaders wanted this market to cool down because they got themselves into some internal equity messes by paying through the nose for all this hot talent,” he said. “What we’re hearing is, ‘Hey, I don’t have to offer the exorbitant in-hire rates that I was offering.’”
Same work, less pay
Kate Ball was at Amazon .com for eight years, some of them as a senior recruiter, before being laid off in 2023. External recruiters have since repeatedly called her about a contract role there as a senior recruiter. Ball said the job is virtually the same as the one she had once held, but for up to 65% less pay.
Some of her former co-workers who were also laid off have taken lower-paid contract positions with Amazon: “I don’t know anyone that came back on the same package,” said Ball, 44, who has started her own HR advisory practice, Sparkle & Sass Consulting.
As Ball has applied for roles elsewhere, she has noticed some openings get reposted with lower pay ranges than were advertised weeks or months before. She applied for one job, as an employee-experience manager, went through two interview rounds, then heard nothing. A few weeks later, she saw the same job re-advertised, this time at roughly a third less than the six-figure salary she’d been quoted by the recruiter.
It is understandable, Ball said, that companies are reining in pay when they have a greater pick of job candidates than they did a couple of years ago. Still, some tactics could create ill will for employers when they have to compete more intensely for talent again.
“People will take a job now because it pays them and they’re scared, but that’s not going to last forever,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From farm-to-table Thai to fairy-lit mango trees and Coral Sea vistas, Port Douglas has award-winning dining and plenty of tropical charm on the side.
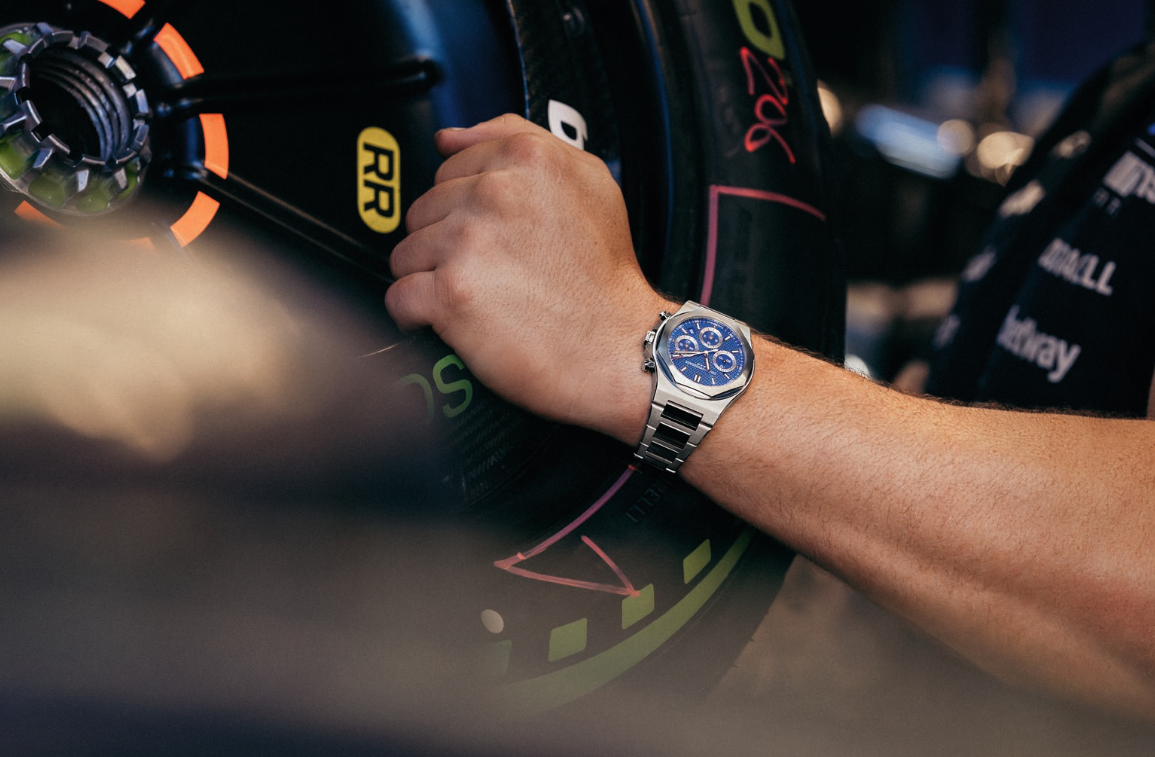
The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.