





Buffett and Munger on Success, Toxicity and Elon Musk
The Berkshire Hathaway CEO, with business partner Charlie Munger, spent hours this weekend discussing life and career choices

 3 min
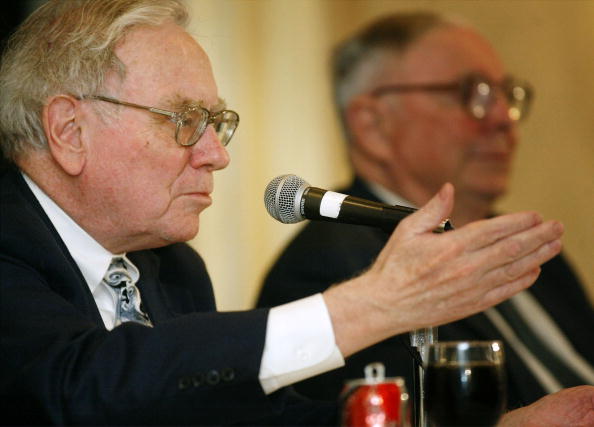
The question was a philosophical one: How should you avoid major mistakes in business and life?
Warren Buffett, the 92-year-old chairman and chief executive of Berkshire Hathaway, paused briefly.
“You should write your obituary and then try to figure out how to live up to it,” Mr. Buffett said. “It’s not that complicated.”
At Berkshire’s annual shareholder meeting on Saturday, an event that draws thousands to Omaha, Neb., each spring, Mr. Buffett and his longtime business partner, Charlie Munger, spent hours weighing in on topics as varied as the recent banking turmoil to artificial intelligence and the future of the U.S. As is typical at such gatherings, the executives also doled out plenty of advice on management practices, career choices and how to enjoy a good life.
In prior years, Mr. Munger has heaped scorn on consultants, compensation specialists and what he described as make-work activities inside U.S. companies. This weekend, he directed his ire at wealth managers.
“Having a huge proportion of the young and brilliant people all going into wealth management is a crazy development in terms of its natural consequences for American civilisation,” Mr. Munger said. “We don’t need as many wealth managers as we have.”
He added: “I don’t think a bunch of bankers, all of whom are trying to get rich, leads to good things.”
Mr. Buffett, for his part, said he wanted to see greater accountability inside banks, saying that the recent crisis in the industry illustrated why executives and board members should face consequences if a business encounters problems.
“If the CEO gets the bank in trouble, both the CEO and the directors should suffer,” Mr. Buffett said. “You’ve got to have the penalties hit the people that cause the problems, and if they took risks that they shouldn’t have, it needs to fall on them if you’re going to change how people are going to behave in the future.”
Over hours of questions from investors and others, the two billionaires often peppered their answers with recommendations on how to navigate business. Mr. Buffett advised that people pay attention to how others might try to manipulate them.
He also encouraged those in attendance to resist the temptation to criticise or vilify others.
“I’ve never known anybody that was basically kind that died without friends,” Mr. Buffett said. “And I’ve known plenty of people with money that have died without friends.”
Mr. Munger said that success comes from steering clear of toxic people.
“The great lesson of life is get them the hell out of your life—and do it fast,” Mr. Munger said.
When hiring some of his top leaders over the years, Mr. Buffett said he has tried to suss out someone’s talents and not focus on whether they attended a prestigious institution.
“I have never looked at where anybody went to school in terms of hiring,” Mr. Buffett said. “If somebody mails me a résumé or something, I don’t care where they went to school.”
One of Mr. Buffett’s top lieutenants, Ajit Jain, studied at Harvard Business School, “but he isn’t Ajit because he went to those schools,” Mr. Buffett said.
Mr. Buffett graduated from the University of Nebraska-Lincoln and later studied under the legendary value investor Benjamin Graham at Columbia University. Mr. Munger, who is 99 years old, studied mathematics at the University of Michigan and meteorology at the California Institute of Technology, and went on to earn a law degree from Harvard University.
On artificial intelligence, Mr. Buffett said he had been impressed at generative AI’s abilities to summarise legal opinions and potentially take on other tasks, though he said he also worried about its potential consequences. “It can do all kinds of things, and when something can do all kinds of things, I get a little bit worried because I know we won’t be able to uninvent it,” Mr. Buffett said.
Mr. Munger said he was skeptical of some of the hype around artificial intelligence. “I think old-fashioned intelligence works pretty well,” he said.
Near the end of the meeting, an audience member asked the two billionaires to weigh in on Elon Musk, the SpaceX and Tesla CEO who took control of the social-media platform Twitter last year.
Mr. Buffett called Mr. Musk a “brilliant, brilliant guy,” who had a much different approach in dreaming about the future than the Berkshire executives. Mr. Buffett has often said he takes a hands-off approach to managing Berkshire’s subsidiaries, which range from the insurer Geico to the restaurant chain Dairy Queen. Mr. Musk is known for weighing in on the details at his companies.
“He would not have achieved what he has in life if he hadn’t tried for unreasonably extreme objectives,” Mr. Munger said of Mr. Musk. “He likes taking on the impossible job and doing it. We’re different: Warren and I are looking for the easy job.”
Mr. Buffett said he didn’t want to compete against Mr. Musk, to which Mr. Munger added: “We don’t want that much failure.”
Mr. Musk tweeted Saturday that he appreciated the “kind words from Warren & Charlie.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


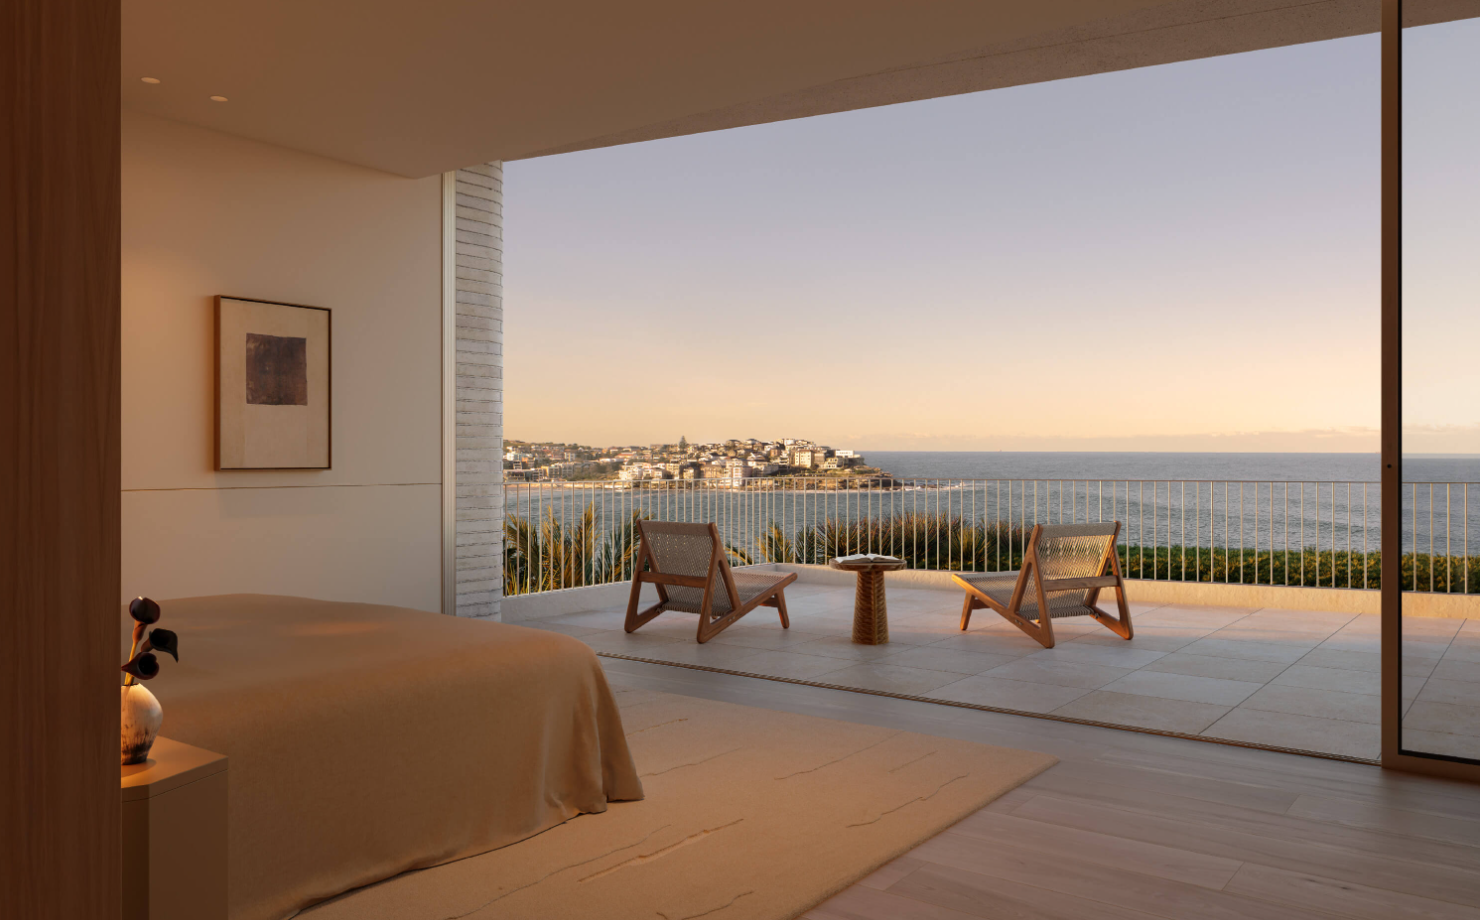
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
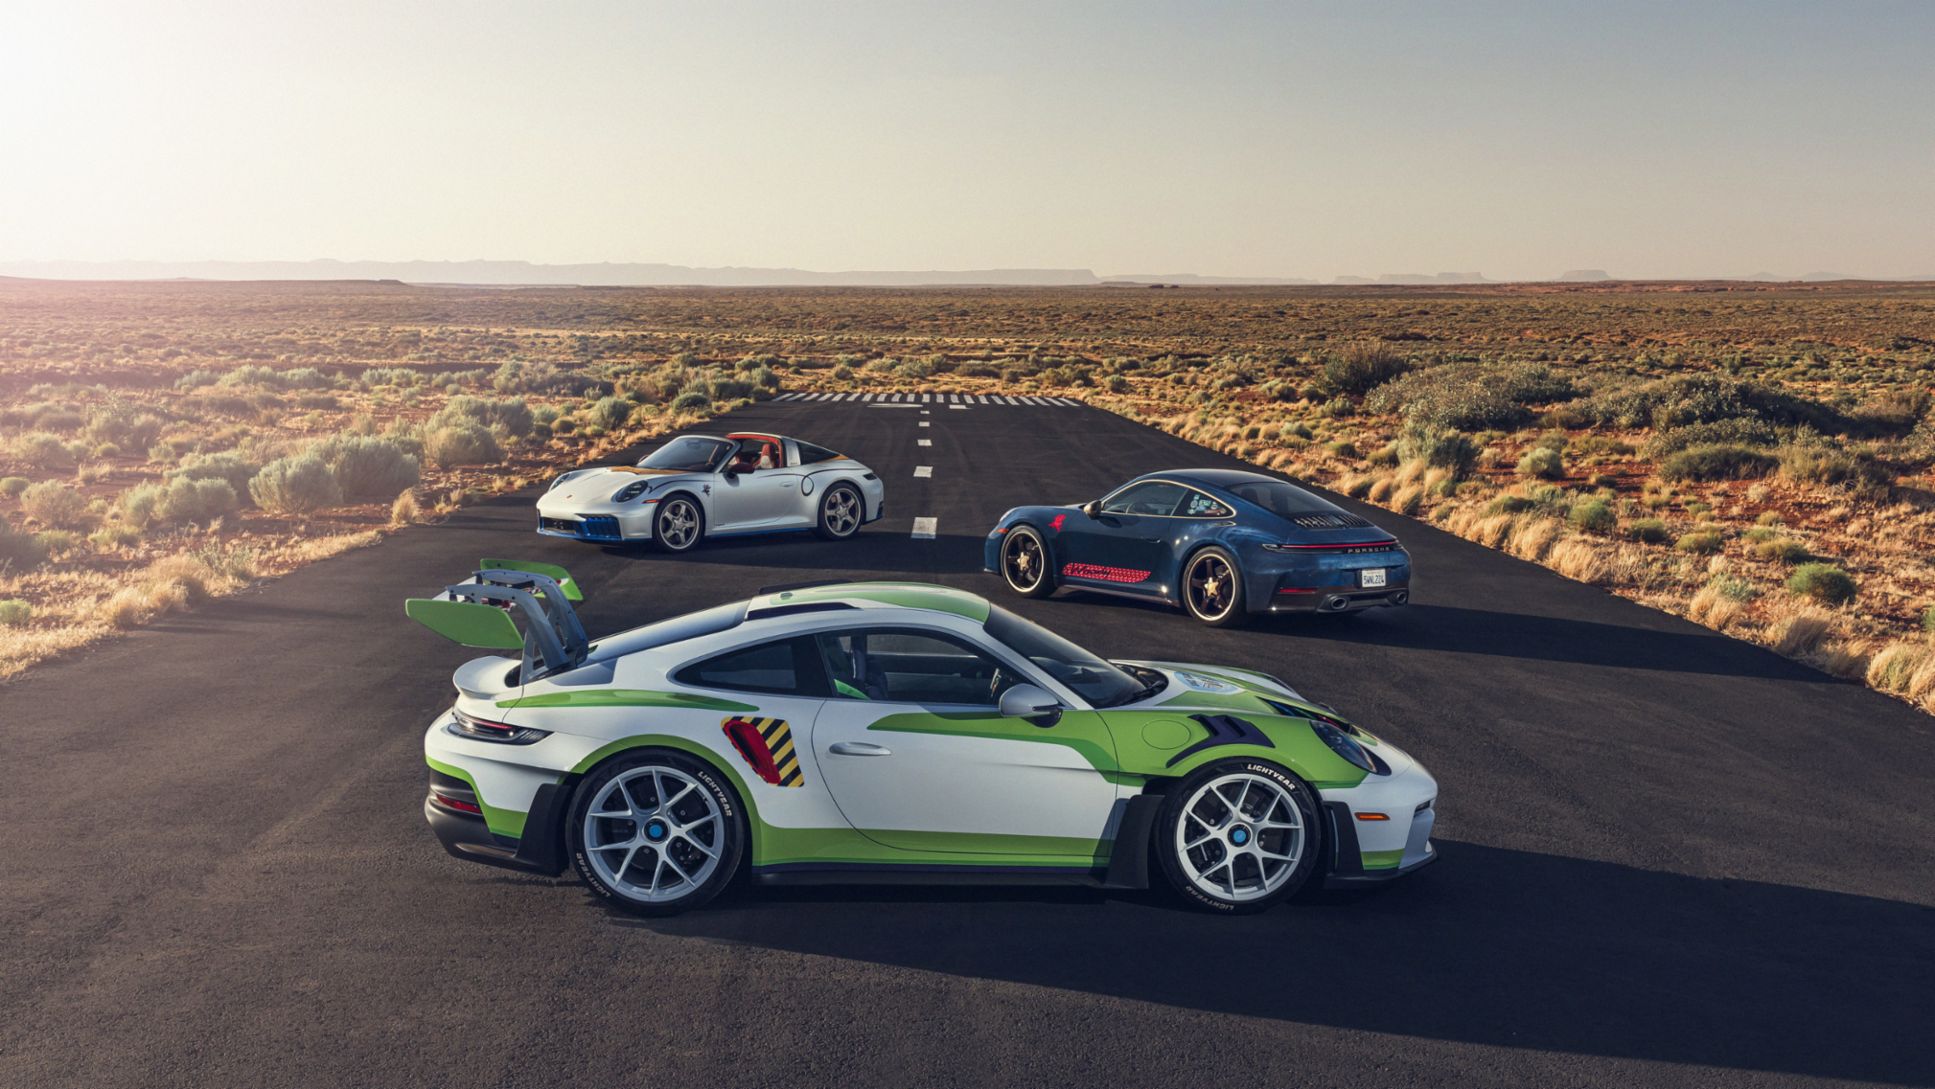
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.

From Italy’s $93,000-a-night villas to a $20,000 Bowral château, a new global ranking showcases the priciest Airbnbs available in 2026.

The pandemic-fuelled love affair with casual footwear is fading, with Bank of America warning the downturn shows no sign of easing.


