Where CEOs Find Time for Triathlon Training and Motorcycle Racing
Leaders with epic hobbies seem to squeeze more hours out of the day than the rest of us

 4 min
Many of us can barely keep up with our jobs, never mind hobbies. Yet some top executives run marathons, wineries or music-recording studios on the side. How can they have bigger responsibilities and more fun than we do?
It can seem like ultrahigh achievers find extra hours in the day. They say they’ve just figured out how to manage their 24 better than the rest of us.
They also admit they take full advantage of the privileges of being a boss—the power to delegate and the means to do things like jetting to Denmark for a long weekend of windsurfing.
Dan Streetman trains as many as 20 hours a week for Ironman triathlons in addition to his job as CEO of cybersecurity firm Tanium. It’s a big commitment for anyone, never mind a corporate leader who travels to meet with customers every week. He pulls it off by sleeping fewer than seven hours a night and waking around 5 a.m., planning his exercise sessions months in advance, and switching his brain from work mode to sport mode almost as fast as he transitions from swimming to cycling during a competition.
“I tend to work right up until the day of the race,” says Streetman, 56 years old. “I remember being on a board call on a Friday night, and Saturday morning was an Ironman. That’s just part of it.”
Ahead of business trips, he maps running routes in unfamiliar cities and scouts nearby pools, often at YMCAs. He rides stationary bikes in hotel gyms and, if they’re subpar, makes a note to book somewhere else next time he’s in town.
Leaders who eat, breathe and sleep business can appear out of touch at a time when employees crave work-life balance and expect their bosses to model it. Today’s prototypical CEO has a full life outside of work, or at least the appearance of one.
Their tactics include waking up early, multitasking and scheduling fun as if it were any other appointment. When you’re a top executive, hobbies tend to disappear unless they’re on the calendar. One CEO told me he disguises “me time” as important meetings. Only his assistant knows which calendar blocks are fake.
Ben Betts calls himself a “spreadsheet guy,” which is a bit like saying Michelangelo was a paint guy. With Excel as his canvas, Betts creates cell-by-cell checklists for just about everything he does, from cooking Christmas dinner to building a coop for newly hatched ducklings.
Betts, 41, is CEO of Learning Pool, a professional-development software maker. The duck home is part of his ambitious effort to restore an 18th-century farmhouse in England. He’s been renovating for about five years and aims to finish this fall.
On a recent Saturday, Betts’s spreadsheet called for stripping overhead beams by 5 p.m. so he could refinish them. Otherwise, the task would have to wait until the following weekend, throwing off his whole timeline. His vision of the home as a cozy enclave—completed in time for the holidays—can only come true if he sticks to a precise plan.
“Sometimes I stand in the doorway, and my wife probably wonders what I’m staring at,” he says. “I’m picturing us on a corner sofa with our two kids and the dog, watching a film in front of the fireplace I installed.”
Back in the swing
John Sicard , president and CEO of supply-chain manager Kinaxis , got back into drumming many years after he let go of his dream to become a professional musician. He practices almost every day, but his sessions sometimes last only 20 minutes. He rehearses with bandmates two or three times a month. That’s enough to prepare Sicard, 61, to play Foo Fighters and Led Zeppelin covers at occasional charity gigs.
He also built a studio in his house, where he records up-and-coming artists. He finds time by sticking to this management philosophy: “The most successful CEOs do the least amount of work.”
For Sicard, that means letting his lieutenants take charge of—and responsibility for—their divisions. Many corporate leaders work harder than they need to because they micromanage or hire poorly and pick up the slack, he says.
Thomas Hansen , president of software maker Amplitude, is back to windsurfing, a sport he competed in as a teenager. He lives near the ocean in California but gets out on the water only about once a month, when the waves are just right. Hobbies don’t need to be daily activities to be fulfilling, he says, especially if they require training regimens.
To stay in shape for windsurfing, he rises at 4:30 a.m., seven days a week, for an hour of exercise. Hansen, 54, also guards his Saturdays and Sundays like the crown jewels of Denmark, his native country, limiting himself to two working weekends a year. Things that feel urgent can almost always wait till Monday, he contends.
‘Like a badass’
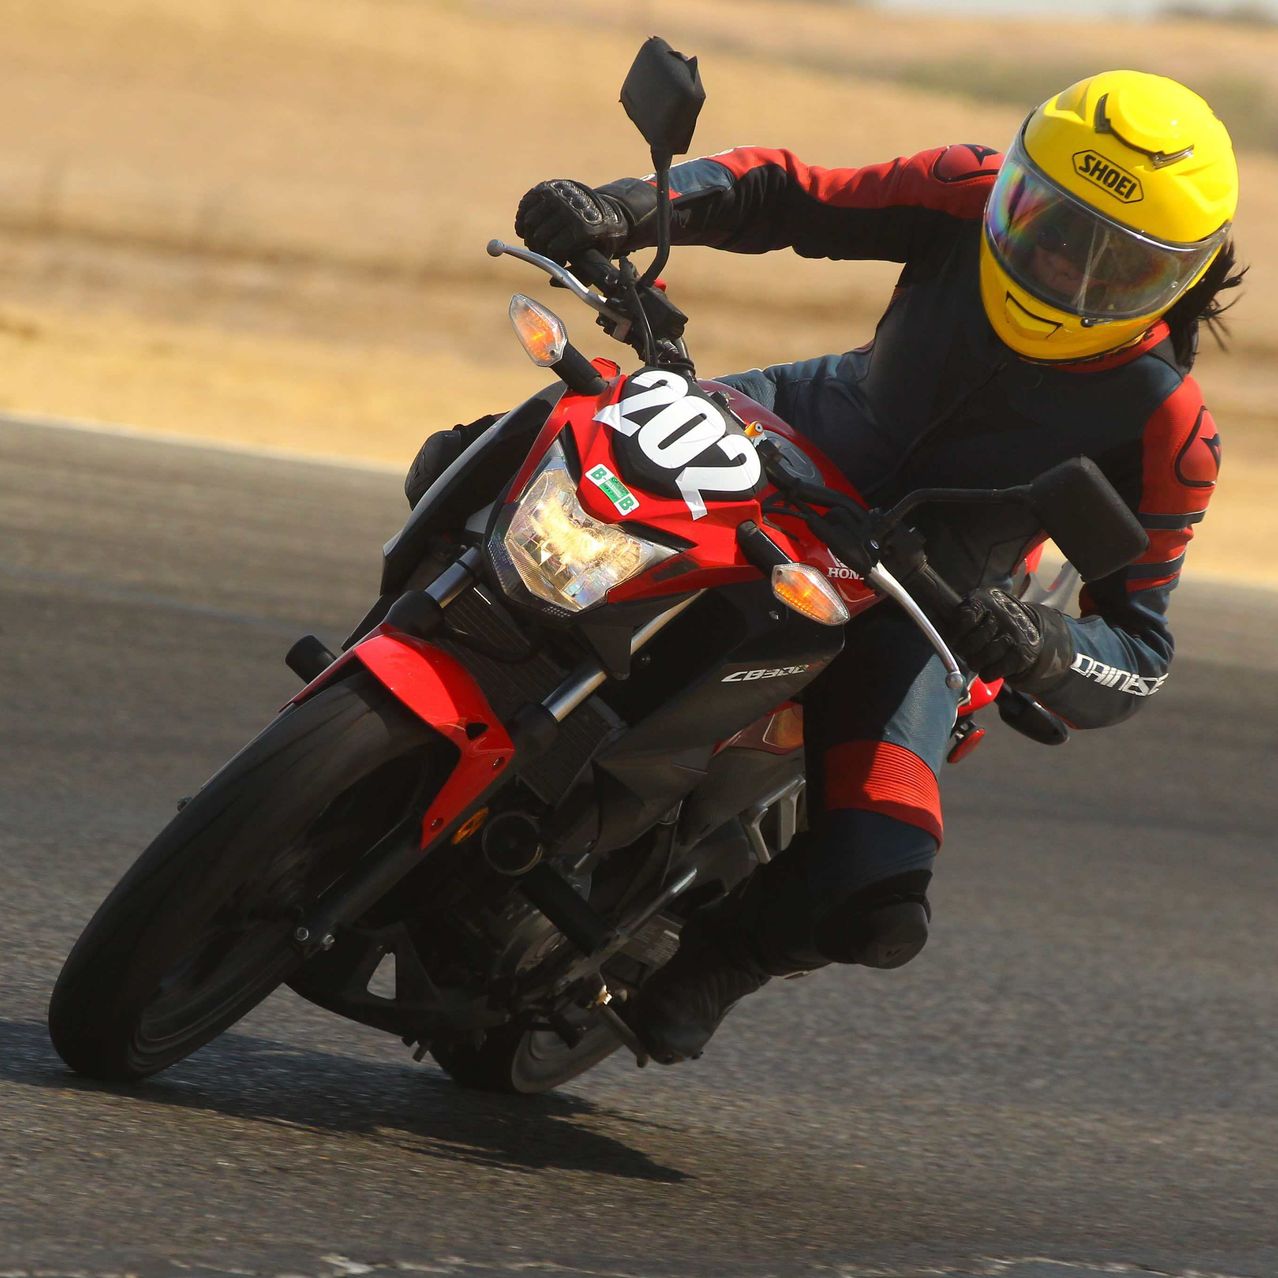
When Christine Yen isn’t calling the shots at work, she’s circling a racetrack at 80 mph on her Honda CB300F motorcycle. The co-founder and CEO of Honeycomb, which helps engineers diagnose problems in their software, took up racing a few years ago.
Prepandemic, her motorcycle was strictly for commuting in San Francisco—and making an impression. She loved pulling up to investor meetings in her hornet-yellow helmet and leather riding suit.
“It fits me like a glove, and it makes me feel like a badass,” says Yen, 36.
The keys to spending full days at the track are planning and being willing to work at odd hours, Yen discovered. Her favorite track publishes racing schedules in 10-week batches. As soon as a slate is released, she circles the dates when she expects her workload will be lightest, aiming to participate in roughly half of the events.
“I have also been known to bring my laptop to the motel and get some work done in the evenings,” she says. “It sounds boring to say hobbies can be scheduled, but that’s how I protect my time.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.
Rising rates, construction inflation and shrinking investor confidence are pushing Australia deeper into a dangerous housing spiral that monetary policy alone cannot fix.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.