Can Innovation Curb AI’s Hunger for Power?
Nvidia says its machine-learning chips have become 45,000 times more energy efficient, with further improvements in the pipeline

 6 min
Artificial intelligence is known for its seemingly insatiable appetite for energy. But some tech leaders and analysts are questioning the extent of AI’s footprint going forward, saying innovations in the sector could help offset rising energy demand.
There is certainly no shortage of forecasts detailing the ominous rise in AI’s energy consumption. One commonly-cited report by Climate Action against Disinformation, an association of environmental groups, suggests that AI could drive up global emissions by 80%.
Another estimate by researcher Alex de Vries—which he described as a worst-case scenario—suggests that Google’s AI alone could eventually rack up as much annual electricity demand as the country of Ireland.
Such predictions present a substantial challenge for the relationship between computing and the climate in the coming years.
However, others see reason for optimism. In a Salesforce survey of about 500 corporate sustainability professionals, published Wednesday, nearly half were concerned about AI’s potential negative impacts on sustainability efforts. Meanwhile, almost 60% thought the benefits of AI would offset its risks in addressing the climate crisis.
Microsoft founder Bill Gates recently weighed in on the subject, urging governments not to go “overboard” on concerns about AI’s energy footprint, and suggesting that the technology could actually drive a reduction in global energy demands.
Putting the AI boom in context
The rise of AI should be considered in a broader perspective, according to Charles Boakye, U.S. sustainability analyst at Jefferies. He noted that relative to other industries, the technology still makes up only a fraction of global power demands.
“Data centers—the engines powering everything from AI to traditional computing to cryptocurrency—currently account for about 2% of global electricity consumption. Of this, AI accounts for roughly 0.5%,” Boakye said.
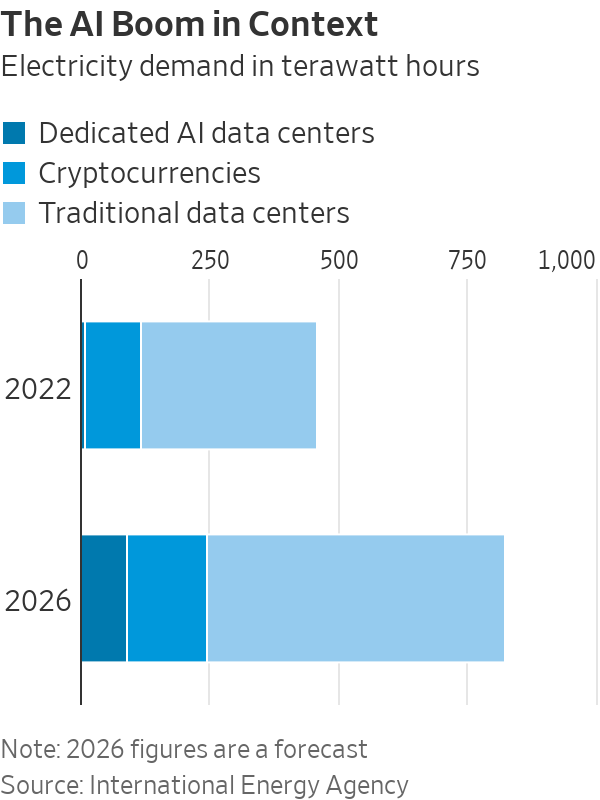
In terms of emissions, statistics last year from the International Energy Agency showed in total, data centers and transmission networks are responsible for 1% of energy-related greenhouse gases. For comparison, the oil-and-gas industry contributed just under 15% of emissions in 2022.
Looking ahead, the intergovernmental organisation said that by 2026, demand for AI is expected to increase ten fold compared with 2023. Even so, IEA data showed that it will still only account for roughly an eighth of total data-center electricity consumption.
“So in terms of AI demand, we’re talking about a small piece of a small piece,” Boakye said, noting that other areas of electrification, such as electric mobility, traditional data center growth and the industrial transition, will ask much greater questions of the power sector.
Charting efficiency trends
Demand is difficult to predict. But recent trends show that in practice, a rise in demand for computing power rarely correlates one for one with a rise in energy consumption, according to climate researcher Jonathan Koomey.
“Between 2010 and 2018, global data centres saw a 550% increase in compute instances and a 2,500% increase in storage capacity. This compares with just a 6% rise in electricity use,” he said.
Koomey, previously a visiting professor at Stanford, Yale and Berkeley, is best known for his work studying long-term trends in the energy-efficiency—now known as Koomey’s Law—highlighting the propensity of computing technologies to become more efficient over time.
AI may be a different animal, with some estimates suggesting large models such as ChatGPT use 10 times more energy than a Google search. But this is unsurprising for a relatively new technology, Koomey noted. In most areas of computing, energy demand tends to spike before levelling off as efficiencies gather pace, he said, noting that forecasts based on this inflection point will often be misguided.
Koomey cited a brief moment in the mid 1990s when internet data flows doubled every hundred days—a statistic that led to overinvestment in networks in the following years and 97% of fibre capacity sitting unused.
Similar efficiency trends can be seen in the development of AI, Jefferies analyst Boakye said. Google’s new TPU processors, for example, are more than 67% more efficient than in 2022, and the energy used to train OpenAI’s ChatGPT models has gone down by 350 times since 2016, he noted.
“It’s in their best interest, and in the interest of their business models, to increase that efficiency,” the analyst said.
Going for gold in the AI Olympics
If any company will have a say in the future of AI, it’s Nvidia . The U.S. technology company designs roughly 80% of the world’s specialized AI chips. Its next-generation GPUs, known as Blackwell, are touted to be 25 times more energy efficient than current iteration Hopper, while offering 30 times more computing power. Blackwell chips are slated for release later this year.
So far, the progress appears consistent, with Hopper 25 to 30 times more efficient than Nvidia’s previous generation of chips. Overall, the company said it has experienced a 45,000 times improvement in GPU energy efficiency over the last eight years.
Nvidia added that software optimisation also plays a big role in increasing the energy efficiency of its products.
“Once a platform has been launched, we will make it more efficient in a single year,” the company said. In the year following its launch in 2022, Hopper became two times more efficient after taking part in MLPerf, otherwise known as the Olympics of AI, in which tech companies compete and collaborate to drive improvements in the speed and efficiency of their models.
Part of this optimization involves taking large, energy-intensive AI models—such as ChatGPT—and refining them to perform more specific tasks. On July 18, for example, OpenAI launched a smaller, smarter and more energy efficient version of its previous GPT model, known as GPT-4o mini. Koomey sees these more “lightweight” models driving demand in the future .
“I’m not convinced large-scale AI has a good business model at this point, despite them driving all the investment. The slam dunk machine learning usually involves smaller, more efficient models, focused on a specific task. For me, this is where most of the business value lies,” he said.
Training and education will be essential for getting a more targeted and efficient experience with AI, helping to narrow the gap between businesses and their sustainability goals, said Suzanne DiBianca, Salesforce’s chief impact officer.
According to Nvidia, another way of alleviating AI’s impact is directing workloads—particularly the more energy-intensive jobs of training AI models—to regions with more abundant resources, ideally renewables which are set to keep a lid on electricity emissions in the coming years.
One company making strides in this space is NexGen Cloud, which builds renewable-powered data centers in areas with untapped energy resources.
According to co-founder and CSO Youlian Tzanev, a large portion of AI workloads don’t need to be performed close to traditional logistical hubs like London or New York, and can be powered from more remote areas in countries like Canada and Norway with excess hydropower.
“We have significantly more power than people believe. The power just isn’t reaching the grid in many cases and is going to waste, and so that is where we focus our efforts,” Tzanev said.
In the U.S., Crusoe Energy Systems offers another example of startups finding innovative ways to power the AI boom. Crusoe’s modular data centers are designed to run on excess natural gas produced at oil wells, achieving a 99.9% methane reduction in the process.
Common forecasting pitfalls
Projecting an outlook for AI’s energy demands is far from straightforward. In its midyear electricity update, the IEA noted that estimates exhibit a wide range of uncertainty, with some analyses following overly “simplistic” extrapolations.
For instance, the organization said certain studies make the mistake of assuming data center operators build all the facilities for which they apply to utilities. Given that several applications can be made for each new data center, this can lead to a multiplication of estimates.
Within data centers themselves, it is tempting for forecasters to imagine computers working flat out around the clock, Koomey said. In practice, GPUs usually operate on much less than their full power capacity, he added.
Based on modeling carried out by Nvidia, GPUs on average tend to run on less than 70% of their potential power. One particular function, known as Multi-Instance GPU, enables workloads—and therefore energy consumption—to be split into seven distinct components, with each able to function independently.
In addition, the company noted the role of substitution effects, in which traditional computing workloads are transferred onto AI platforms and subsequently performed more efficiently—an aspect that can be easily overlooked.
Forecasts can also conflate local data-centre developments with broader energy demands , Koomey added, noting that the most common estimates for electricity demand come from local utility companies.
In the U.S. as a whole, electricity use actually fell in 2023 compared with the previous year, according to the U.S. Energy Information Administration. In March 2024—the most recent month of available data—total demand reached 306 billion kilowatt-hours, down from 317 billion kWh in the year-prior period.
“I worry that people are jumping on the explosive demand-growth train before really understanding what’s going on,” Koomey said. “If you cluster data centers in certain places you’re going to see some local power constraints, but that doesn’t necessarily mean that AI will be a key driver of electricity use more broadly.”
Corrections & Amplifications undefined Nvidia said it has experienced a 45,000 times improvement in GPU energy efficiency over the last eight years. An earlier version of this article incorrectly said the company developed its first GPU eight years ago. (Corrected on July 24)
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From snow-dusted valleys to festival-filled autumns, Bhutan reveals itself as a rare destination where culture, nature and spirituality unfold year-round.
On October 2, acclaimed chef Dan Arnold will host an exclusive evening, unveiling a Michelin-inspired menu in a rare masterclass of food, storytelling and flavour.