Carbon Trading Opens Loophole in Paris Climate Accord
Credits issued under the landmark Paris accord come with limited oversight as international trading ramps up

 4 min
When the South American nation of Guyana wanted to sell millions of carbon-offset credits to preserve its rainforests, government officials knew they had a problem: The country’s lush Amazonian forests were actually in good shape.
Guyana’s rate of deforestation was already low, meaning its forests wouldn’t yield much under standard methodologies for calculating carbon credits. So its government chose a new method that allows a large adjustment for countries with healthy forests. The change raised the credits that Guyana could issue sixfold. Guyana sold 37.5 million of them last year to U.S. oil giant Hess for at least $750 million, and is now shopping the remaining two thirds to countries facing pressure to comply with the landmark Paris climate accord, officials say.
That agreement calls for governments to adopt national plans to limit greenhouse-gas emissions and allows them to pay for emission-reduction projects elsewhere in the world to offset their own pollution. Credits for each ton of emissions cut can then be traded between countries. It is as if the emission reduction happened in the country buying the credit, not the one selling it.
Guyana is among the first in a long line of developing-world countries expected to cash in on credits compliant with United Nations agreements. Some officials worry the U.N. risks giving its seal of approval to credits for forests that aren’t under threat. At the COP28 climate summit under way in Dubai, negotiators are debating how much scrutiny carbon trading should face from U.N. experts and the public to prevent the mechanism from becoming a loophole in the Paris accord.
“If we play that game—every country gets to come in and pull an arbitrary methodology out of the ether, apply it to their forest areas and say give me credits—we’re never going to get anywhere,” said Kevin Conrad, the climate envoy of Papua New Guinea.
For now, the Paris accord imposes relatively little oversight on the market. Credits are required to undergo review by a panel of experts. But at last year’s COP in Egypt, governments decided that the experts wouldn’t be allowed to review the “appropriateness” or “adequacy” of projects.
That is fuelling fears the accord opens the door for polluting countries to buy lower-quality credits from poorer nations to meet their own emissions targets, undermining the Paris accord ambition of limiting global warming to 1.5 degrees Celsius above preindustrial era temperatures. Some developing countries are pushing for the right to keep much of the information around offset projects confidential. Companies would end up buying the credits, critics say, that would support spurious greenhouse-gas reduction claims. Hess said it would apply Guyana’s credits to its goal of completely offsetting its emissions by 2050.
“There is very little oversight of the process,” said Jonathan Crook of Carbon Market Watch, a Brussels-based nonprofit. “Some countries could set a higher bar, but there’s a risk that others do not.”
Guyana is in talks to sell credits to Singapore, which is evaluating whether it will accept the adjustment for low deforestation countries, an official involved in the talks said. The U.N.’s civil aviation agency last year said it would accept Guyana’s methodology under new regulations it set to limit emissions from international flights, making Guyana’s offsets the first eligible under the rules.
Switzerland is moving to purchase the first credits under the Paris accord, for non-forest projects in Ghana, Thailand and Vanuatu. The credits will then be used by Swiss companies to comply with the country’s greenhouse-gas limits under the Paris accord.
The Swiss government is refusing to invest in forestry projects because of uncertainties around the baseline against which the lack of deforestation is measured. Switzerland also has concerns around whether protections for forests are long term—a tree cut down or destroyed in the future would release the planet-warming carbon dioxide it has absorbed over its lifetime.
Corporations over the past decade have invested billions of dollars in greenhouse-gas offset projects in the developing world. Those projects yield so-called voluntary carbon credits: The companies are under no legal obligation to buy them but do so because of public commitments they have made to offset their carbon emissions.
Academic research and media reports have cast doubt on the impact of many of the projects underlying these credits. The problems were particularly acute in projects to prevent deforestation. Because such programs typically cover relatively small areas within a larger forest, they risk pushing logging and clear-cutting for agriculture into other sections that aren’t protected by a project.
Guyana’s project is designed to address some of these problems. It is one of the first to cover an entire nation, eliminating the possibility that deforestation could be displaced within the country. Covering around 45 million acres, it is one of the world’s largest forest-protection projects, according to Trove Research.
Guyana has some of the most pristine forests on the planet. They have been mostly spared the rampant logging and clear-cutting seen in neighbouring Brazil. Guyana lacks rich soil suitable for large-scale agriculture, a major driver of deforestation, scientists say.
“These are among the poorest soils on the planet,” said Janette Bulkan, a Guyanese forestry expert at the University of British Columbia.
Critics say issuing credits for protecting such forests violates a core principle of carbon crediting: They should only be issued for emissions that would have happened without the project.
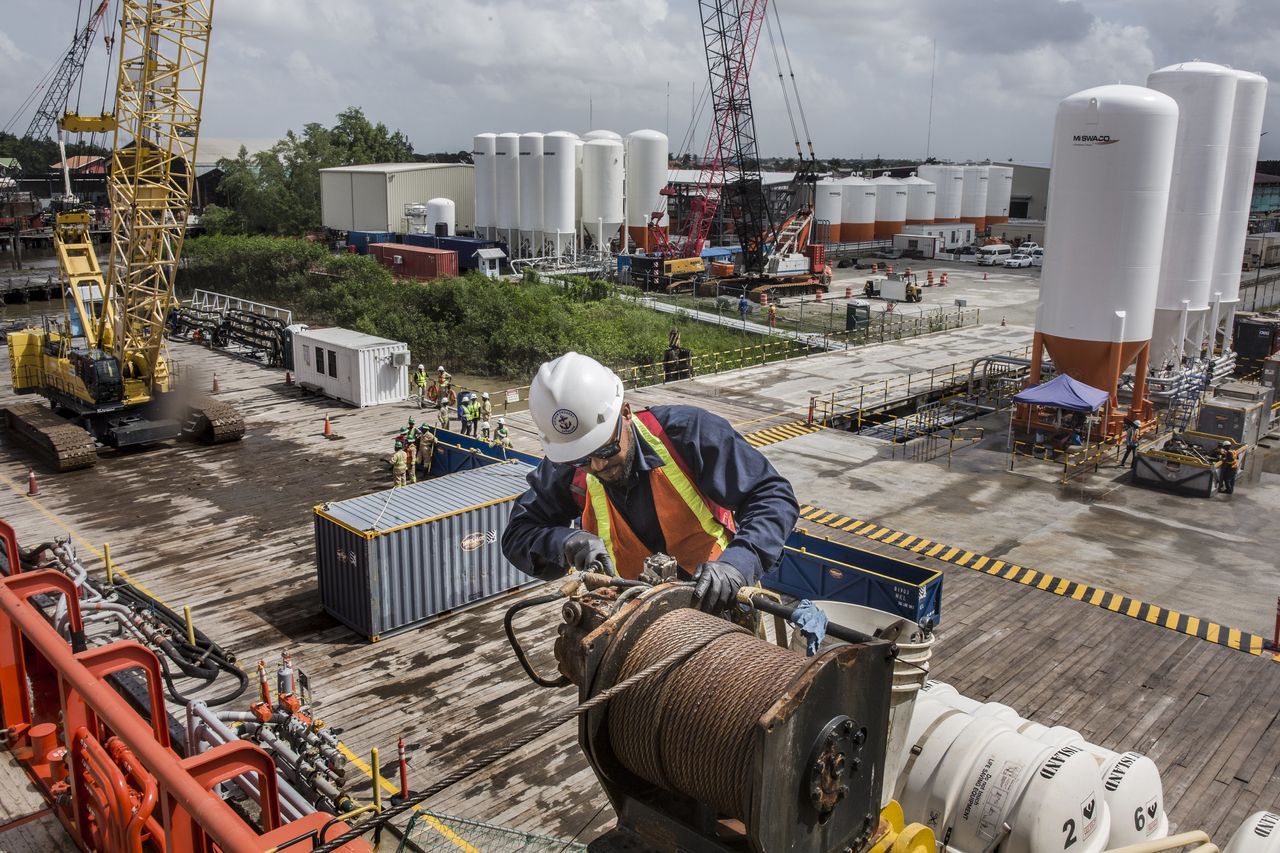
Guyanese officials say its forests are nevertheless at risk in the near future without intervention. The country’s economy is growing quickly, as is global demand for the commodities that could be extracted from its rainforests. Guyana is also reaping a windfall from oil discoveries off its coast that are now being pumped by Exxon Mobil and Hess.
“Guyana’s forests offer opportunities for a wide range of goods and services, and development opportunities for opening up areas for industry and manufacturing,” said Pradeepa Bholanath, who oversees climate policy at Guyana’s Ministry of Natural Resources.
Guyana’s credits have been calculated by Architecture for REDD+ Transactions, a program run by the U.S. nonprofit Winrock International. The program’s methodology allows countries like Guyana that have had little deforestation in the past to issue credits against a predicted future level of deforestation under a formula devised by Winrock.
Winrock and other advocates of the methodology say the money allows much-needed climate finance to flow to rain-forested countries, even if they haven’t experienced past deforestation. Guyana has already received more than $100 million in its deal with Hess. Officials say that money is reaching tribes that live in the rainforests and being used nationally for forest preservation and renewable energy projects.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
As interest rates, inflation and market sentiment fluctuate, investors are being urged to focus on data, not panic.
A Vaucluse masterpiece by MHNDU with interiors by Poco Designs brings architectural ambition and breathtaking ocean outlook to the auction block.