Electricity That Costs Nothing—or Even Less? It’s Happening More and More
A surge in wind and solar power means many businesses and consumers around Europe can get paid for plugging in. The U.S. could be next.

 5 min
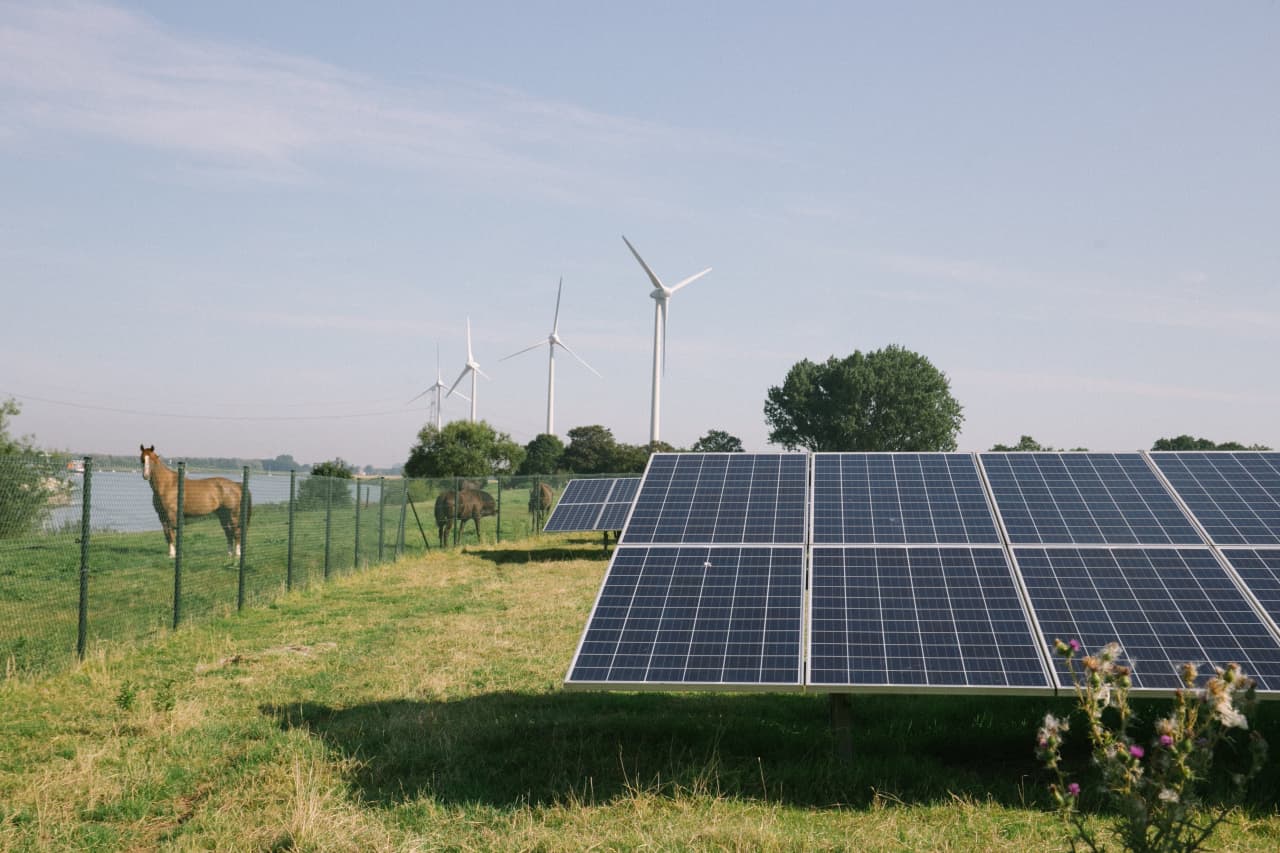
KERKDRIEL, the Netherlands—For much of the spring and summer, Jeroen van Diesen got paid for using electricity.
Sometimes his neighbours came over to power up too, generating even more cash.
Van Diesen’s situation reflects the strange, new dynamics of electricity that could soon become the norm in many parts of the world: A big increase in wind and solar power has pushed wholesale prices to zero or below for many hours of the year, spurring a sea change in the way people use power—based on whether the sun is shining or the wind is blowing.
Most people pay a fixed price for each kilowatt-hour of electricity they consume throughout the day. The price is set by their power company and only changes at infrequent intervals—once a week, a month or even only once a year.
Van Diesen, a software salesman, recently signed up to receive electricity from two providers that charge him the hourly price on the Dutch wholesale power market, rather than a fixed price that resets monthly or annually. When the price of electricity falls low enough, smart meters in his house begin charging his two electric cars.
Wholesale prices swing wildly each hour of the day, and even more so as a larger share of electricity flows from wind and solar installations. Because the generation costs of wind or solar farms are negligible, market prices will be near zero when there is enough renewable power to cover most of a region’s electricity demand.
Electricity market dynamics get weirder when renewable-energy producers don’t have an incentive to stop feeding power into the grid, usually because of government subsidies. Then grids can be flooded with excess power, pushing prices into negative territory.
Van Diesen said he’s made 30 euros, equivalent to around $34, over the past five months charging his car, enough to cover the service fee from his power supplier, a Norwegian company called Tibber.
“I’m charging the car for free,” said van Diesen, who is part of a group of clean-energy enthusiasts in the Netherlands who call themselves green nerds. “To me it’s also like a hobby and a game—how far can I go?”
Doing laundry in the evening? The electricity could be free a few hours later when demand dies down and the wind picks up. Likewise, in regions with lots of solar power, charging an electric vehicle in the morning is usually far more expensive than powering up under the midday sun—or whenever the price is right.
In the U.S., most states don’t currently allow such real-time pricing, but many think that will change. Already, in some of the world’s biggest economies from Western Europe to California, the occurrence of zero and negative wholesale power prices is growing fast.
Negative prices
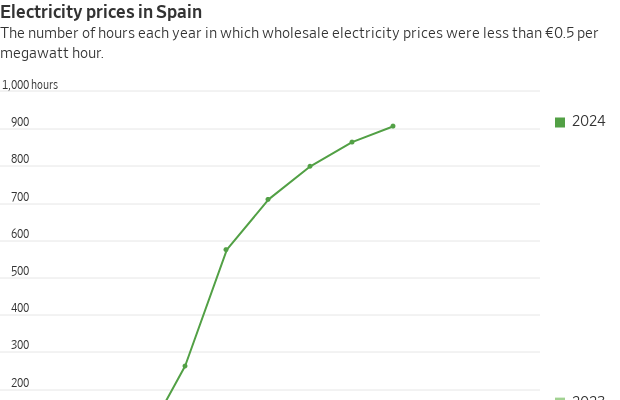
Wholesale prices across continental Europe have fallen to zero or below in 6% of all hours this year, up sharply from 2.2% in 2023 and just 0.3% in 2022, according to data collected by Entso-E, the group of European transmission system operators. In markets with lots of renewable capacity, this year’s figure was higher: 8% in the Netherlands, 11% in Finland and 12% in Spain. Analysts expect those numbers will grow as more solar panels and wind turbines are installed.
The changes sweeping Europe’s electricity markets, which were accelerated by the energy crisis brought on by the war in Ukraine, show what could happen in the U.S. in a few years when renewable capacity reaches a similar scale. In 2023, 44% of EU electricity was generated by renewables, compared with 21% in the U.S.
In some U.S. markets—sunny California, the wind-swept Great Plains, and Texas—zero and negative prices are already common. The wholesale price in Southern California was negative nearly 20% of all hours this year because of the region’s boom in solar-panel installations. That compares to around 5% last year, according to data collected by the U.S. Energy Information Administration.
U.S. regulators have been cautious about allowing households and companies to sign up for electricity plans that charge them wholesale prices, fearing consumers could be hit with big bills if prices jump. Texas consumers who signed such contracts were walloped with huge bills in 2021 when a rare winter storm sent prices soaring.
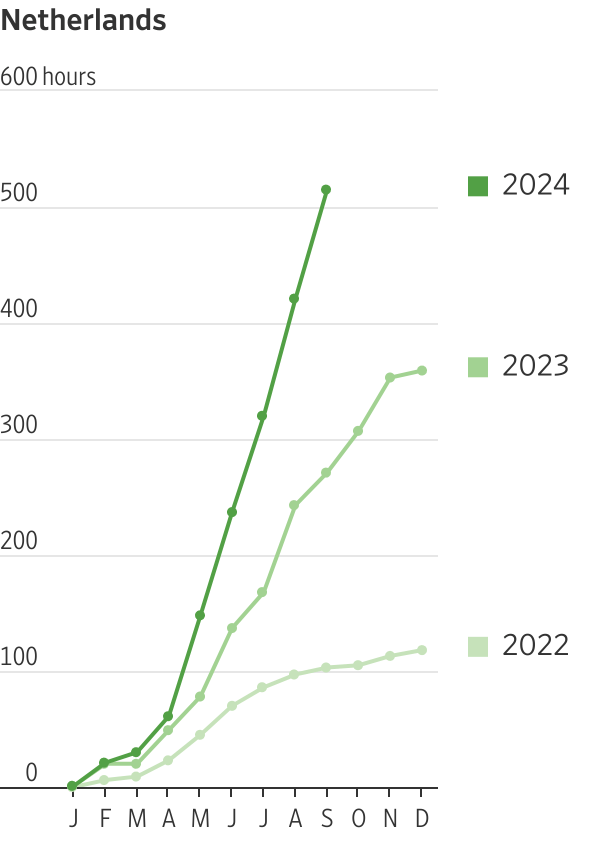

States’ reluctance, however, may now be waning as policymakers increasingly see real-time pricing as a way to lower peak demand, reduce the need for costly infrastructure and integrate more renewables into the grid.
California regulators this year ordered the state’s utilities to expand dynamic price pilot programs that have only been available for a select group of customers.
Your overall power bill still won’t be zero in a clean-energy future. Generation costs comprised around 60% of customer bills on average in the U.S. in 2023. Transmission and distribution costs account for most of the rest—and are expected to grow sharply in the coming decade to reinforce the grid for electric heating, electric transport and data centers.
Negative prices could also be reined in over the next few years as governments from Europe to California pare back renewable-energy subsidies. Governments are particularly focused on trimming subsidies for solar power, which is driving negative prices in a number of markets.
Green nerds
In Europe, energy-hungry manufacturers are shifting their operating strategies to maximise energy consumption when prices are close to zero or negative, while throttling back when prices are high.
Linde, a U.K.-based engineering company, is building a new generation of industrial gas plants that can be quickly ramped up and down depending on the wholesale price of power.
When solar and wind power drive prices down, Linde’s plants fire up and send the output to large tanks. When electricity prices shoot up again, the plants can ramp back down and supply customers out of the gases stored in the tanks.
“The tank functions like a virtual battery,” said Klaus Ohlig, a research and development executive at Linde Engineering.
Trimet, an aluminium producer that is one of Germany’s single-largest power consumers, is overhauling its smelters to vary their power consumption depending on the availability of renewable energy on the grid.
A new European Union law requires dynamic-price power contracts be made available to consumers across the 27-nation bloc. Tibber, a power retailer based in Norway that charges its customers the wholesale hourly price, has signed up more than one million households across the Nordic countries, Germany and the Netherlands.
Edgeir Aksnes, Tibber’s co-founder and chief executive, says he doesn’t expect customers to constantly track the hourly price before deciding when to charge their car or run appliances.
“We can automate all of this for you. You don’t have to think about it,” he said.
Some enthusiasts, however, like to get into the weeds.
Wouter van Embden, a 49-year-old Dutch entrepreneur and one of the country’s so-called green nerds, switched to Tibber earlier this year. On a recent summer Sunday, the battery in his home began charging as solar power flooded the Dutch grid and the wholesale power price fell to zero. He also charged his two electric cars and programmed his heat pump to make the water in the house tank extra hot.
Toward the evening, as prices rose with the drop-off in solar, van Embden’s battery—which he and his son built at home—would power his home as well as feed into the Dutch grid.
“I have to be honest, when I started building the battery I had so many outages. There was a lot of testing to do,” he said. “But now it’s working pretty stable.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Rising rates, construction inflation and shrinking investor confidence are pushing Australia deeper into a dangerous housing spiral that monetary policy alone cannot fix.

Once a sleepy surf town, Noosa has become Australia’s prestige property hotspot, where multi-million dollar knockdowns, architectural showpieces and record-setting sales are the new normal.