Chasing Passive Income, Americans Turn to Vending Machines
How candy and soda machines became an unlikely trending investment idea of the 2020s

 5 min
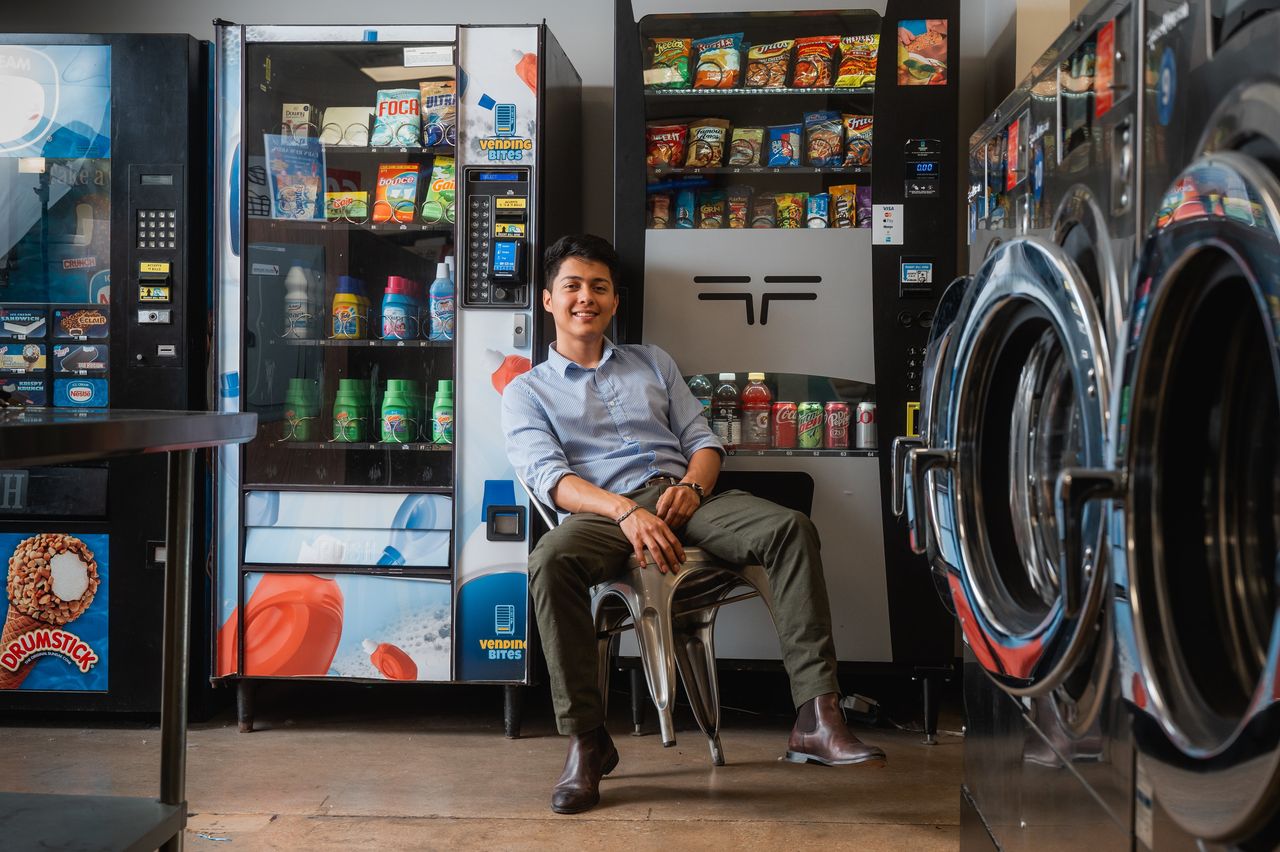
With a brick of cash in his hand and a grin on his face, Jaime Ibanez shows his half-million YouTube subscribers a path to earning money without burning many calories: Vending machines.
In videos with titles such as “This Is HOW MUCH My Vending Machines Made IN 7 DAYS!!” the swoopy-haired 23-year-old Texan makes the rounds to his 51 machines, stocking them and taking the profits.
His channel promotes the idea that with diligence and luck, anyone can go from snacks to riches.
Vending machines might seem an unlikely candidate for trending investment of the 2020s, but the idea has captured the imagination of Americans dreaming of easier money. Some pursue chips and soda as a side hustle because their regular paychecks aren’t enough for them to get by. Others bet on vending machines as a ticket to upward mobility, to quitting their jobs and becoming their own boss.
The startup cost is low and the formula simple. Buy a used machine for $1,500, load it up with products from Costco , charge a 100% markup and let the crinkled dollars roll in. But turning a profit takes real work, and the machines can be a losing proposition when stuck in locations without enough hungry foot traffic.
There is a fair amount of competition, too. America has three million vending machines, an $18.2 billion industry, with the average machine generating about $525 in monthly revenue, according to the National Automatic Merchandising Association.
More than half of operators bring in less than $1 million a year, according to trade publication Automatic Merchandiser. Many are individuals who have other jobs.
Social media has fuelled the notion of finding financial freedom in vending machines. Between 2019 and 2023, the number of posts or comments mentioning passive income and vending machines more than tripled on X and increased by a factor of six on Instagram, according to Sprinklr, a social-media management platform. Google search interest in passive income increased some 75% during that same period.
“There’s a real sense that doing things the so-called right way won’t necessarily land you in the middle class,” said Lana Swartz, a media-studies professor at the University of Virginia who researches financial technologies. “If the old rules no longer apply, then there’s a searching for new rules to get ahead or to get by.”
Some vending-machine newbies say they are on their way to building an automated empire. Others’ dreams get snagged like a bag of Funyuns on a faulty coil.
Making sales while you sleep
Last spring Rob Smith, a 30-year-old truck driver in Orlando, Fla., spent $4,000 on his first machine, a credit-card reader and a load of snacks and drinks.
He recently acquired his fourth machine, which is at an industrial bakery. His first three machines take up three to five hours of his week and bring in about $1,500 a month in revenue, which works out to roughly $750 in profit.
“I’ve made sales at four o’clock in the morning, when I was sleeping,” he said. “That machine is still working whether I’m there or not.”
He hopes to scale up to 30 machines and quit his job.
Smith started looking for extra income because his goal of buying a house felt out of reach with only his day job’s pay. He chose vending specifically after he witnessed a colleague complain about a malfunctioning machine at work and then use it anyway.
“He still put his $2 in,” Smith said. “I was like, ‘I need to get a vending machine as soon as possible.’ ”
Some budding vendors pay $300 or more for online courses to learn the trade. Smith relied on YouTube, Instagram and Reddit to get going.
At one point, he stocked a machine with orange soda against the advice he got in an online forum. When it didn’t sell, he and his family had to drink three dozen cans themselves.
Empty calories
Tom and Missi Hakes of Midway, Ala., started vending after Missi, 40, saw videos on YouTube about the business. The idea seemed more appealing than their stints driving for Uber, shopping for Instacart and trying to make it as YouTubers.
The Hakes, who both have full-time jobs in health insurance, scouted out locations in Atlanta, the closest big city and two hours away. After their best lead fell through, they paid a woman they found on Facebook Marketplace $500 to find a location for them.
She sent them to two spots that didn’t work out, including a cheerleading gym. The manager there was on board until she learned that the Hakes hadn’t operated a vending machine before.
Tom, 48, posted on a forum wondering how to address questions about their industry experience. At their next meeting, with the owner of a gym, they reluctantly followed some of the forum’s advice: They lied and said they had a few machines.
“We didn’t want to get another no,” said Tom.
He then spent a month repairing a used machine they bought for $1,400, staying up on some nights until 2 a.m.
When it was ready, Tom and Missi struggled to wrangle it into the 15-foot U-Haul truck they rented.
“Two people is not enough to move an 800-pound machine,” she said.
The Hakes spent about $2,500 on their vending business, as well as 20 to 30 hours a week for much of last fall.
They pay $50 a month to park it in the gym and it costs about $330 to fill up. It is currently grossing about $30 a week.
If anything, the income has been too passive, Tom said, “because it’s not really doing a lot of sales.”
If the machine isn’t selling more by summer, the Hakes will consider leaving the location, or perhaps vending machines overall.
Hit Facebook Marketplace, then Costco
Used vending machines of questionable quality sell online for as little as $500. More reliable ones cost in the range of $1,000 to $2,000, according to veteran vendors. A new machine with a touch screen and a robotic arm could cost upward of $7,000.
Many used machines have a maintenance issue about once a year, and they need to be cleaned. Cash is dirty, said Ben Gaskill of Everest Ice and Water Systems, a vending-machine maker. “Somebody digs around for coins in the bottom of their purse and it’s got grape jelly on it.”
Vendors shop warehouse stores like Costco and Sam’s Club to stock up. One machine’s worth of snacks or drinks can cost $200 to $300 a month. Owners then charge about twice what they paid for each product, or more. Prices of food from vending machines were up 10.6% year over year in January, according to Labor Department data.
The top-selling items in vending machines are cold drinks, snacks and candy, according to the latest data from Automatic Merchandiser magazine.
“No matter how healthy you try to make the machines, people are going to buy that Snickers bar,” said Lory Strickland, who sells courses and one-on-one coaching with her husband, Barry, under the name The Vending Mentors.
A never-vending story
Selling online classes and coaching can sometimes be more lucrative than a given moneymaking idea itself, said Swartz, the University of Virginia professor.
In online forums, she said, “there’s the joke that if there are people making courses about it, then it’s already oversaturated as a side hustle.”
To capitalise on interest in vending, some experienced operators started selling their expertise to supplement the income coming in from their machines. Some transitioned primarily to training.
Hyping the vending-machine dream predates the internet, though. The first machines in the U.S. sold gum and appeared on train platforms in 1888.
In the 1940s, media outlets cautioned about “get-rich-quick schemes” promoted by “unscrupulous agents involving vending machines.” In 1960, the magazine now known as Kiplinger Personal Finance warned of “vultures in the business” who promised “that an $800 investment may produce $200 a month, and that only a few hours of work a week are required to enjoy such rich pickings.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
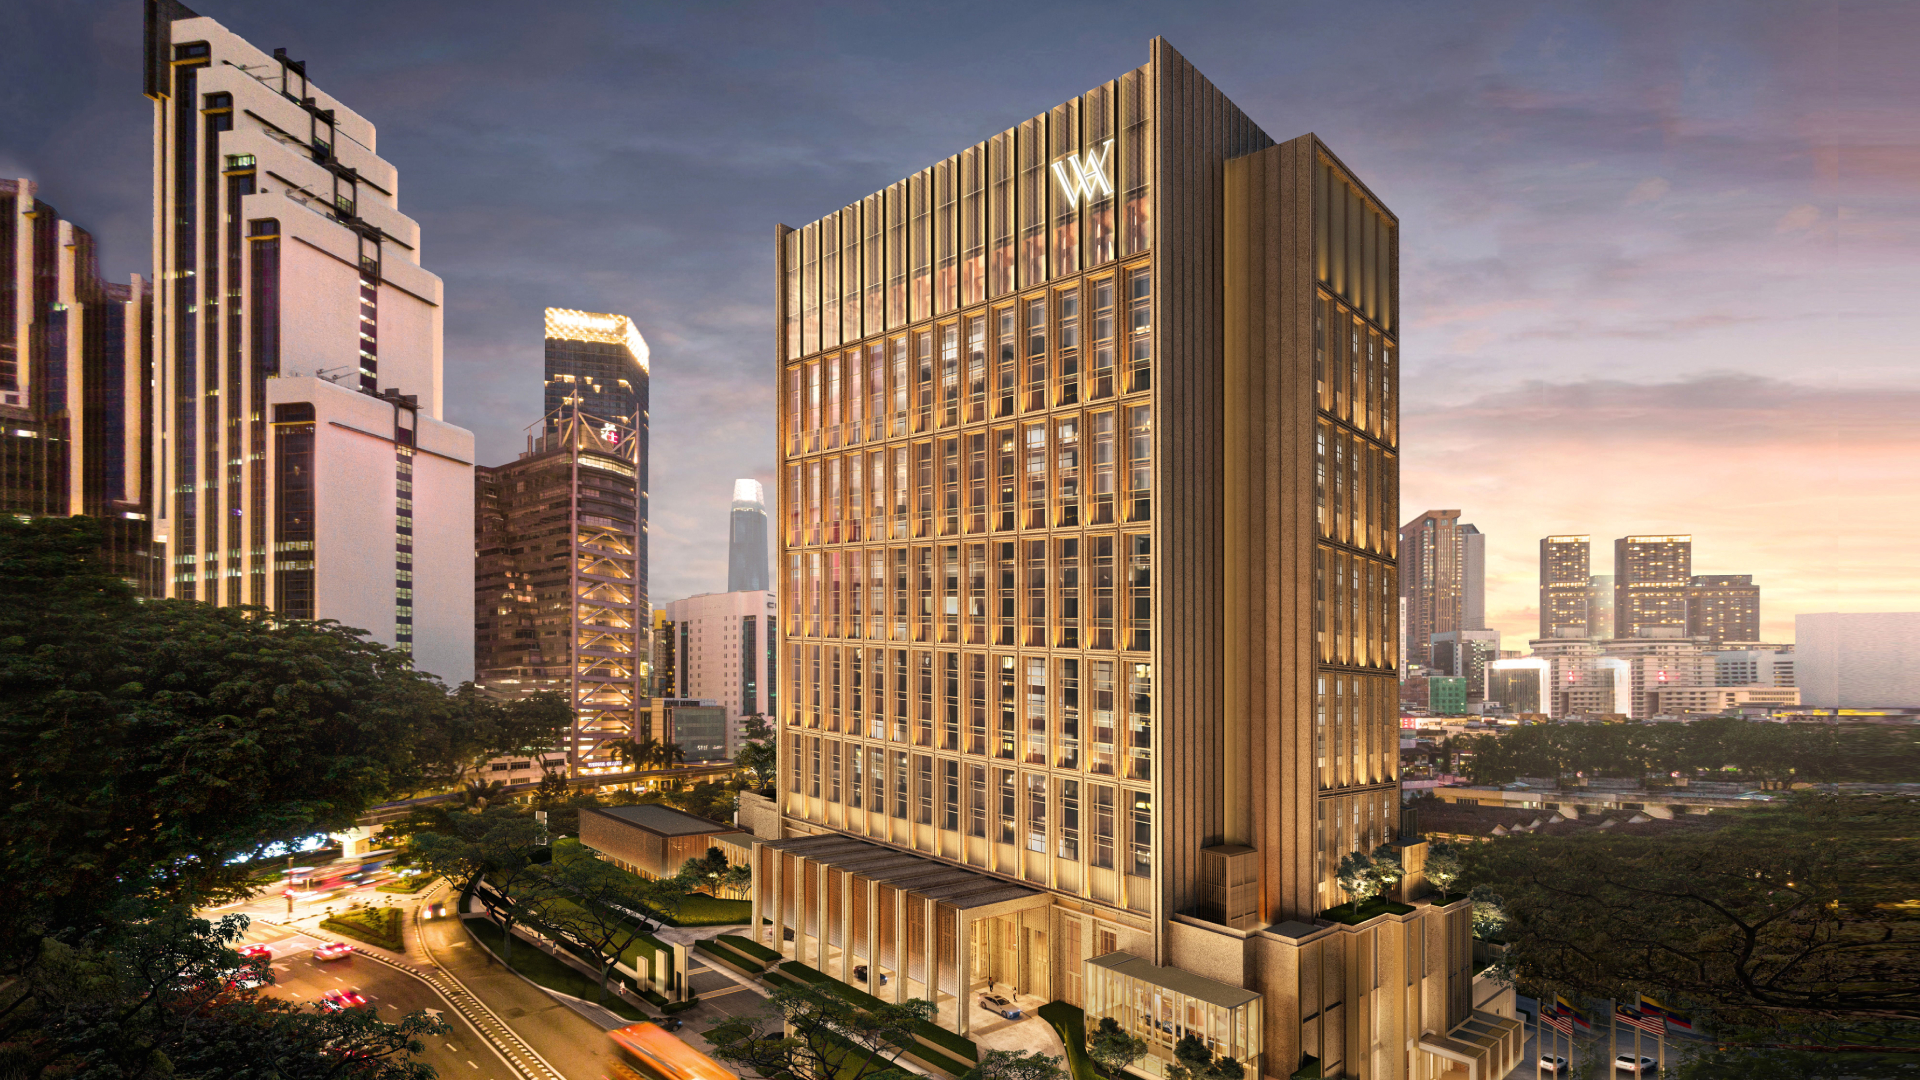
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

By improving sluggish performance or replacing a broken screen, you can make your old iPhone feel new agai
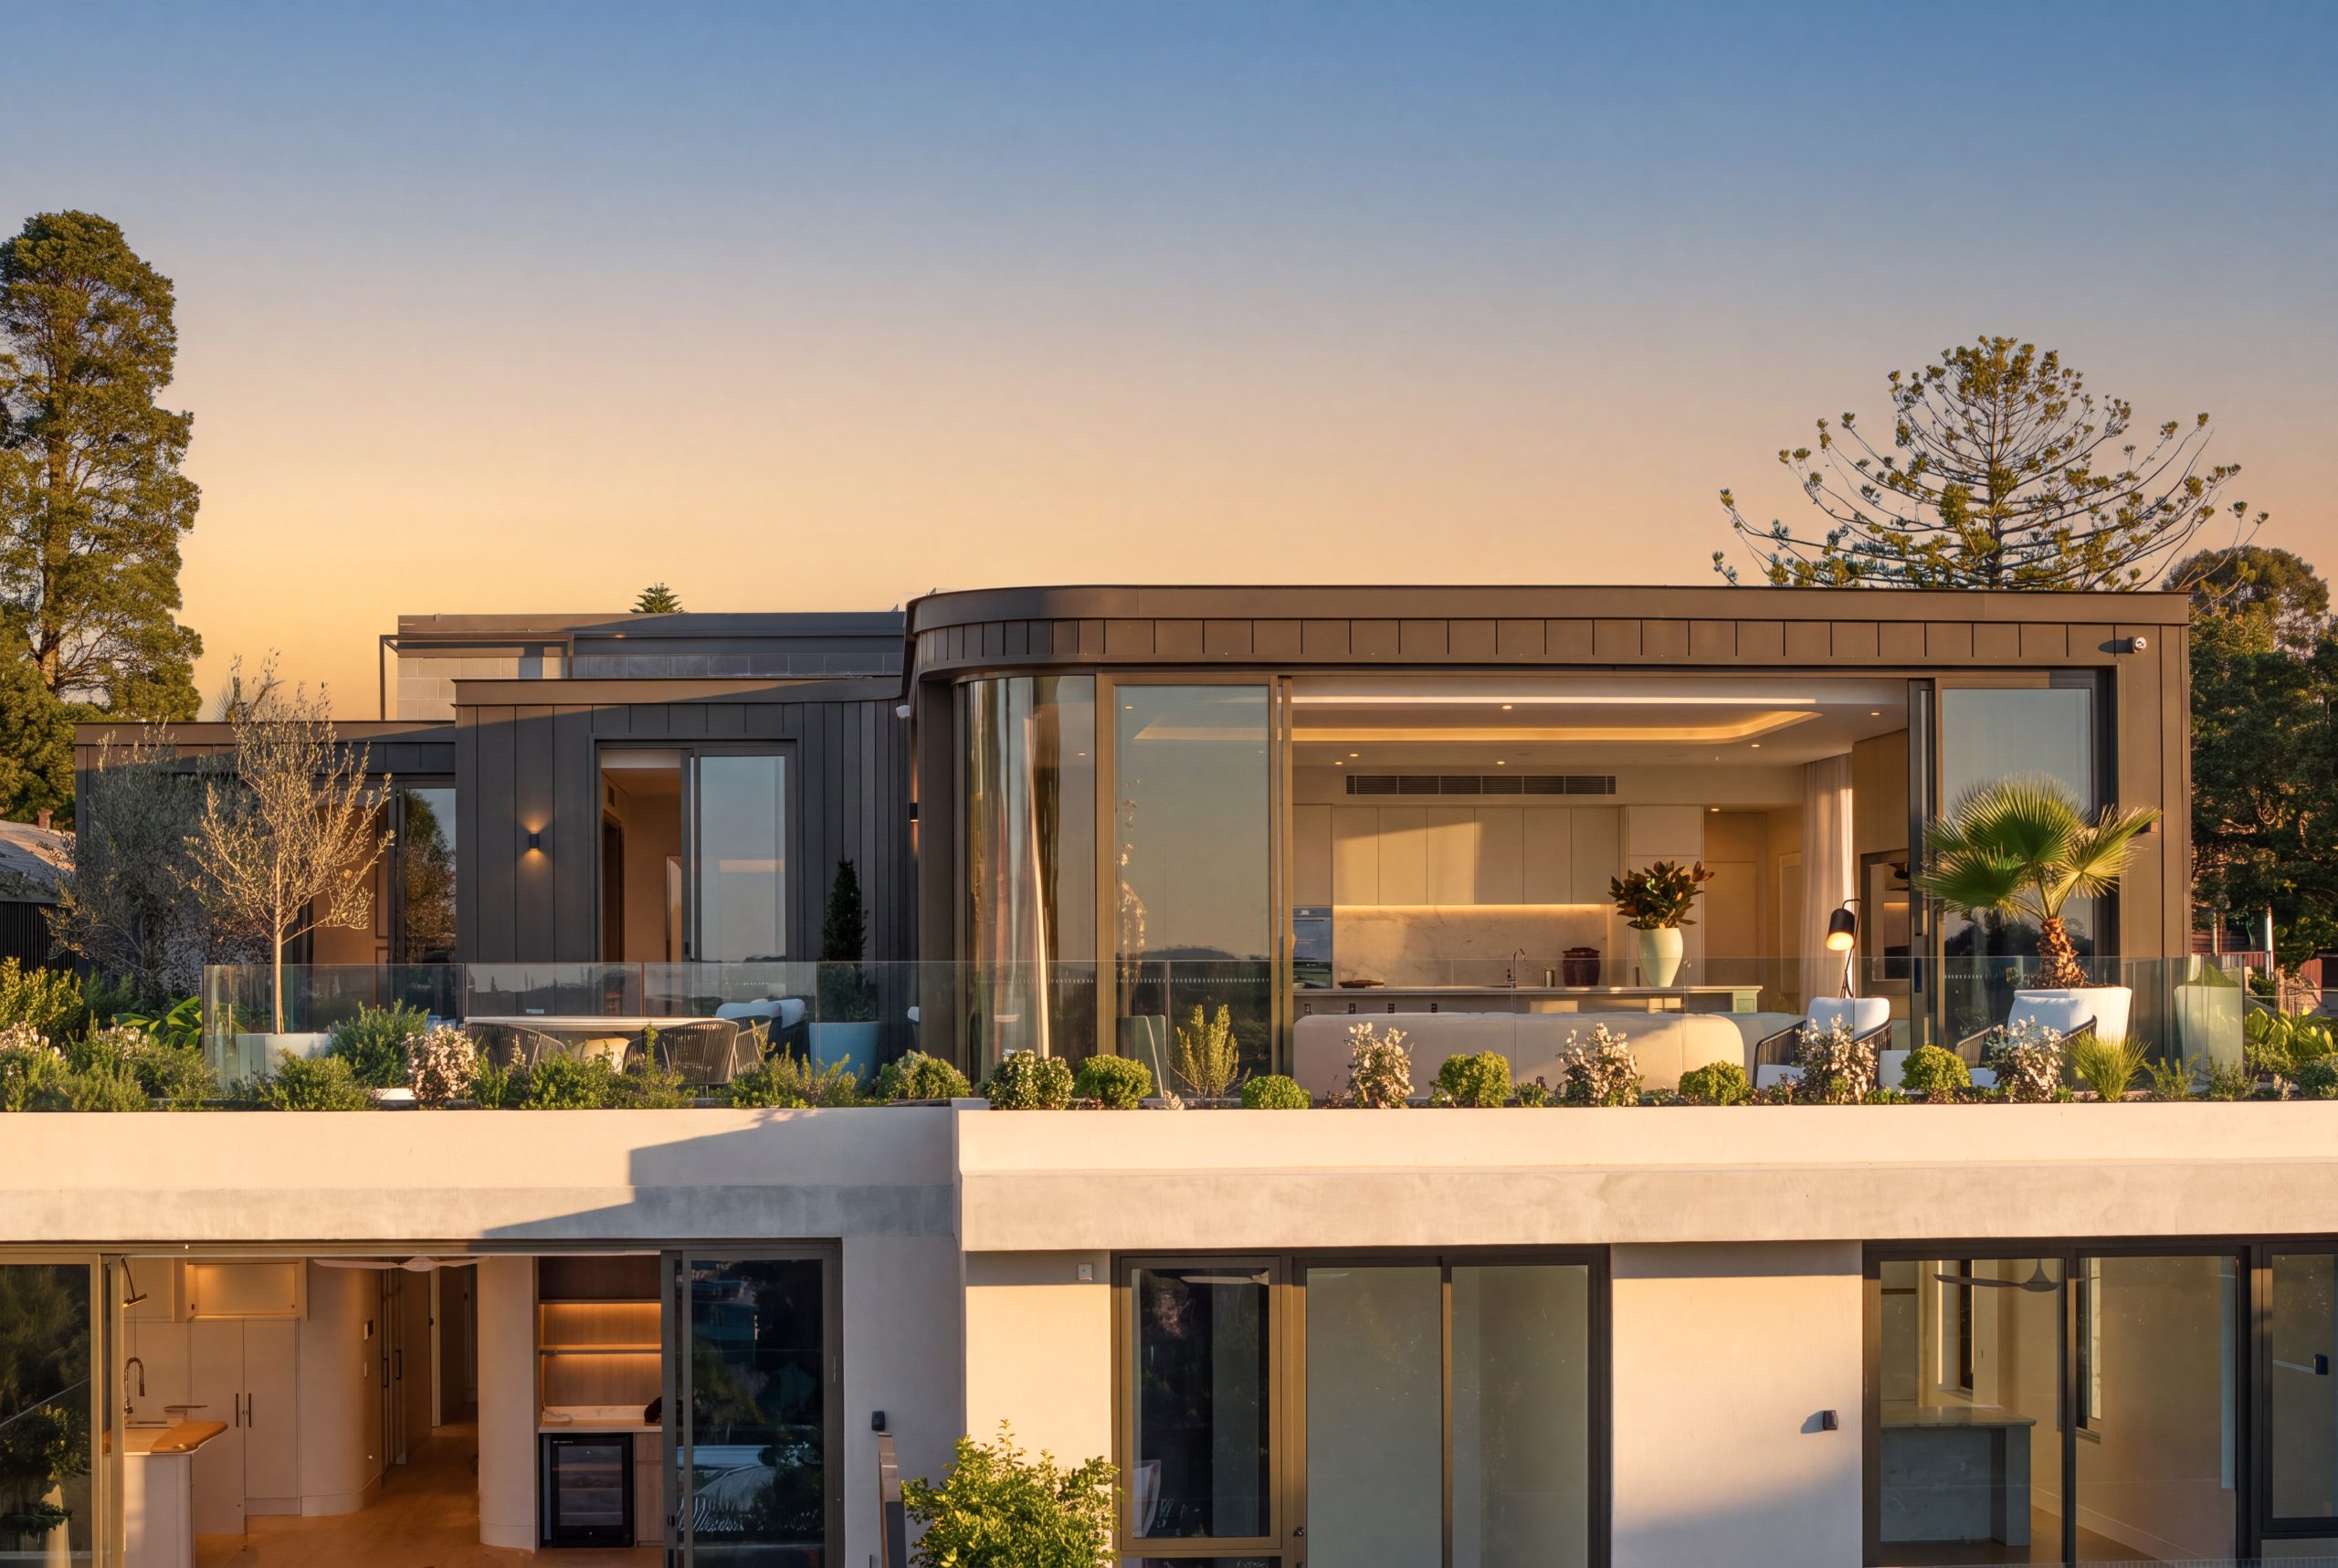
The completed penthouse at Park Residences showcases a considered approach to luxury apartment living, combining northern light, curated interiors and the privacy of a whole-floor residence.