ChatGPT Comes Under Investigation by Federal Trade Commission
FTC is examining whether the artificial-intelligence app harmed people by publishing false information

 4 min
WASHINGTON—The Federal Trade Commission is investigating whether OpenAI’s ChatGPT has harmed people by publishing false information about them, posing a potential legal threat to the popular app that can generate eerily humanlike content using artificial intelligence.
In a civil subpoena to the company made public Thursday, the FTC says its investigation of ChatGPT focuses on whether OpenAI has “engaged in unfair or deceptive practices relating to risks of harm to consumers, including reputational harm.”
One question asks the company to “describe in detail the extent to which you have taken steps to address or mitigate risks that your large language model products could generate statements about real individuals that are false, misleading or disparaging.”
The new FTC investigation under Chair Lina Khan marks a significant escalation of the federal government’s role in policing the emerging technology.
Khan, who appeared before the House Judiciary Committee on Thursday, said the agency is concerned that ChatGPT and other AI-driven apps have no checks on the data they can mine.
“We’ve heard about reports where people’s sensitive information is showing up in response to an inquiry from somebody else,” Khan said. “We’ve heard about libel, defamatory statements, flatly untrue things that are emerging. That’s the type of fraud and deception that we are concerned about.”
For critics of the FTC, the probe represented another venture into uncharted territory for an agency that has suffered recent legal setbacks in its antitrust enforcement efforts.
“When ChatGPT says something wrong about somebody and might have caused damage to their reputation, is that a matter for the FTC’s jurisdiction? I don’t think that’s clear at all,” said Adam Kovacevich, founder of Chamber of Progress, an industry trade group.
Such matters “are more in the realm of speech and it becomes speech regulation, which is beyond their authority,” he said.
OpenAI didn’t respond to requests for comment.
Marc Rotenberg, who heads a group that filed an FTC complaint over ChatGPT in March, said it might be unclear whether the FTC has jurisdiction over defamation. But “misleading advertising is clearly within the FTC’s purview,” said Rotenberg, president of the Center for AI and Digital Policy. “And disinformation relating to commercial practices is already, according to the FTC, an area within its authority.”
Rotenberg’s group filed a complaint with the FTC in March concerning ChatGPT, terming it “biased, deceptive and a risk to privacy and public safety,” and arguing that it satisfies none of the FTC’s guidelines for AI use.
The FTC has broad authority to police unfair and deceptive business practices that can harm consumers, as well as unfair competition, but critics say Khan has sometimes pushed its authority too far—as illustrated by a federal judge’s decision this week to dismiss the FTC’s attempt to block Microsoft’s acquisition of Activision Blizzard.
At the House committee hearing Thursday, Khan came under fire for her agency’s investigation of Twitter’s privacy protections for consumers. Republicans say the probe was driven by progressives angry over Elon Musk’s takeover of Twitter and his loosening of content moderation policies. And Twitter asked a federal court Thursday to terminate a 2022 settlement it agreed to with the FTC over alleged privacy violations, saying it had been subject to a “burdensome and vexatious enforcement investigation.”
Khan responded that the agency was only interested in protecting the privacy of users and that “we are doing everything to make sure Twitter is complying with the order.”
In its civil subpoena to OpenAI, the FTC asked the company detailed questions about its data-security practices. It cited a 2020 incident in which the company disclosed a bug that allowed users to see information about other users’ chats and some payment-related information.
Other topics covered by the FTC subpoena include the company’s marketing efforts, its practices for training AI models, and its handling of users’ personal information. The FTC inquiry was reported earlier by the Washington Post.
The Biden administration has begun examining whether checks need to be placed on artificial-intelligence tools such as ChatGPT. In a first step toward potential regulation, the Commerce Department in April put out a formal public request for comment on what it called accountability measures.
The White House’s Office of Science Technology Policy is also working to develop strategies to address both the benefits of AI, such as the possibility of using it to expand access to government services, as well as harms such as increased hacking capabilities, discriminatory decisions by AI systems, and the potential for AI-generated content to disrupt elections.
Lawmakers in both parties—led by Senate Majority Leader Chuck Schumer (D., N.Y.)—also have made regulating artificial intelligence a priority for the current Congress.
In addition to concerns about potential reputational risks, lawmakers say they worry that AI tools can be abused to manipulate voters with disinformation, discriminate against minority groups, commit sophisticated financial crimes, displace millions of workers or create other harms. Lawmakers have been especially concerned about the risks of so-called deepfake videos that falsely depict real people taking embarrassing actions or making embarrassing statements.
But new legislation or other measures are likely months away, if not longer. And lawmakers must worry that any significant action they take will risk slowing the pace of U.S. innovation, in what is shaping up as a vital competition with China to dominate the markets for AI tools.
Even ChatGPT’s creators have urged more government oversight of AI development.
In a hearing before Congress in May, OpenAI Chief Executive Sam Altman called on Congress to create licensing and safety standards for advanced artificial-intelligence systems, as lawmakers begin a bipartisan push toward regulating the powerful new tools available to consumers.
“We understand that people are anxious about how it can change the way we live. We are, too,” Sam Altman said of AI technology at the Senate subcommittee hearing. “If this technology goes wrong, it can go quite wrong.”
Altman has been traveling the world talking about both the promise and perils of AI, including meeting with heads of state including French President Emmanuel Macron and Indian Prime Minister Narendra Modi.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
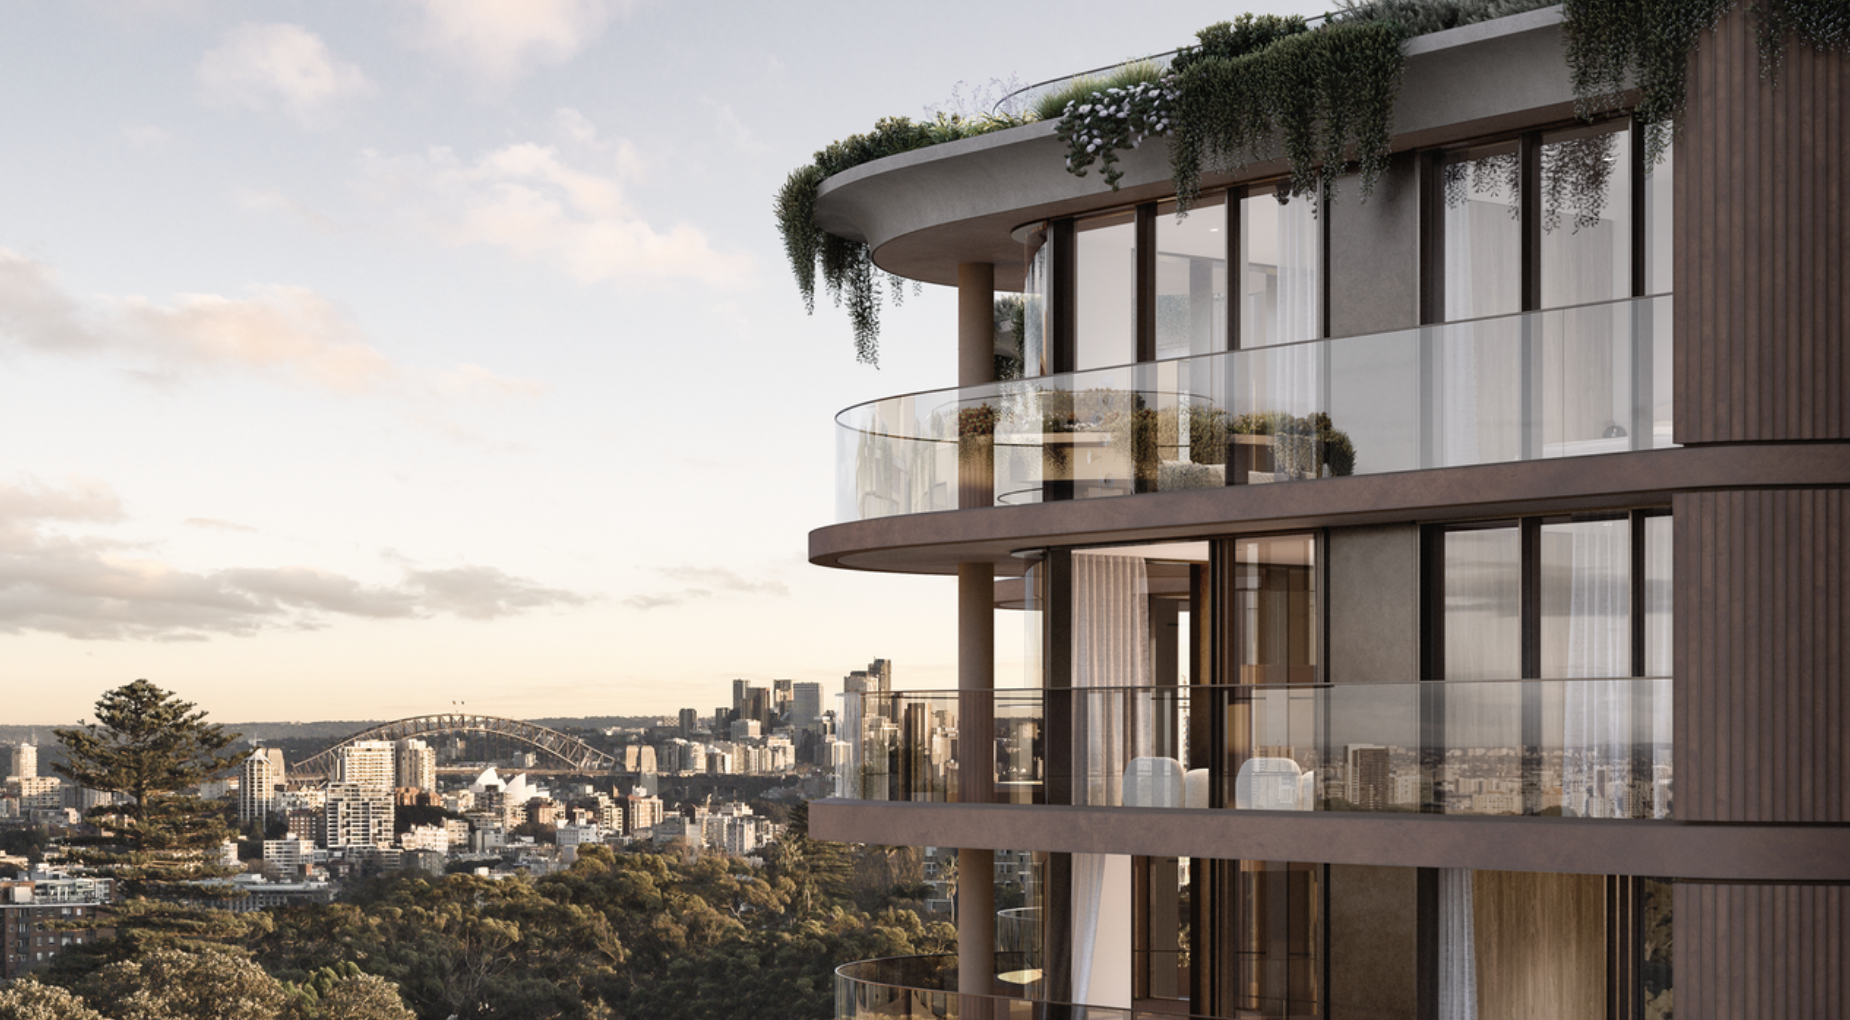
A record-breaking $11 million sale at The Centennial Collection has set a new benchmark for luxury apartment living in Bondi Junction.
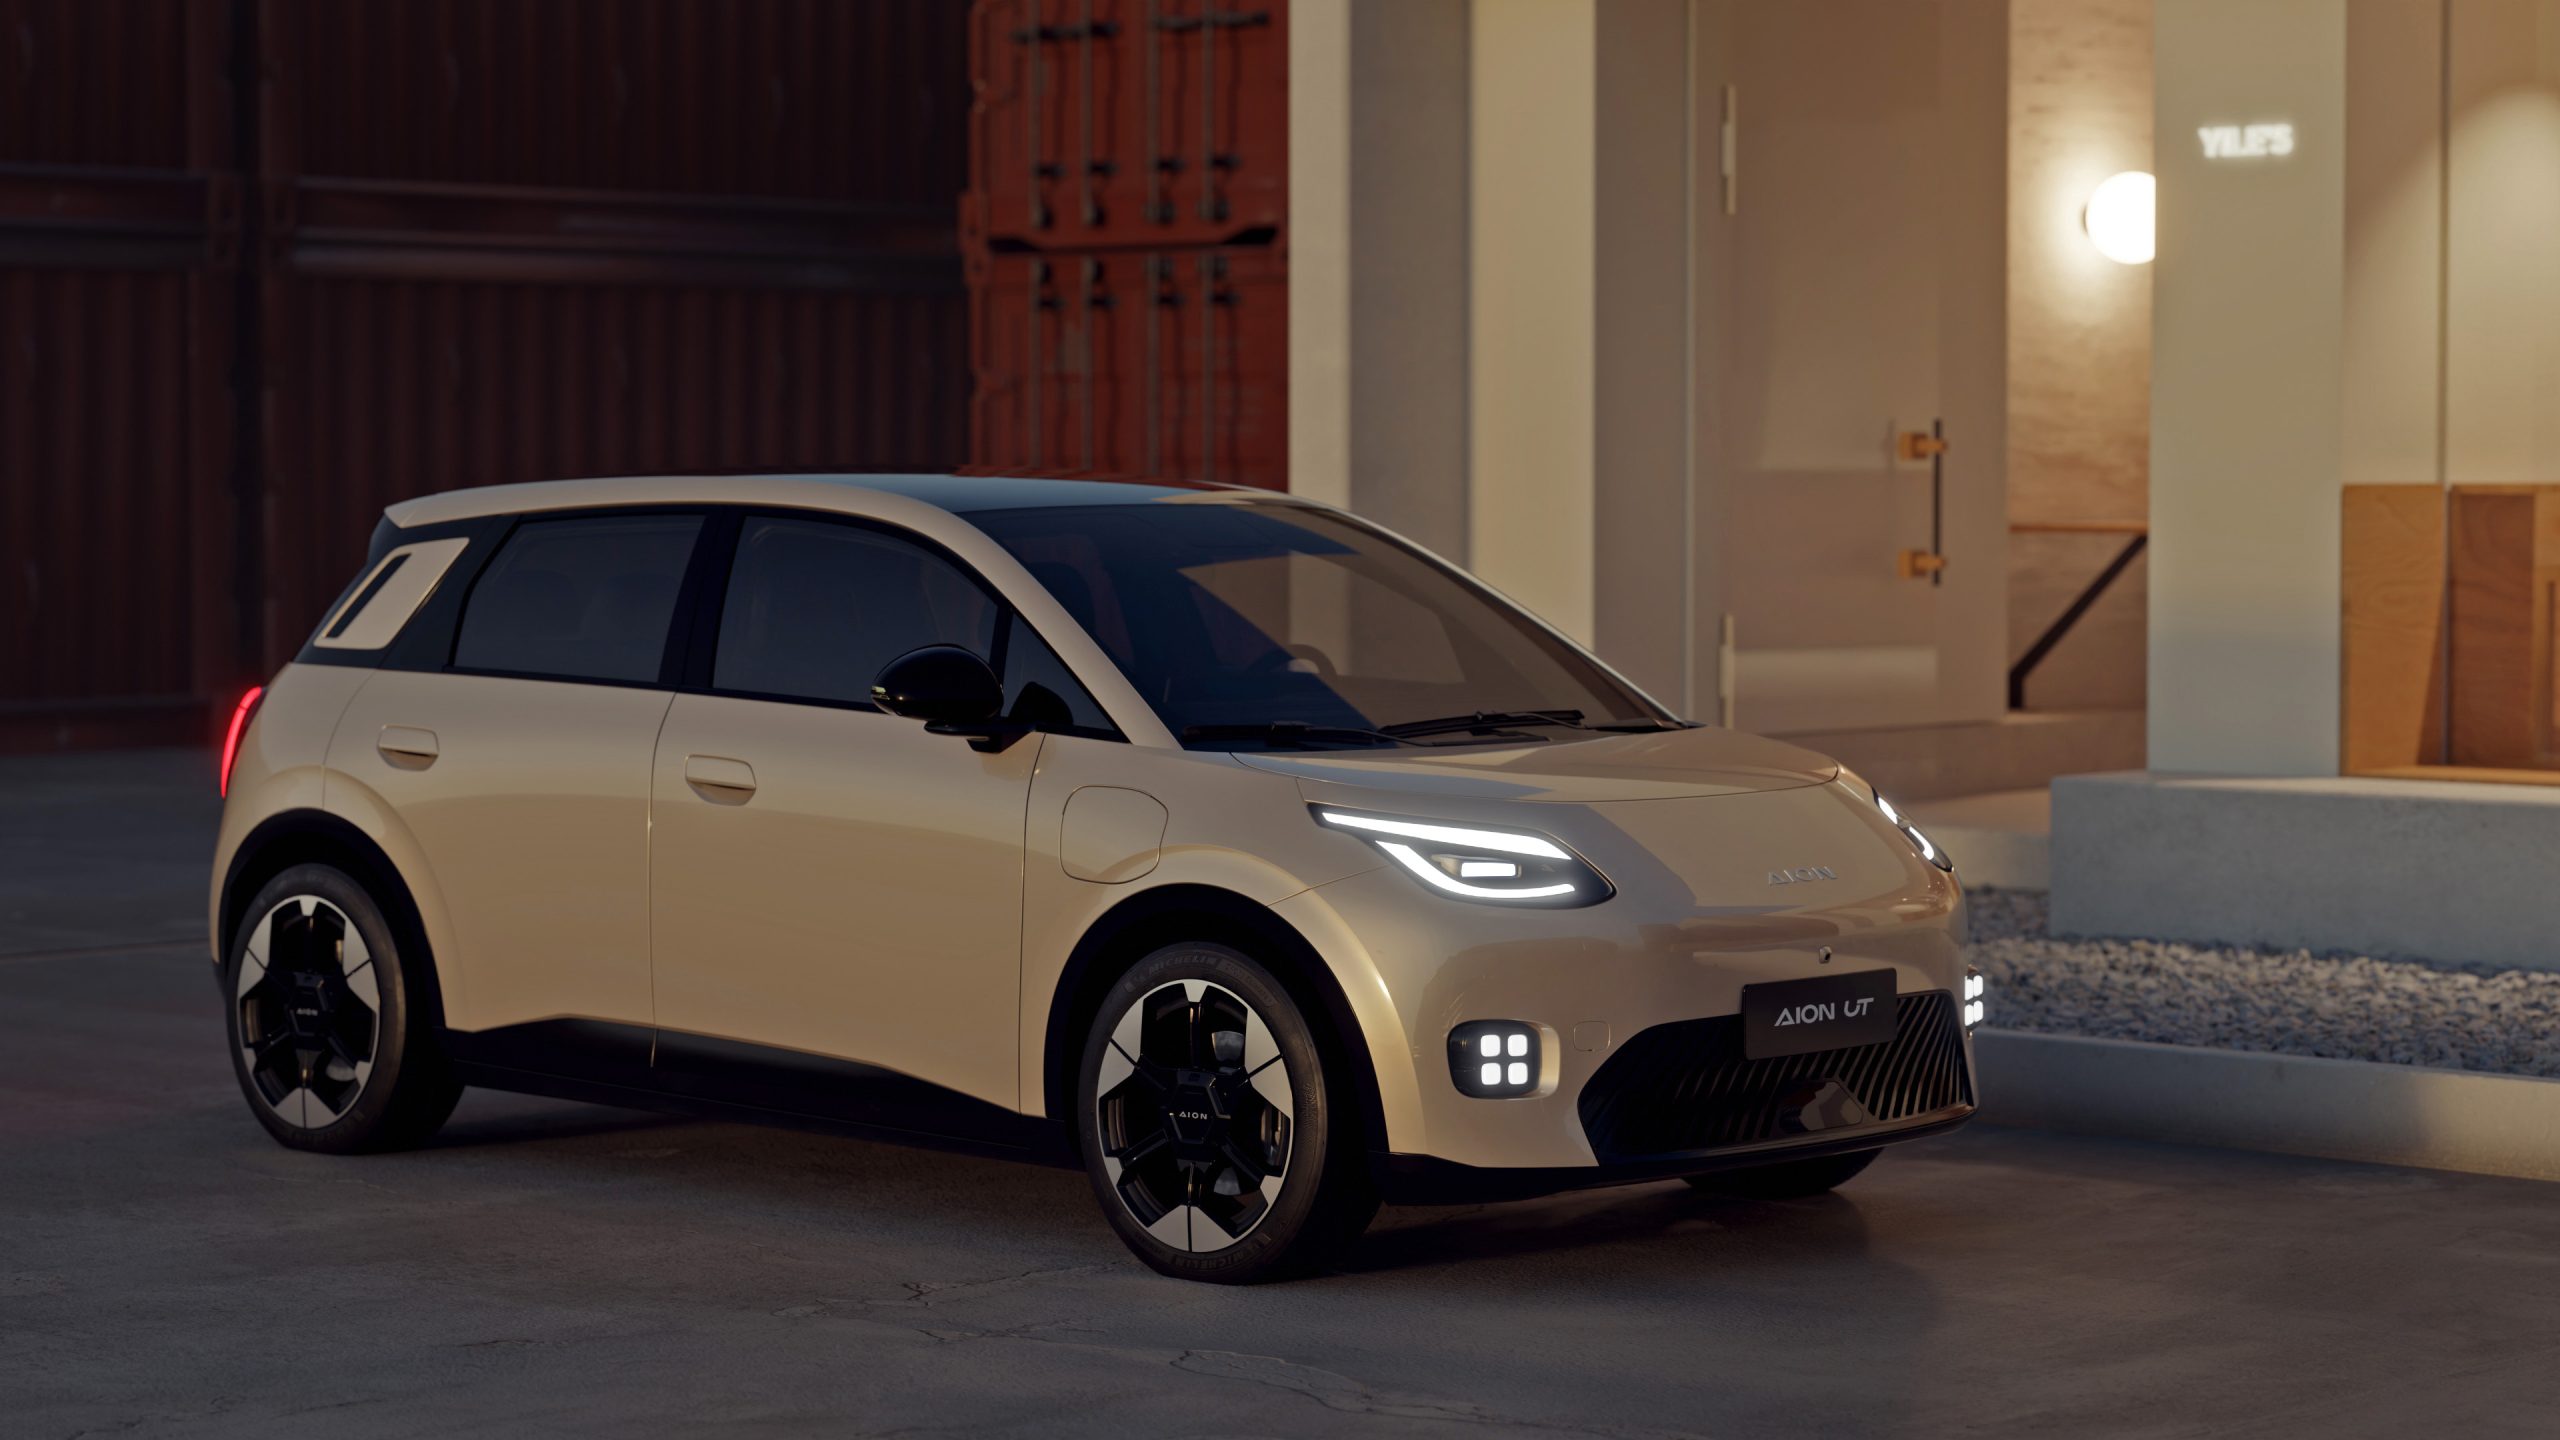
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.