





China’s Punishment for People With Bad Debts: No Fast Trains or Nice Hotels
Beijing’s crackdown on millions of delinquent debtors makes catching up on unpaid bills a slog

 6 min
FOSHAN, China—Qin Huangsheng once imagined a better life in the city when she left her home village to become a factory worker at age 16.
Now, in her early 40s, she has $40,000 in personal debt and a base salary of $400 a month. Debt collectors are hounding her. She is blocked from buying tickets on China’s high-speed rail, just one of the penalties the government is increasingly imposing on people who don’t pay their bills.
On the ageing slow trains she is left to ride, Qin sometimes looks at the other passengers and thinks: “I wonder if they’re all bad debtors like me.”
People across China are being weighed down by their debts and a system that penalises them for not paying the money back. Beijing is cracking down on delinquent debtors by seizing their salaries or restricting them from getting government jobs, as well as curbing their access to high-speed trains and air travel. Many are forbidden from buying expensive insurance policies and told they aren’t allowed to go on vacation or stay in nice hotels. Authorities can detain them if they don’t comply.
The number of people on a publicly available government delinquency blacklist has jumped by nearly 50% since late 2019 to 8.3 million today. Courts can put people on the blacklist when they don’t fulfil judgments against them to pay money back or are deemed to be not cooperating with legal proceedings.
Unlike in the U.S., China doesn’t allow most people—including those who had a run of bad luck—to declare bankruptcy to write off bad debts and move on with their lives, a policy some Chinese scholars are criticising as unfair.
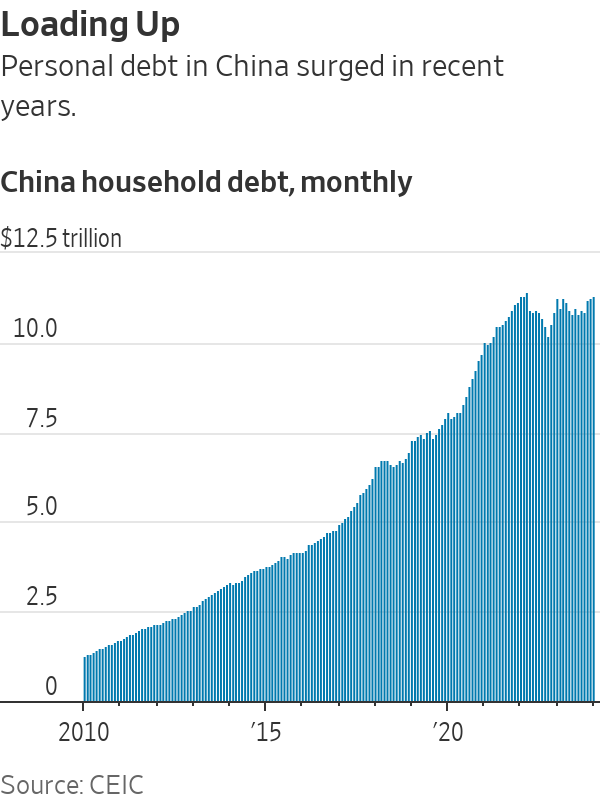
Household debt has surged by 50% in the past five years to around $11 trillion today. While that is lower than the $17.5 trillion Americans owe, it is a huge sum in a country where people earn far less.
With home prices falling, deflation risks becoming entrenched and unemployment a persistent challenge , Chinese leaders are eager to get people spending more. But each additional dollar going to pay for debt is taking away one that could be used to splurge on new clothes or pay for a vacation. The threat of punishment for falling behind on debt is making many families more conservative with their money.
Retail sales of consumer goods in China rose 4.7% year-over-year in the first quarter, the government said Tuesday, lagging behind total economic growth of 5.3%. As many in China curtail spending, the government is giving priority to turbocharging manufacturing and exports, a strategy that is exacerbating trade tensions with the West.
With so many Chinese consumers under financial pressure, Western companies including Apple , Estée Lauder and General Motors have reported weaker sales in China .
Chinese officials didn’t respond to questions about the blacklisting system. The government has said previously it only seeks to target those who have the ability to repay their debts but refuse to do so.
Behind China’s personal-debt surge
China’s long housing boom was a significant cause of the rise in personal debts, because many people had to borrow more to afford homes. Some buyers took on extra debt to buy more properties for investment purposes, sometimes letting them sit empty. Now that the boom is over and prices are falling , many are stuck with debts they can’t handle.
The number of foreclosed homes listed for sale rose 43% in 2023 to roughly 400,000 properties, according to real-estate research firm China Index Academy.
The increase in personal debts is also partly a result of more people using credit cards or tapping personal credit lines to handle expenses as the economy stagnates.
Many economists say a U.S.-style financial crisis is unlikely in China soon. State control of the banking system means the government can absorb losses and inject capital in an emergency. Household debts have also largely plateaued over the past two years, as many people give priority to using extra cash to pay down liabilities rather than shopping or investing in stocks.
Still, the prevalence of large personal debts is a problem for China’s leadership.
“Household debt booms tend to lead to bad macroeconomic outcomes, even in the absence of a financial crisis,” said Amir Sufi, a University of Chicago economist. China has no simple fix. “Once the cycle starts, it’s usually one in which it’s painful, long and difficult to predict when it will end,” Sufi said.
A tough system for borrowers
China has tried for years to lift personal spending to ease its economy’s traditional reliance on infrastructure and real-estate growth. Its banks issued tens of millions of new credit cards each year, with outstanding balances jumping 50% between 2018 and 2023 to well over $1 trillion. Private technology apps such as Alipay and WeChat also started helping consumers secure loans as their digital payment systems soared in popularity.
But when debts go unpaid, a person’s income can be seized by the state to cover their liabilities, leaving debtors with a small allowance to scrape by.
A 38-year-old man petitioned courts in the southern city of Guangzhou to raise his monthly allowance to 12,000 yuan, equivalent to around $1,600, from 9,500 yuan to help pay for a newborn child. Judges denied his request late last year, and instead concluded that his allowance should be cut by nearly 40% because he was already getting too much, court records show.
A black market has emerged to serve people on the blacklist. In one case, Shanghai authorities busted a ring of scalpers who were booking high-speed rail tickets on behalf of debtors who were barred from doing so themselves. In early 2021, authorities tracked down a debtor who had been using the service and took him into custody, according to a local court.
The current system gives priority to protecting creditors—often powerful, state-owned institutions—at the expense of helping struggling individuals. Scholars who study the issue say China urgently needs a nationwide personal-bankruptcy system to achieve leader Xi Jinping’s goal of making the country more equitable , by forcing creditors and debtors to share the costs of soured loans.
“A personal-bankruptcy system is a mechanism for the redistribution of wealth,” Li Shuguang, a scholar who has advised the government on bankruptcy policy, wrote in a Chinese magazine commentary online last summer.
Movement on the issue has been stymied in part by opponents who believe such a system would only encourage more people to shirk their debts.
One woman’s saga
For Qin, the former factory worker, easy access to credit backfired badly.
As a 16-year-old in 1999, Qin boarded an overnight bus from her home in rural southern China to the grimy manufacturing hub of Dongguan, north of Hong Kong.
Her parents, who are farmers, couldn’t afford a payment of less than $15 needed for her to take a high-school entrance exam. She vowed to make it on her own, and found work in factories producing slippers and golden jewellery.
A few years later, Qin secured her first credit card. With it, she bought a computer to teach herself to type so she could land a better job.
When the bill was paid, Qin said she tried to cancel the card. “Keep it for an emergency,” the bank clerk told her.
Qin’s career flourished and she eventually moved to the metropolis of Guangzhou. By 2010, she said, she was managing bidding for a company that supplied fire-safety equipment to real-estate projects. Her nest egg steadily grew from the lucrative commissions she earned in the property boom.
When the property sector slowed, she jumped industries. An acquaintance had been involved in a startup that was developing software to help small-business owners collect WeChat data to generate more foot traffic and aid marketing efforts.
Qin said she invested the equivalent of around $150,000 of her savings into the venture.
The startup burned through her initial investment as it tried to get the software up and running. Qin said she then agreed to start putting some of its expenses, including office supplies, rent and employee salaries, on her credit cards, and to tap personal credit lines she had obtained via WeChat and Alipay.
A roadshow by the company was warmly received, she said. But its prospects dimmed after the Covid pandemic hit.
The company’s struggles left Qin with the equivalent of tens of thousands of dollars of debt. Phone calls from debt collectors have become a daily occurrence.
With no option of bankruptcy, Qin concluded that a new job was her only way out of trouble.
“As long as I’m still living and have a life, I can work hard to earn the money back,” she said.
That path has faced unexpected difficulties. In 2021, while preparing for a business trip to Shanghai, more than 700 miles northeast of Guangzhou, Qin realized that she had lost her access to high-speed rail, where a government I.D. is required to buy a ticket. She took the slow train—and later quit that job in part because the travel restrictions were making it impossible.
Local officials didn’t respond to questions about Qin’s case and The Wall Street Journal wasn’t able to verify some details of her account.
Today, Qin is working in a shop in Foshan, south of Guangzhou, selling traditional Chinese medicines. With a base salary of about $400 a month, she has found it tough to put a dent in her debts, but said she has managed to pay back two of her credit cards so far, with about $40,000 still to go.
Qin is trying to stay optimistic, hoping that medicine will be in high demand as China’s population ages, opening the door to bonuses and potentially even running her own shop. Still, she has had to get creative to earn the cash to pay her debts.
Her current role requires Qin to collect payments from customers using a digital wallet on WeChat. But she said that function on her account has been frozen several times since 2022, leaving Qin to seek help from her family.
She decided not to tell her parents about the full scale of her troubles, however.
If they knew the truth, Qin said, they “wouldn’t be able to sleep.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Once a sleepy surf town, Noosa has become Australia’s prestige property hotspot, where multi-million dollar knockdowns, architectural showpieces and record-setting sales are the new normal.
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.


