China’s Small Businesses Are Hit Hard as Economic Recovery Falters
Beijing pushes banks to extend loans to small businesses, with limited success

 5 min

China’s small businesses are cutting staff, struggling to pay off debt and nervous about the future. Their plight paints a grim picture of the country’s flagging recovery.
The country’s small and medium-size enterprises are crucial to the economy; they employed around 233 million people by the end of 2018, which was the last time this data was made public. But official data, recent disclosures from lenders and interviews with small-business owners show that many of these companies are suffering.
“The biggest problem for small and micro enterprises now is survival,” said Ji Shaofeng, the founder of a micro loan trade association based in China’s eastern Jiangsu province.
The struggles of China’s small businesses make clear how far the country has to go before it fully recovers from a series of lockdowns, which were part of Beijing’s strict response to the coronavirus.
When the government finally brought an end to its strict zero-Covid policy late last year, many economists expected a strong recovery. It hasn’t arrived. Consumer spending, factory orders and exports are among many indicators showing signs that the recovery is losing steam.
A recent survey of manufacturing purchasing managers in China showed a second consecutive month of contraction for small companies. China’s small-enterprise purchasing managers index is now at 47.9; a reading below 50 shows business activity is slowing.
Scott Yang, a wine and tea seller in Wenzhou, a city in China’s wealthy Zhejiang province, said many local business owners he knows are laying off employees and trying to cut costs, in response to a drop in factory orders.
Small enterprises started to add jobs at the end of the first quarter, when there was still some optimism about a recovery. But a PMI subindex showed employment at small enterprises was 48.7 in May, meaning these companies are either cutting staff or not replacing those who leave.

Huang Yiwen, who sells furniture online in Foshan, in southern China’s Guangdong province, said his business has been hurt by the weak property market, since new-home buyers are a reliable source of demand for furniture makers. Annual home sales fell to a six-year low in 2022, after a slump in the property sector that also led to debt defaults by some of China’s largest developers.
“It’s so hard to sell,” said Huang, regarding furniture.
Less than 40% of small and medium-size enterprises are operating at full capacity, which means producing all of the goods they can, according to the latest survey conducted by the China Association of Small and Medium Enterprises, which sends questionnaires to 3,000 SMEs in the country every month.
Economists warn that the problems facing small businesses can’t be isolated from the wider economy. Because small businesses are such a major source of employment, particularly in large cities, their struggles reflect—and could worsen—wider economic strains.
“If SMEs do not recover, it will be difficult for urban areas to create enough employment and income, which will have a significant impact on low- and middle-income families,” said Dan Wang, chief economist of Hang Seng Bank (China).
Chinese government officials are becoming uneasy about the economy and are planning a series of moves to stimulate growth, The Wall Street Journal recently reported. That could include billions of dollars of infrastructure spending and a loosening of rules in the property sector.
So far, Beijing’s attempts to prop up small businesses have focused mainly on making it easier for them to get funding. That has had limited success.

Since early 2020, Chinese regulators have pushed banks and other financial institutions to extend loans to small businesses that were hurt by the pandemic. In some parts of the country, local divisions of China’s central bank have sought to help small businesses by establishing teams to answer funding-related questions, as well as visiting factories and farms to assess their needs. The government has provided other targeted-relief measures such as tax exemptions and temporary rent reductions.
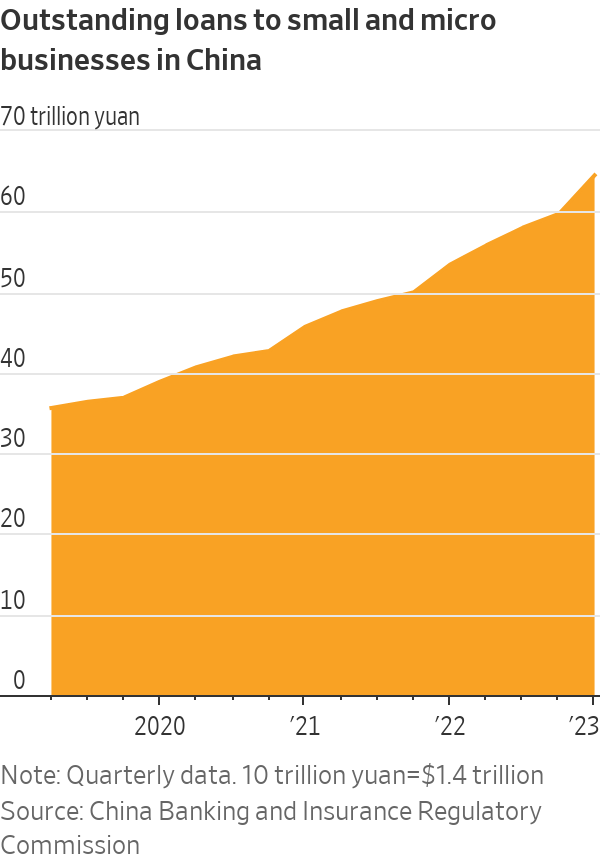
The total outstanding balance of loans to small and micro enterprises has been climbing, reaching the equivalent of $9 trillion at the end of March, according to data from China’s banking regulator.
Many small businesses in China don’t want to secure new financing unless it helps them clear previous debts. Yang, the wine seller, said that while financing is relatively cheap and easy to get, most local businesses he knows are borrowing only to stay afloat and not to expand.
Lufax, a Chinese internet-lending platform that caters mostly to small-business owners, said last month that about 5.7% of the total loans it facilitated were more than 30 days past due at the end of March. Its loan-delinquency rates, which are higher for unsecured loans, have risen for six consecutive quarters.
MYbank, an internet lender that serves small businesses, said in its latest annual report that the balance of its loans that were more than 30 days past due more than doubled last year. The company, an affiliate of the Chinese fintech giant Ant Group, said the impact of the pandemic and weak consumption last year caused many small- and micro-business owners to face continuous pressure.
Many commercial banks have given borrowers more time to repay their loans, extending their forbearance for small businesses to this year. Small businesses whose loans were due in the fourth quarter of 2022 will have until the end of this month to repay, according to a notice from the central bank and a group of regulators.
Chinese banks have allowed some small businesses to roll over their loans, but if these small businesses are unable to repay in the future, they will eventually have to be recognized as bad loans, said Jay Guo, a former banker and current dean at the Ningbo China Institute for Supply Chain Innovation.
“It only makes sense to extend loans if the economy rebounds and SMEs are able to sell their goods,” said Guo.
Ji, of the micro loan trade association, said that while some sectors such as tourism and catering have rebounded in the past few months, small businesses in manufacturing, trade and other industries are still under pressure as demand remains well below where it used to be.
Small businesses are falling victim to a vicious cycle that is affecting the wider economy, said Xiangrong Yu, chief China economist at Citigroup. The poor performance of some private companies is leading to a loss of confidence, and that low confidence is making it hard for those companies to do better, he said.
“Lack of confidence is both a symptom of the problem and the root cause of the problem,” said Yu.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
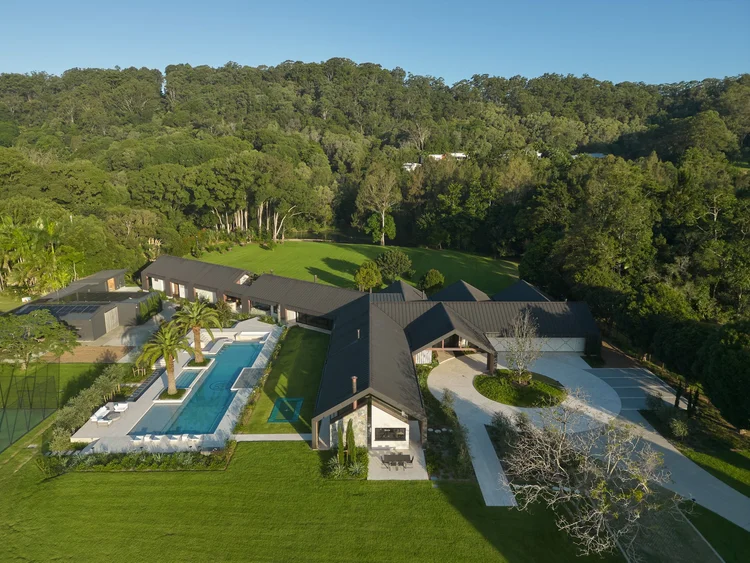
Margot Robbie may have travelled from a Queensland farm to the highest reaches of Hollywood, but a reported $28 million property deal suggests the Gold Coast has never lost its hold on her. The Australian actor and producer is believed to be the mystery buyer of Redwood, a seven-acre Currumbin Valley estate transformed into the …
Continue reading “Margot Robbie Reportedly Behind $28 Million Currumbin Valley Homecoming”

From citrus oils to warming spices, the classic G&T is being reimagined at home as a more thoughtful, seasonal ritual for modern entertaining.