Chinese Leaders Vow to Step Up Support for Flagging Economy
Pledges on government spending and monetary support come as data points to slowing growth

 4 min
Chinese leaders vowed to increase government spending and monetary support for the economy at an annual gathering, signalling they plan to stick with a measured approach to stimulus despite calls for bolder action.
The Central Economic Work Conference, which ended Tuesday, capped a bruising year for the country’s economy, which has struggled with a drawn-out housing crunch and weak consumption.
The trouble shows no sign of abating. After a pickup in the third quarter, data in recent weeks has pointed to slowing growth again as exports struggle, activity in the services sector slows and deflation deepens.
Still, Chinese leaders offered few specifics Tuesday on how they intend to reignite consumer and business confidence and reinvigorate growth.
Chinese leader Xi Jinping presided over the two-day meeting, where leaders urged officials to increase fiscal stimulus and help expand domestic demand, according to Chinese state media. They also acknowledged economic challenges, including “excess capacity in certain industries and weak sentiment in the society,” according to a readout of the meeting.
Chinese leaders also called for strengthening the resilience of industrial supply chains and accelerating the development of artificial intelligence, as well as other strategic industries such as aerospace and biotechnology.
The closed-door meeting, which is typically held in December each year to map out plans for economic policy-making, sets out the leadership’s growth ambitions for the following year, though the detailed targets won’t be released until March, during the National People’s Congress.
Though the overall tone of the conference was pro-growth, “it is still not a call for massive stimulus,” economists at Société Générale said in a note to clients after the readout was published. Instead, officials are emphasising the need to stabilise the economy and stem risks to growth, they said.
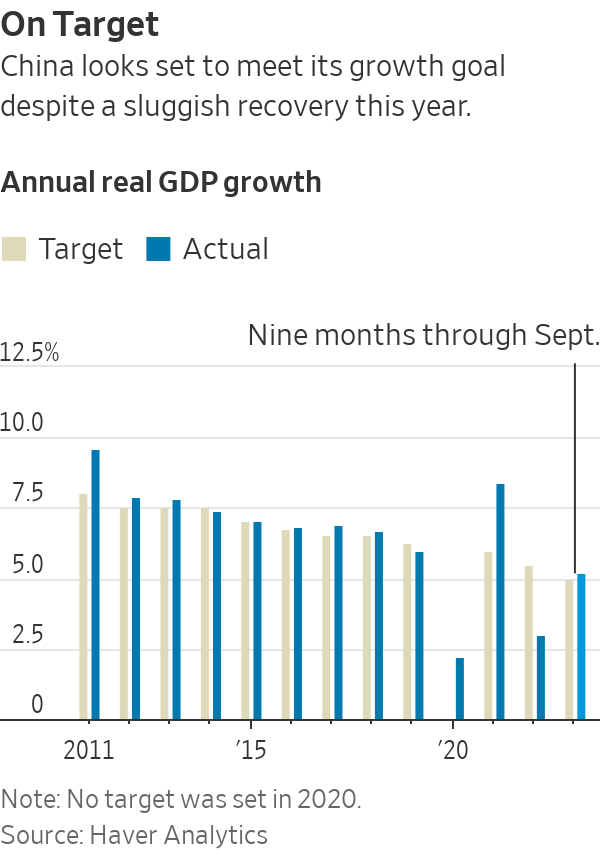
Many economists expect Beijing to anchor its growth target at around 5% in 2024, taking their cue from a meeting last week of the Communist Party’s Politburo, its body of top leaders. Policy makers emphasised the importance of economic progress, saying the country needed to “pursue stability through growth.”
This year’s target was also set at around 5%. Despite its difficulties, the economy looks set to hit that goal this year, but economists say maintaining that pace will be tough without bigger measures to stimulate the economy.
Beijing has taken some measures this year including interest rate cuts and channeling cheaper loans to firms to arrest the downturn but has so far failed to reverse a broad-based loss of confidence.
China’s difficult year contrasts with surprising resilience in the U.S., where buoyant consumer and government spending have kept the economy motoring despite aggressive increases in interest rates by the Federal Reserve. The latest data on jobs and inflation has stoked optimism that the U.S. will avoid recession and instead enjoy a “soft landing,” in which price growth slows to target without a steep rise in unemployment. That marks a reversal in expectations from earlier in the year when China was expected to easily outpace a cooling U.S. economy.
And there are fresh signs of trouble for China.
Business surveys showed factory activity slid deeper into contraction in November as domestic and foreign orders dried up, while activity in the services sector shrank for the first time this year as consumers cut back spending.
Exports rose just 0.5% on the year last month after shrinking for six months, highlighting the drag from slowing growth in the U.S. and Europe.
Weak domestic spending and bloated industrial capacity caused consumer prices in China to fall in November for the second straight month, deepening a bout of deflation that economists say could prove hard to shake if the economy doesn’t pick up soon.
China’s slow-motion property crunch shows few signs of abating. Some developers have defaulted on their debts and construction has stalled on millions of homes. Home prices fell in October and new investment in the sector is shrinking.
A central question for investors and economists is whether Beijing will experiment with novel stimulus approaches to shore up battered confidence among households and businesses.
At the meeting, Chinese leaders vowed to expand consumption and raise income for both urban and rural residents but offered little sign that they may pivot to giving cash handouts to households, despite repeated calls from policy advisers and economists to do so.
Instead, the government is seen as more likely to step up efforts to resolve the crisis in the property market, which remains a major drag on overall growth.
Chinese leaders called for equal treatment for developers to meet their financing needs—a likely reference to the perception that banks favour state-backed developers over private ones. They also urged accelerating the construction of government-subsidised affordable housing and urban village renovation projects.
Still, the meeting didn’t spell out a plan to help cash-strapped developers finish tens of millions of uncompleted apartments, a crucial step that economists believe will help restore household’s confidence in the government.
While officials aren’t expected to disclose a growth target until a political gathering next spring, economists and investors are already debating how aggressive Beijing will be with its 2024 goal.
Economists from J.P. Morgan predicted that policy makers will likely maintain a goal of around 5%, to signal a renewed focus on the economy. Robin Xing, chief China economist at Morgan Stanley, said he expects Beijing to set a target of 4.5% to 5% and pursue a stronger fiscal stimulus.
Others believe Beijing will stick to a more conservative target because of the headwinds facing the economy. Ting Lu, chief China economist at Nomura, said he expects China to aim for around 4.5%.
“I still think the Chinese government is quite rational,” said Lu, who cautioned that the economy hasn’t bottomed out and the actual growth rate could slip to 4% in 2024 from Nomura’s 5.2% forecast for 2023.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

From Tokyo backstreets to quiet coastal towns and off-grid cabins, top executives reveal where they holiday and why stepping away makes the grind worthwhile.
Porsche has revealed a one-off 911 GT2 RS that brings the extraordinary silhouette of its 935/78 “Moby Dick” racing car onto the road. Created by Porsche Sonderwunsch with Manthey, the commission began with a near-new GT2 RS. The owner requested greater performance, a Slantnose profile and a rear wing influenced by the limited 911 GT3 …
Continue reading “Porsche Builds a Road-Going “Moby Dick” From a 911 GT2 RS”