

Christie’s to Offer Two Landscapes by Lucian Freud in London

 3 min

Two landscapes by Lucian Freud previously in the collection of British businessman and philanthropist Simon Sainsbury will be offered next month at Christie’s in London, the auction house announced Friday.
Separately, Sotheby’s released additional highlights of its upcoming Masters Week in New York, including an over 400-year-old Anthony Van Dyke painting, A Sketch for Saint Jerome, that was found in a farm shed in the late 20th century in New York. The auction house expects to bring in more than US$100 million from across nine sales running now until early February.
Christie’s sale of the two Freud landscapes will take place on the evening of Feb. 28 in London. Offered by the same private collector, both paintings were formerly in the collection of Sainsbury, whose family founded Sainsbury’s, the second largest chain of supermarkets in the U.K. Upon his death in 2006 at the age of 76, Sainsbury bequeathed the majority of his art collection, estimated to be worth £100 million at the time, to the National Gallery and the Tate Gallery in London.
One of the paintings, Scillonian Beachscape from 1945-46, will make its first public appearance on the market since 1974 and has a presale estimate of between £3.5 million and £5.5 million (US$4.3 million and US$6.8 million). Depicting a dreamlike coastal scene in lush, sun-drenched color, it was inspired by Freud’s visit to the Isles of Scilly and directly based on his drawing, Untitled, which sold for £138,600 at Christie’s in London last October.

The other, Garden from the Window, depicts the artist’s garden at 138 Kensington Church Street. It was first unveiled at the Tate in London in 2002, and its debut auction at Christie’s is expected to fetch £2.5 million and £3.5 million.
“Lucian Freud, revered as one of the greatest painters of the 20th century, continually returned to the natural world as a source of rich inspiration throughout his career. This lifelong fascination is perfectly encapsulated in these two exquisite paintings which offer viewers insight into both his early and late life,” Tessa Lord, acting head of department of Post-War and contemporary art at Christie’s London, said in a news release.
The National Gallery in London has recently organized a centenary retrospective “Lucian Freud: New Perspectives,” which will move to Thyssen-Bornemisza Museo Nacional in Madrid in February.
Freud’s auction record was set by his painting large interior w11 (after watteau), 1981-83, from the collection of Paul Allen. It sold for US$86.3 million last November at Christie’s in New York.

Meanshile, t Sotheby’s, its first major sale of the year will be its Masters Week in New York, which is expected to bring in more than US$100 million across nine sales that will run through early February.
The sales will be led by 10 Baroque masterpieces from the collection of Mark Fisch, a real estate developer and a trustee of the Metropolitan Museum of Art in New York, and his ex-wife, Rachel Davidson, a former New Jersey judge. The two filed for divorce last year. Highlighting the collection, to be auctioned next Thursday, is a 1609 Rubens masterpiece, Salome Presented with The Severed Head of Saint John the Baptist, with an estimate of between US$25 million and US$35 million.
The sales also include The One, a new format sale featuring one-of-a-kind objects throughout history. This sale will be led by Kobe Bryant’s Lakers jersey with a high estimate of US$7 million, and a Princess Diana’s dress, with a presale estimate between US$80,000 and US$120,000.
A Sketch for Saint Jerome from 1615-18 by Anthony Van Dyck that was discovered in the late 20th century in a farm shed in Kinderhook, N.Y., will be offered in the region of US$2 million and US$3 million. A portion of proceeds from the sale will benefit the Albert B. Roberts Foundation, which supports artists and other creatives.
Roberts, a collector of “lost” pieces, purchased the sketch for US$600. Soon afterwards, the sketch was recognized by art historian Susan J. Barnes as a “surprisingly well preserved” autograph work by Van Dyck, according to Sotheby’s.
He died in August 2021 at the age of 89.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


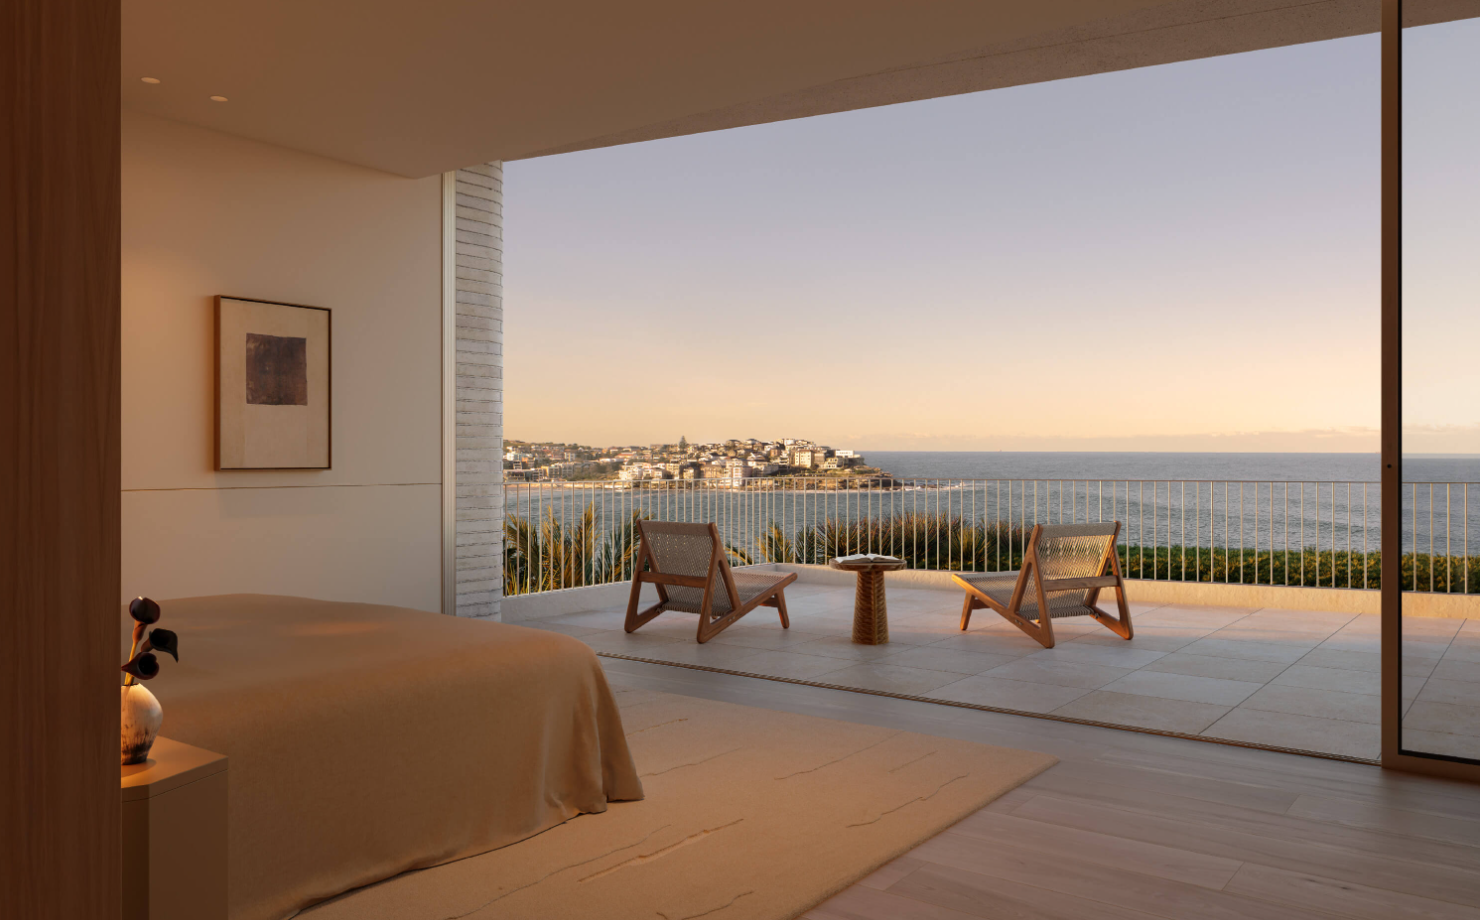
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
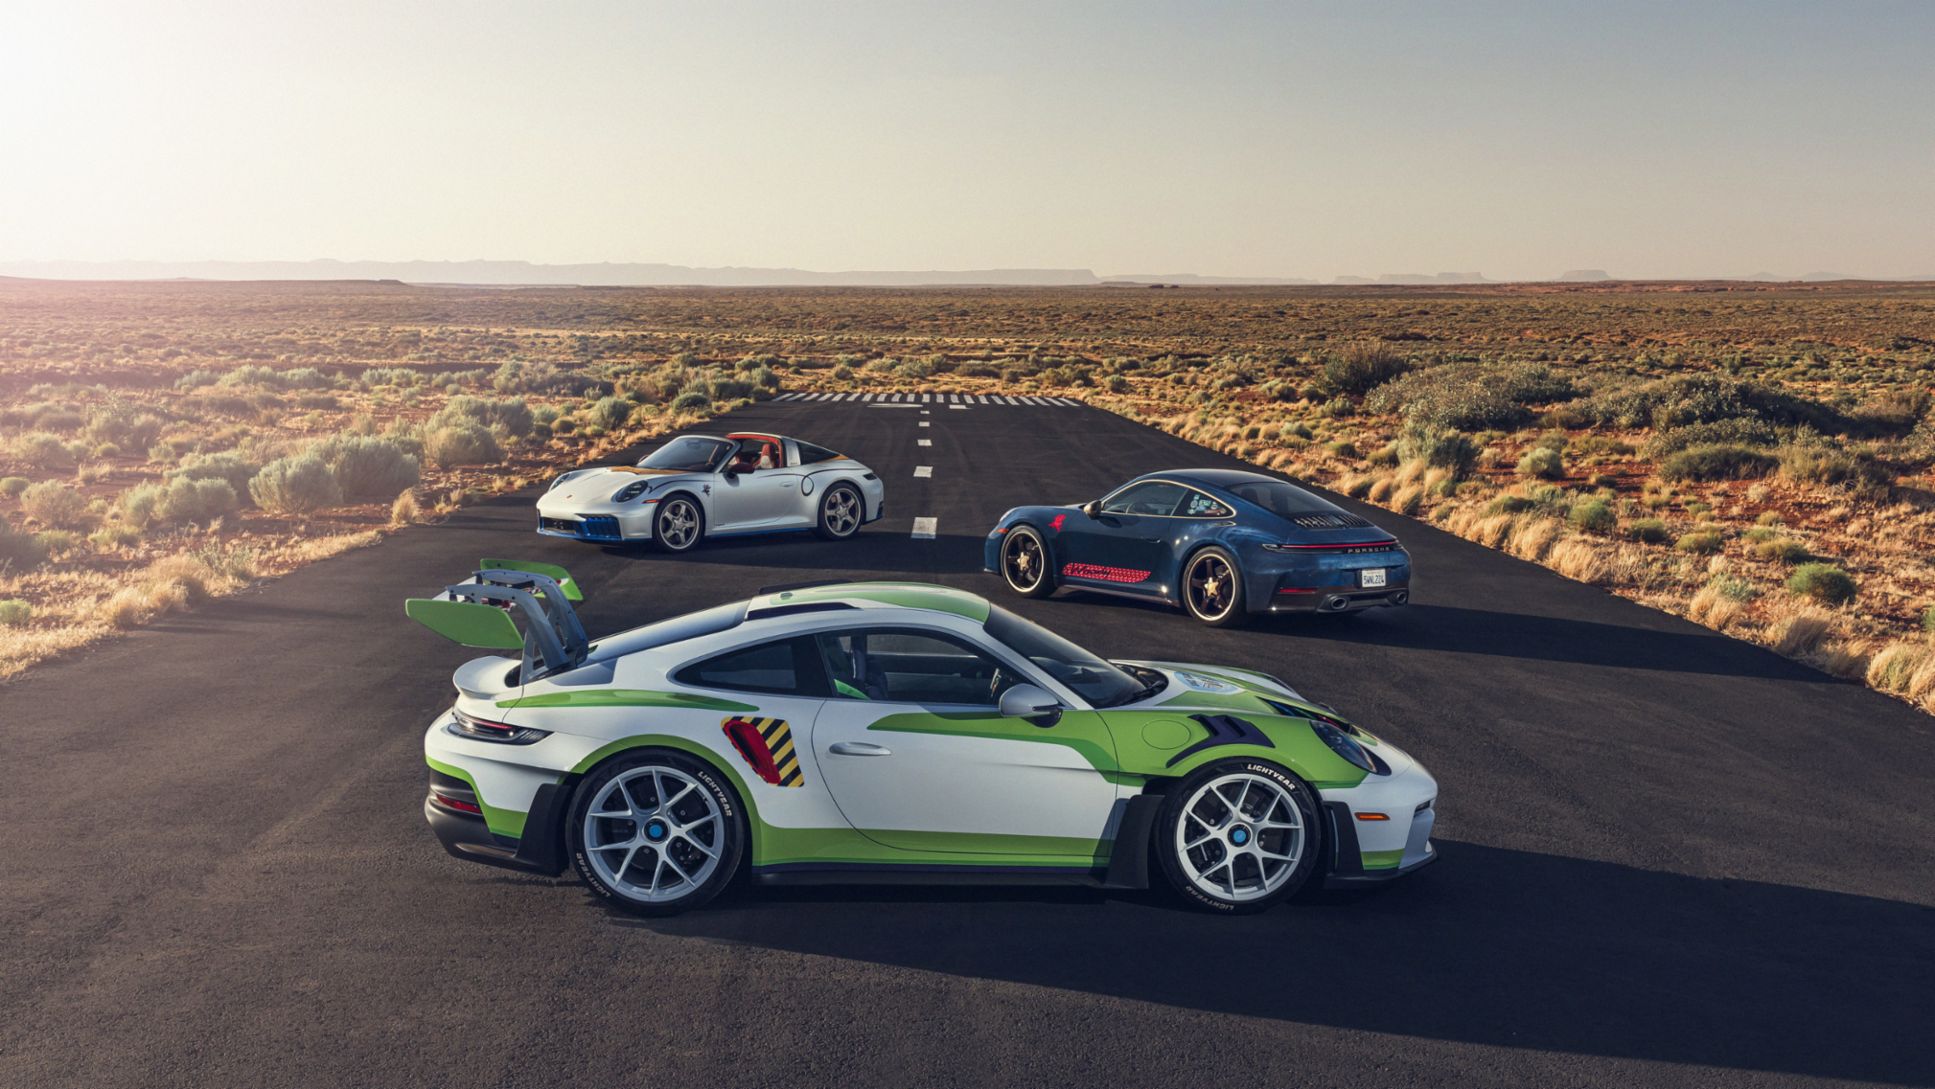
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.

A thoughtful timber-led renovation in Byron Bay has reimagined an existing house as a warm, resort-style family sanctuary grounded in natural materials.
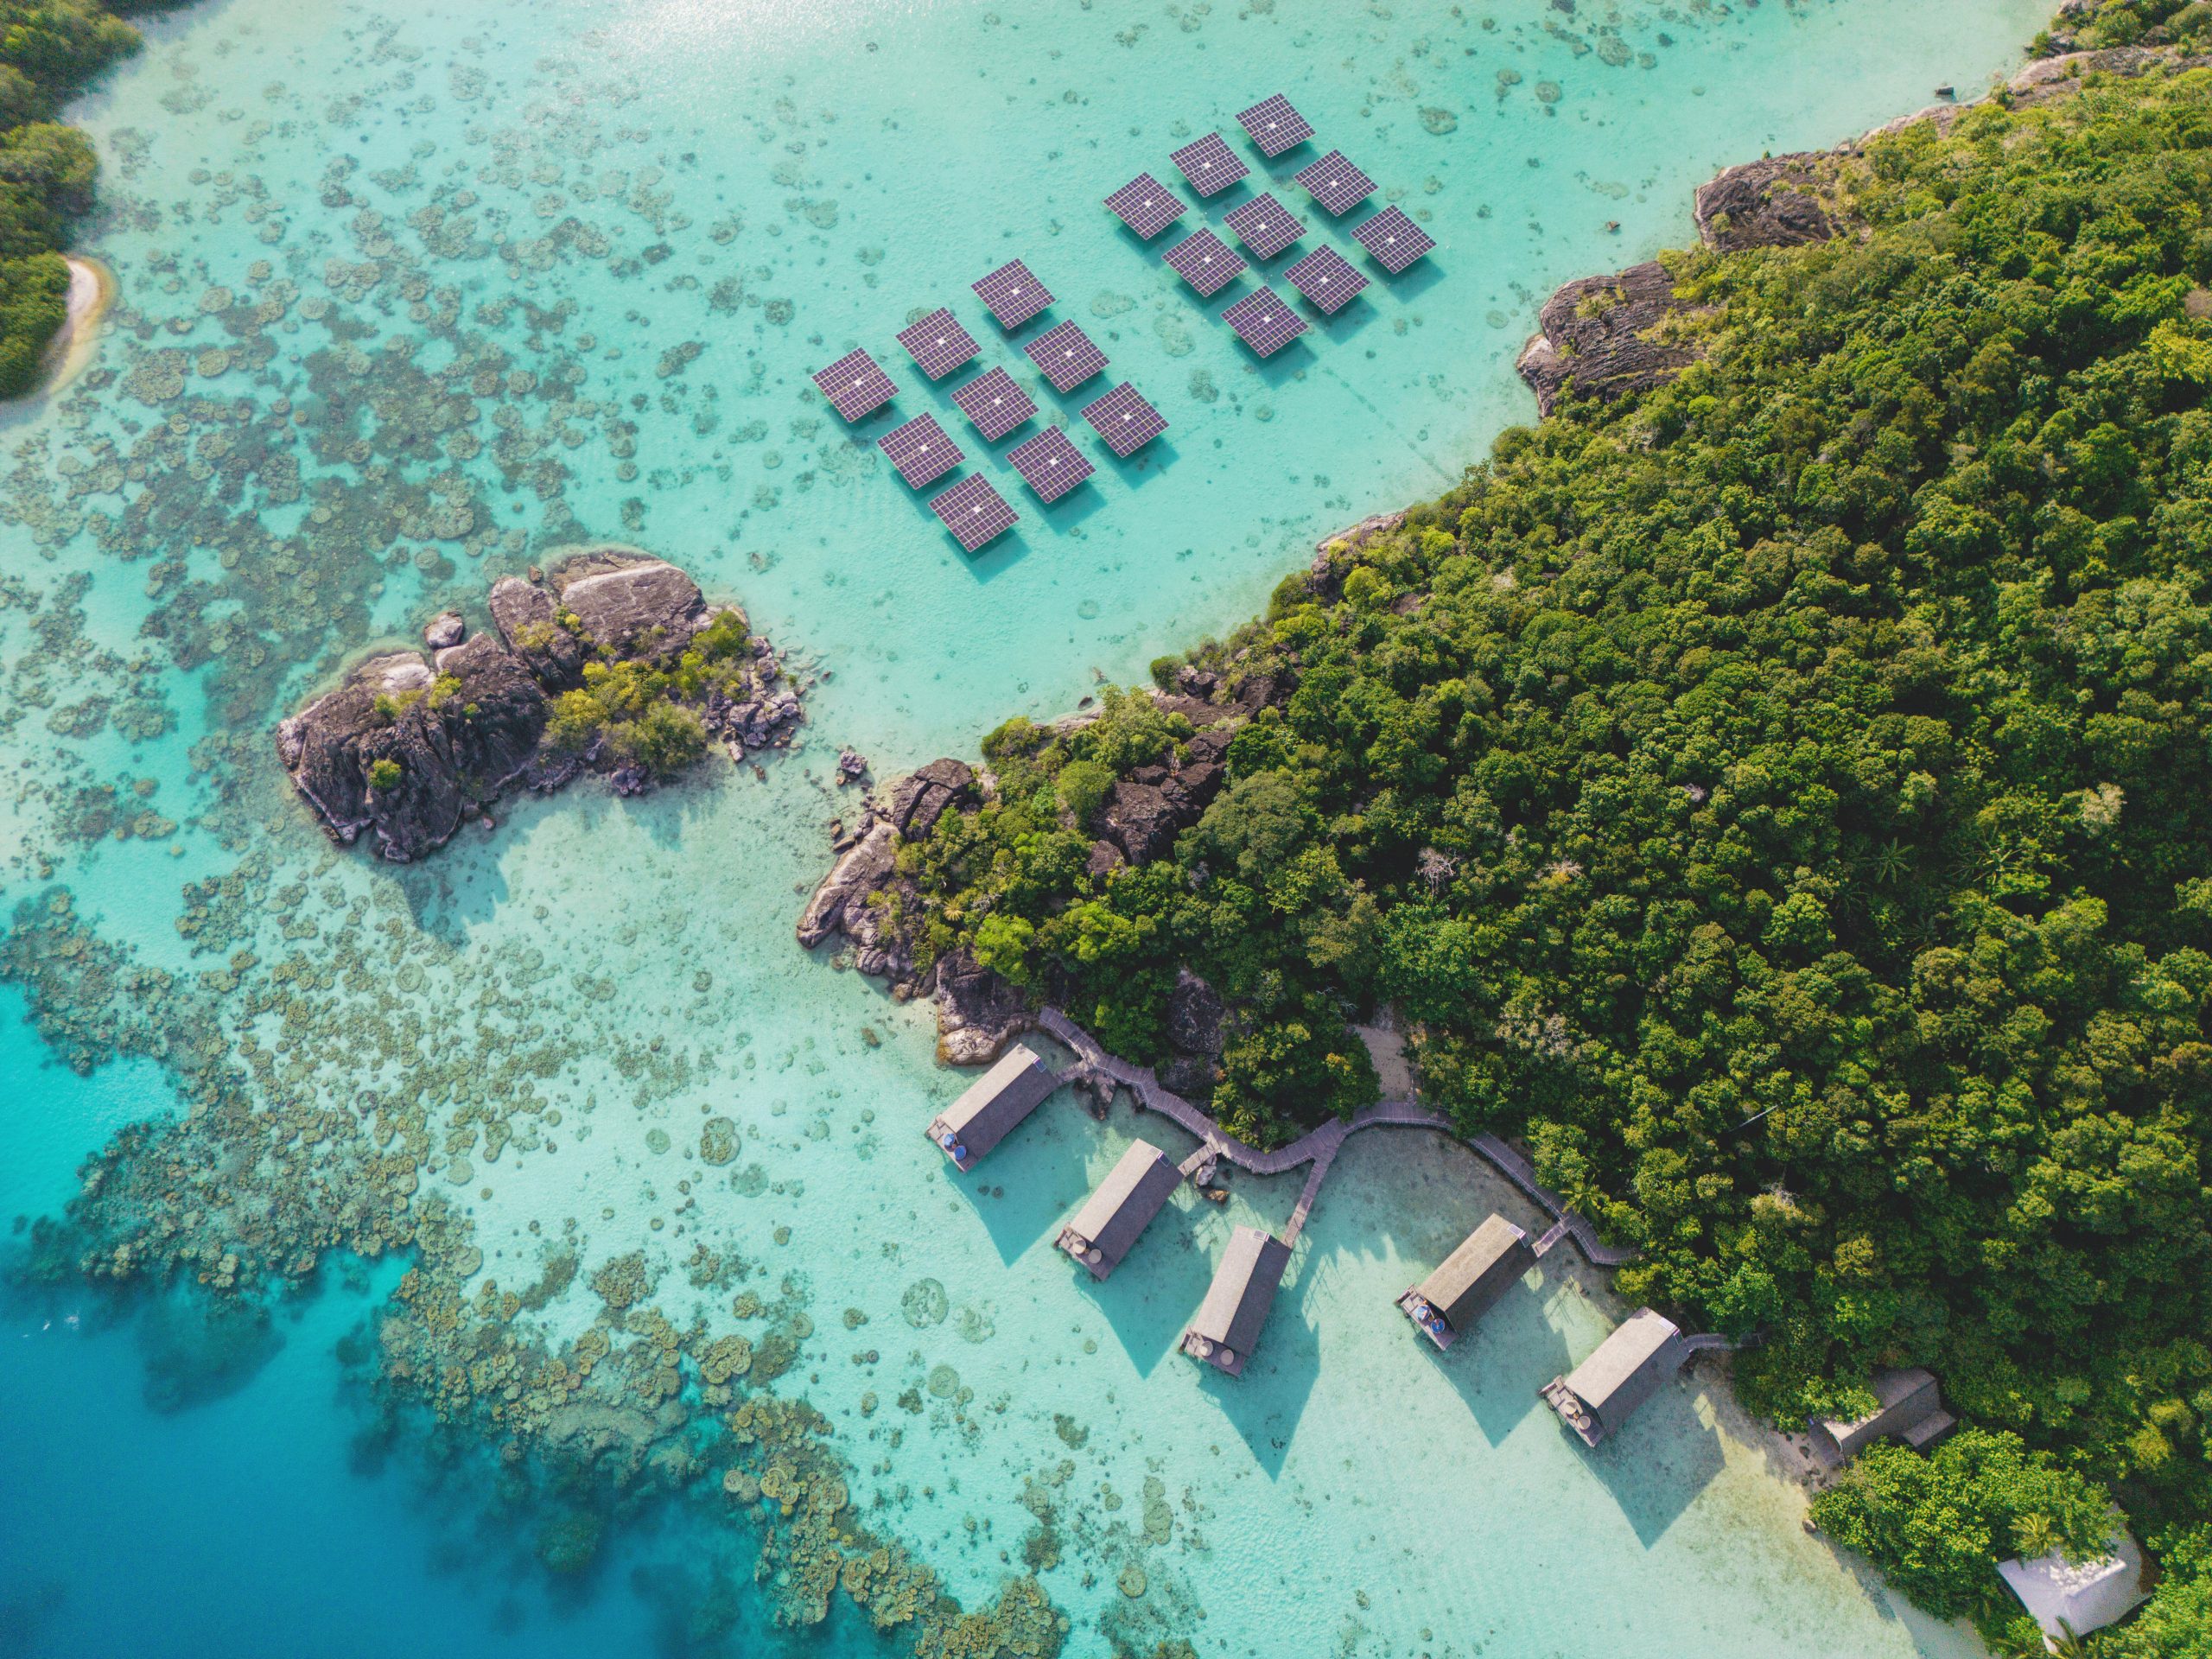
In the remote waters of Indonesia’s Anambas Islands, Bawah Reserve is redefining what it means to blend barefoot luxury with environmental stewardship.