Don’t Count on China to Save the World Economy
Early signs suggest the country’s economic revival will mostly be felt in service industries at home

 6 min
The world is counting on an economic bounceback from China to power global growth and help keep recession at bay. Don’t bank on it.
China’s recovery after years of Covid-19 lockdowns will likely look a lot different from previous ones. And for many parts of the world, economists warn, it could be less potent than governments and businesses hope.
China has historically relied on government stimulus and heavy investment to power itself out of slumps. That mix helped yank the global economy out of the doldrums after the 2008 financial crisis.
This time, China is deeply in debt, its housing market is in distress, and much of the infrastructure the country needs is already built. As a result, its latest revival will be led by consumers, who are casting off almost three years of public-health restrictions and travel bans after the government abruptly dismantled its zero-tolerance policy toward Covid-19.
Data shows that people are again venturing out and shopping in big cities, and there are signs that the worst of China’s Covid outbreak might be behind it. Like their American counterparts, Chinese consumers squirrelled away cash during lockdowns. But consumer confidence remains low. While wealthier Chinese are opening their wallets, many others are choosing to save more than spend.
Early indications suggest the biggest effects of China’s rebound will be felt at home, rather than abroad. Official data, including business surveys, sales and public transit numbers, suggest the strongest growth will come from service industries such as restaurants, bars and travel.
That means that while an accelerating China is good news for fragile global growth, especially as the U.S. and Europe are set to slow, the direct effects of its revival will likely be less pronounced elsewhere than in the stimulus-led expansions of the past.
“China will deliver a powerful economic recovery, but the growth spillover to the rest of the world will be much more muted in this cycle because of the nature of the economic rebound,” said Frederic Neumann, chief Asia economist at HSBC.
The U.S. economy is unlikely to feel much benefit at all, some analysts say, since it has limited exposure to China’s service industries. U.S. growth might even be squeezed if China’s reopening pushes up demand for energy and raises global energy prices, adding to inflationary pressures.
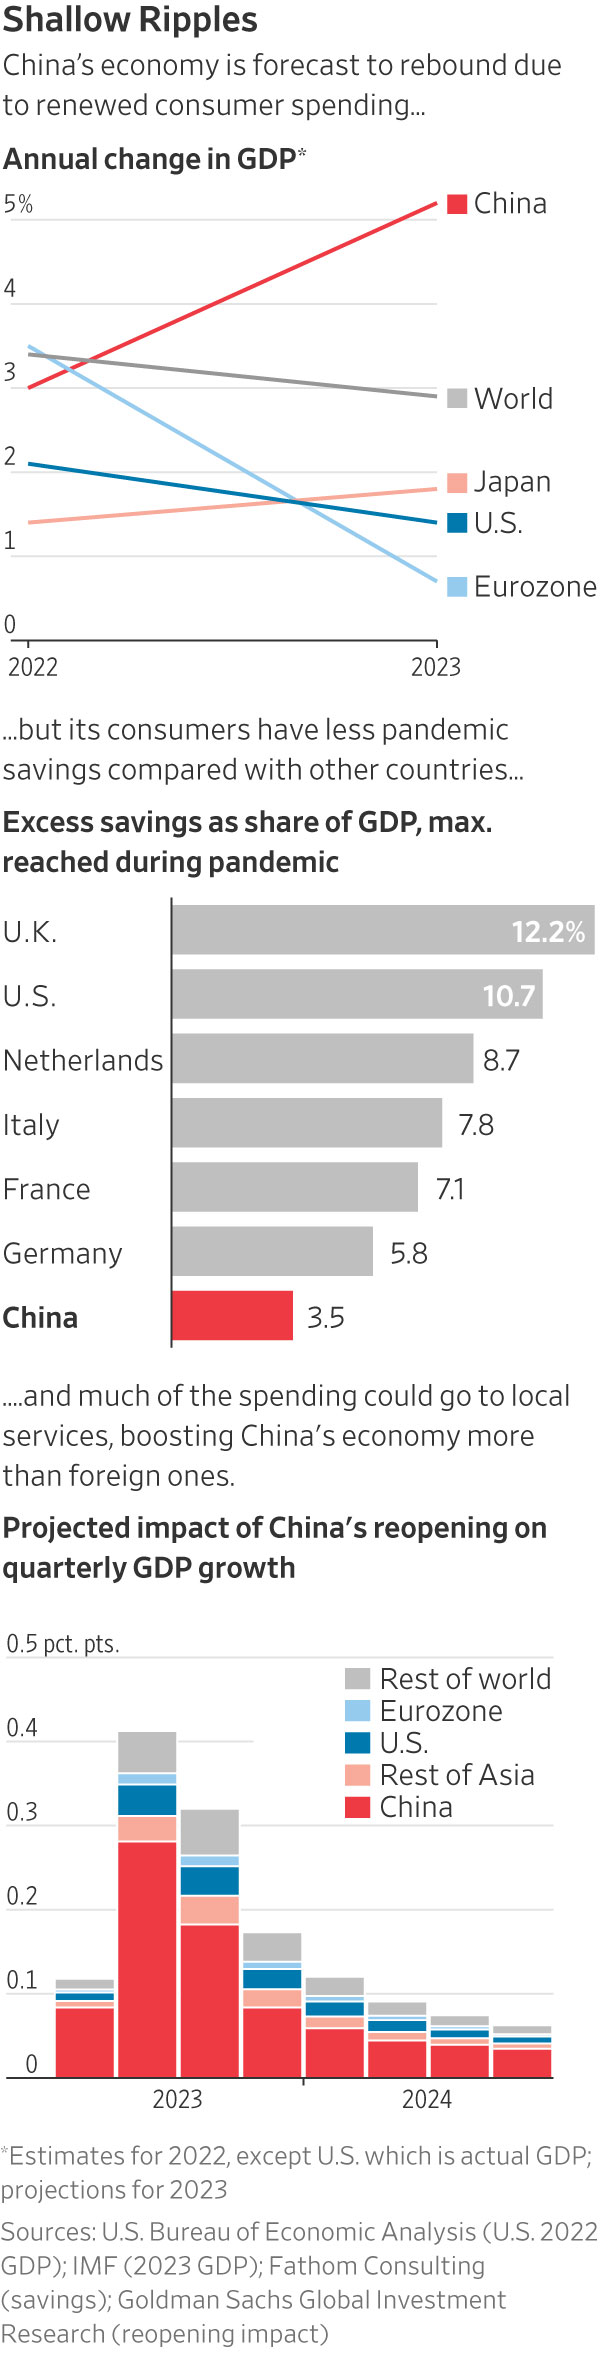
China’s economy is set to expand 5.2% in 2023, according to the International Monetary Fund’s latest forecasts, easily outpacing the 1.4% growth rate expected in the U.S. and 0.7% in Europe’s 20-nation common currency area.
The IMF predicts China will account for around a third of global growth this year, compared with just 10% for the U.S. and Europe combined. That would take China back to the kind of share it had in the five years before the pandemic, IMF data show. In 2022, when the U.S. grew at 2.1%, China’s economy expanded 3%, its second-worst performance since the death of Mao Zedong in 1976. China’s share of global growth sank to 16%.
“It’s so important that China rebounds this year because the U.S. and Europe are expected to slow down sharply,” said Hoe Ee Khor, chief economist at the Asean+3 Macroeconomic Research Office, an economic research organisation that provides policy advice and technical assistance to economies in East and Southeast Asia. “It provides the support that’s missing among those three pillars.”
Wealthier Chinese could help boost the global economy with spending on European luxury goods and vacations in places such as Southeast Asia. Swiss watchmaker Swatch Group AG said in January that based on the rebound in sales it experienced in China immediately after reopening, it expects a record year for revenue, powered by sales in China, Hong Kong and Macau as travel resumes.
Bernard Arnault, chairman and chief executive of luxury goods giant LVMH Moët Hennessy Louis Vuitton SE, told analysts and reporters on Jan. 26 that stores are full in Macau. “The change is quite spectacular,” he said.
“This is a serious bump for everybody,” David Calhoun, chief executive officer of Boeing Inc., said last month on a call with investors, describing China’s reopening as “a major event in aviation.” He said the company is aiming to get idled aircraft back in the air and is hopeful on further deliveries to China, as Chinese carriers will need Boeing’s 737 MAX aircraft to meet rebounding demand for flights.
Other companies are more circumspect. Chinese households received far less in fiscal support from their government during the pandemic than workers in advanced economies, and many consumers remain worried about a weak job market and the continuing real-estate slump.
Colgate-Palmolive Co. Chief Executive Officer Noel Wallace told analysts late last month that despite the euphoria about reopening, sales of the company’s household goods in China remain soft. “China is a big question mark,” he said.
Yum China Holdings Inc., which manages restaurant chains including Kentucky Fried Chicken and Pizza Hut in China, said it saw a bump in sales during China’s recent Lunar New Year holidays but it is wary about the outlook. “While all these happy improvements are happening, we are also cautious that the value for money, the cautious spending is also happening,” Chief Executive Joey Wat said on a Feb. 7 call with analysts.
In previous years of stimulus-fuelled growth, when China plowed money into real estate, infrastructure and factories to turn its economy around, its ravenous demand for commodities and machinery was felt all over the world—among tool makers in Germany, copper producers in Latin America, makers of excavators in Japan and coal producers in Australia.
In 2009, China expanded 9.4% thanks to a $586 billion stimulus package, providing a powerful counterweight to advanced economies hit hard by the global financial crisis.
Economists at Goldman Sachs estimate China’s reopening will add 1 percentage point to global economic growth this year, primarily through higher demand for energy, higher imports and international travel. The biggest beneficiaries are likely to be oil exporters and China’s neighbours in Asia, they said.
Modelling by Oxford Economics implies a smaller boost to global growth. The consulting firm said if Chinese gross domestic product grows 5% this year with the end of Covid restrictions, that would lift global growth to just 1.5%, a gain of 0.2 percentage point compared with their previous forecast.
Goldman Sachs estimates the direct effect of China’s reopening on U.S. growth to be slightly negative, perhaps shaving about 0.04 percentage point off 2023 growth, as the effect of higher oil prices offsets any increase in exports or tourists. The U.S. and other economies less exposed to the reopening might still benefit from indirect effects, though, if China’s revival lifts global trade and business activity overall or contributes to easier financing for households and businesses.
Even if its growth rebounds sharply, underlying issues remain in China’s economy. Local governments are saddled with debt, limiting their ability to finance infrastructure spending. China has taken steps to boost the real-estate industry, such as easing lending curbs on overstretched developers, but such policies aren’t expected to reverse China’s drop in home sales soon because falling prices mean families are still cautious about home purchases, said Tommy Wu, chief China economist at Commerzbank AG. That will limit China’s appetite for commodities such as iron ore, he said.
Other policy goals could weigh on Chinese demand for imports. Beijing is eager to produce more sophisticated capital goods domestically, rather than buy them from Japan and Germany, and has been reining in polluting industries such as steel to meet climate goals.
Steel production fell 2.1% in 2022 from the previous year, and iron ore imports dropped by 1.5%. BHP Group Ltd., the world’s largest miner by market value, said in January that it expects China to be a stabilizing force for commodity demand in 2023. But it isn’t predicting a rebound to pre-pandemic rates of growth, saying Chinese steel output will likely plateau this half-decade after what was possibly the peak in production in 2020.
While domestic flights in China have picked up quickly, it will take some time before flights to Europe and the U.S. begin to approach pre-pandemic levels, said Olivier Ponti, vice president insights at ForwardKeys, a consulting firm that tracks travel industry data.
In January, the number of flights to destinations outside mainland China was about 15% of where they were in 2019. The most popular destinations are relatively nearby, including Macau, Hong Kong, Tokyo and Seoul.
For now, Chinese travellers to Thailand, a popular destination, are mostly businesspeople or affluent independent tourists. Thai officials say they expect a slow uptick of visitors as more flight routes open and group tours resume from Feb. 6, but that it could take years for arrivals to return to the levels they were before Covid struck.
China’s contribution to the global economy will ultimately depend on the durability of Chinese consumption. For now, even though Chinese households accumulated $2.6 trillion in fresh savings last year, less than 30% of the money is available to spend straight away. The rest is socked away in long-term savings accounts. The job market is still weak and the real-estate slump is sapping household wealth.
The consumption recovery will be “shallow and short-lived,” according to Logan Wright, director of China markets research at Rhodium Group, a research firm based in New York. He predicts that after a quick surge in growth around the second quarter, the recovery in consumer spending will quickly lose steam.
—Nick Kostov, Eric Sylvers, Feliz Solomon, Rhiannon Hoyle and Jeffrey Sparshott contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A bold new era for Australian luxury: MAISON de SABRÉ launches The Palais, a flagship handbag eight years in the making.
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.