Emerging-Markets Stocks Have Rarely Been So Hated. It’s Time to Buy
The best returns might require investing in troubled countries and looking past the benchmark index to find some gems

 3 min
The last time emerging markets were doing this badly the term “emerging markets” hadn’t been coined yet.
That spells opportunity, and the greatest spoils might go to those investors who are the boldest and also willing to look past that poorly-defined category. The benchmark for how emerging markets stocks are doing is a widely followed index maintained by MSCI that has returned less than 4% annually in the past five years, compared with nearly 12% for global equities and more than 15% for U.S. stocks.
Dig into any of those broad categories, though, and there are clear leaders and laggards. A whopping 65% of the MSCI All Country World Index’s market value, including nine of its top 10 stocks, were American as of the end of October. The MSCI Emerging Markets Index has been dragged down in large part since 2020 by China, where a housing crisis and a heavy-handed approach to technology firms by leader Xi Jinping have depressed valuations. Alibaba Group and Tencent Holdings were two of the world’s most valuable companies four years ago, before the tech crackdown.
If not for the massive surge of the MSCI index’s Chinese components in September on renewed stimulus hopes, the overall picture for emerging-markets stocks would be even worse. India, in no small part because it isn’t China, has seen huge foreign and domestic investor interest and now has the third largest weighting in the emerging-markets index. But it also is one of the world’s pricier markets .
Emerging markets outperformed developed market stocks in the century’s first decade as commodity prices boomed and the tech and housing bubbles dented the U.S. market. Today, though, they are much cheaper as a multiple of earnings, and not solely because of China.
Just buying an emerging-markets index fund and betting on the performance pendulum swinging back could be a decent strategy. Bolder investors might be able to do better: The most enticing opportunities are where skepticism is highest.

For example, Mexico and the multinational companies that use it as a base to sell products destined for the U.S. are in President-elect Donald Trump ’s crosshairs. Newly-elected leftist President Claudia Sheinbaum also faces violent drug cartels and protests over changes to the country’s judiciary. But the MSCI Mexico Index has gone absolutely nowhere, with a slightly negative return over the past decade and a forward price-to-earnings ratio of around 10 times—less than half that of the U.S. market.
And Mexico is pricey compared with South Africa, Brazil and Turkey, which fetch multiples on the same measure of about 9.8 times, eight times and five times, respectively. All three also face significant domestic problems and leaders who have mismanaged their economies. But even poorly-run countries can have long-term promise, and occasionally some short-term charms: Brazil’s dividend yield, for example, is about 6%, or five times that of the S&P 500 index.
Another way to profit as a savvy emerging-markets investor? By reading what is on the label and then ignoring it. MSCI’s benchmark has had an odd definition of what qualifies that mostly matters to professional money managers.
For example, both South Korea and Taiwan are major emerging markets, but their citizens are wealthier than those of developed Portugal or Greece. With leading high-tech companies like Taiwan Semiconductor Manufacturing Co . and Samsung Electronics , educated workforces and excellent infrastructure, they have more in common with neighbouring Japan, a developed market. MSCI cites market access issues that hold them back. That might still make them attractive places to invest, but the rapid growth a country enjoys by becoming modern, educated and wealthy—the sort of thing that has people so excited about India’s long-term potential—are now behind them.
Getting booted from the index can create anomalies too. Israel, which is richer than Britain or France , was included in the emerging-markets index until 2010 for what seems like geographical reasons. Then it went from being a notable emerging-markets investing destination to irrelevancy for many fund managers.
Because it is the only officially “developed” market in the Middle East, Israel is now part of the little-tracked MSCI Europe and Middle East Index created that year instead of the more-followed MSCI Europe, which dates to 1986. It is also a minuscule part of MSCI EAFE, which tracks 21 non-U.S. developed markets. With world class healthcare and tech companies like Teva Pharmaceutical Industries and Check Point Software in the index, “Startup Nation’s” stocks trade at barely half of the forward price-to-earnings ratio of the tech-heavy U.S. market.
And there are other stock markets just waiting to join, or rejoin, the official emerging-markets club. By the time they do the best gains might have been had. Take Argentina , which was demoted to “stand-alone” status three years ago because it was difficult to invest there. It has had a blistering return in dollars of almost 50% a year in the three years through October compared with a negative return for the MSCI Emerging Markets Index over that time.
While far from a foolproof investing strategy, betting that the last shall be first and buying what feels uncomfortable could pay off when it comes to beaten-down emerging-markets stocks.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
Australia’s housing market rebounded sharply in 2025, with lower-value suburbs and resource regions driving growth as rate cuts, tight supply and renewed competition reshaped the year.
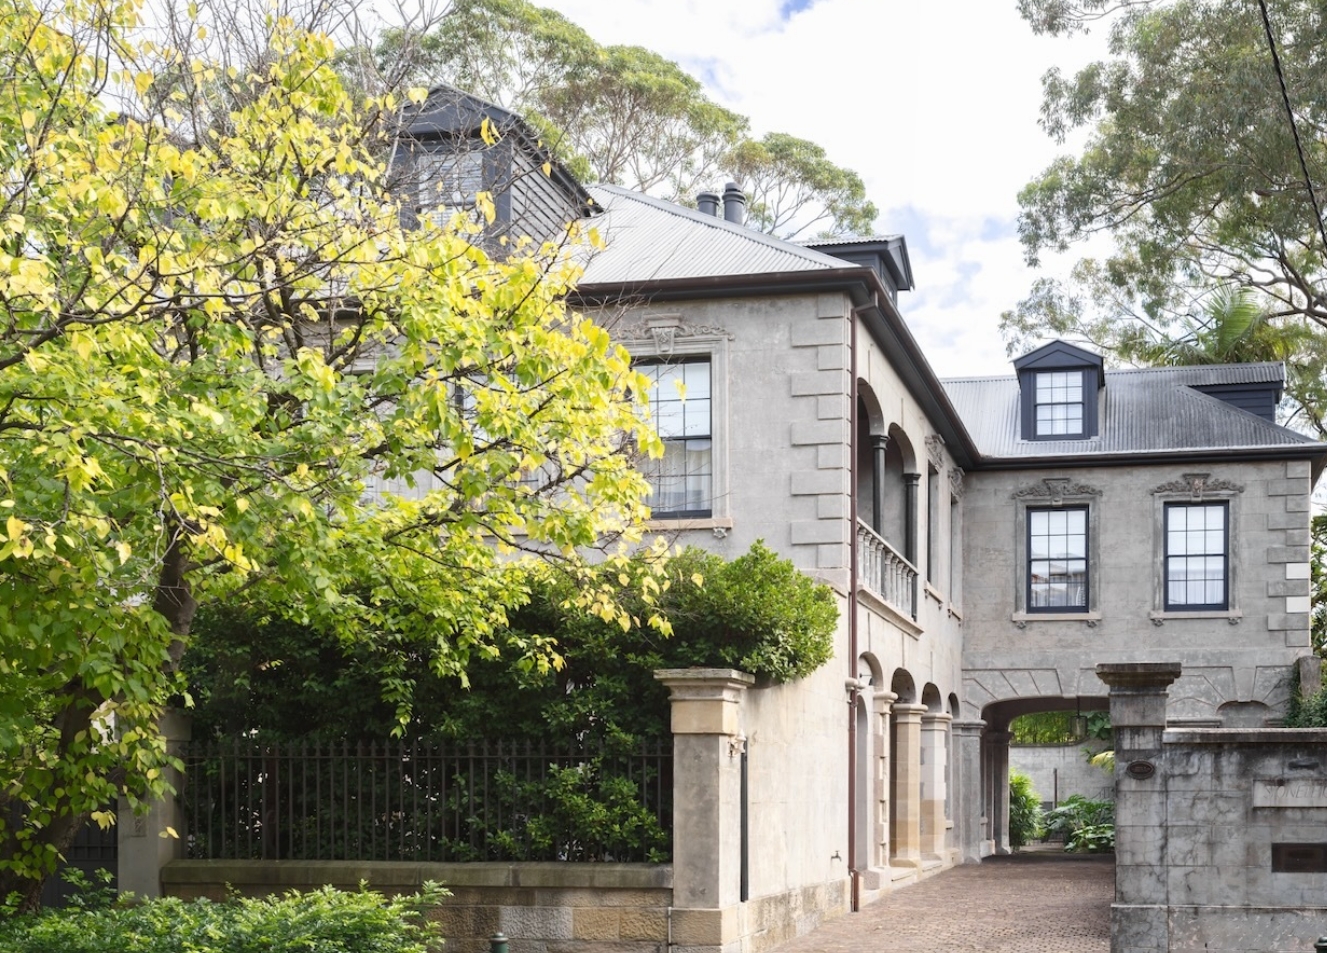
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …