Europe’s Economy Faces Sink-or-Swim Moment as Trump Returns
With the US election result and the German government’s collapse, the lagging European economy is at a crossroads

 4 min
Wall Street’s verdict is clear: A second Trump presidency is likely to deliver a blow to an export-dependent European Union that is struggling with sclerotic economic growth and ever-multiplying political crises. Whether it will finally spark some change is the question for patient investors.
Since Wednesday, the day after the election, the S&P 500 has gained 3.7%. Meanwhile, the Euro Stoxx 50 and the FTSE 100 are down. Among those to shed the most market value have been clean-energy firms such as Vestas, carmakers such as BMW , consumer-goods companies such as Nestlé and Unilever and sellers of pharmaceuticals such as Roche. They all sell a lot to the U.S.
The U.S. is the top goods export market for the European Union, and for Germany, with pharmaceuticals, machinery and vehicles topping the export list.
During the campaign, President-elect Donald Trump floated a 60% tariff on Chinese imports and a 10%-to-20% levy across the board. The think tank German Economic Institute estimates that such a measure could make the German economy between 1.2% and 1.4% smaller than it would have been by 2028.

The core of the European Union’s export machine has been plunged into difficulties because of the end of cheap Russian energy, delays in joining the electric-vehicle revolution and an over reliance on selling to China.
Volkswagen last week announced the closing of at least three plants in Germany. According to FactSet, American customers make up 18% of its sales, about the same as the German market.
“I want German car companies to become American car companies,” Trump said last month while holding a rally in Savannah, Ga. “If you don’t make your product here, then you will have to pay a tariff, a very substantial tariff,” he added.
On Wednesday, Oliver Zipse , chairman of German carmaker BMW, underscored that the company has a plant in Greer, S.C.
“The most demanded vehicles in the United States, we produce there,” he told analysts Wednesday in a conference call. “So there is some natural cover against possible tariffs.”
Volkswagen and Mercedes-Benz have factories in Chattanooga, Tenn., and Vance, Ala., respectively. Manufacturers Airbus , Siemens and BASF also service the U.S. market from within, as do Nestlé and Unilever.
Much depends on details. In early 2021, Airbus’s assembly line in Mobile, Ala., was forced to pay tariffs for its shipments of fuselage, wing and tail components from France and Germany, as part of a World Trade Organization dispute. An agreement was quickly reached to suspend them.
Regardless, building up capacity to service all types of American-based demand would be hard. The Mobile plant makes A220 and A320 jets, but A330 and A350 wide-bodies are assembled in France. Volkswagen uses Chattanooga for the Atlas SUV, the Passat sedan and the electric ID.4, but the bestselling Tiguan and Jetta are built in Mexico. Roughly a quarter of U.S. imported cars originate there, and Trump has suggested that a 200% tariff could be slapped on them.
And when it comes to high-performance models, most EU firms still make them domestically and ship them over. Exports to the U.S. amounted to about 800,000 cars in 2023.
To be sure, EU leaders have struck a conciliatory tone with Trump this week, suggesting that a more amicable endgame such as the 2018 trade deal between the U.S., Canada and Mexico is possible.

Another risk is that China would send even more cheap goods to Europe if the U.S. ratchets up its trade war with Beijing. Yes, recent experience shows that China often just reroutes exports through third countries—and, as of recently, faces higher tariffs for electric vehicles in the EU anyway—but even small shifts could have big effects.
For a decade and a half, the 27-nation bloc has limped along, fostering just enough political change to avoid a painful breakup during the debt crisis of the 2010s and the 2020 pandemic, but never enough to truly invigorate its economy. Attempts by France’s Emmanuel Macron and Germany’s Olaf Scholz to change course have ended in paralysis. Scholz’s three-party government collapsed this week, after years that saw the coalition’s pro-austerity member blocking efforts to spur domestic industry with public spending.
Yet the first Trump presidency did galvanise some early support for a cohesive industrial strategy in Europe. The long-term bull case for European equities is that Trump 2.0 will be a catalyst for further transformation. European Central Bank President Mario Draghi published a report in September urging less red tape, state aid to key sectors and, where appropriate, harsher tariffs, all of which has buy-in from officials in Brussels.
On a small scale, the impulse toward a European industrial policy is already playing out. European defence contractors such as BAE Systems, Rheinmetall and Thales have seen their shares jump on the expectation that less American military involvement in Europe will force governments there to rely on their own capabilities. By 2030, the EU wants members to direct 50% or more of their procurement budgets toward European contractors.
Elsewhere, substituting foreign markets for domestic consumers will prove much harder, though providing advantages to buyers of electric vehicles has proved extremely effective in Norway. They now outnumber cars that run on gasoline.
Caught between the U.S. and China, Europe’s economic strategy is soon to face its biggest challenge since the eurozone crisis. Investors are right to be wary.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A luxury lifestyle might cost more than it used to, but how does it compare with cities around the world?
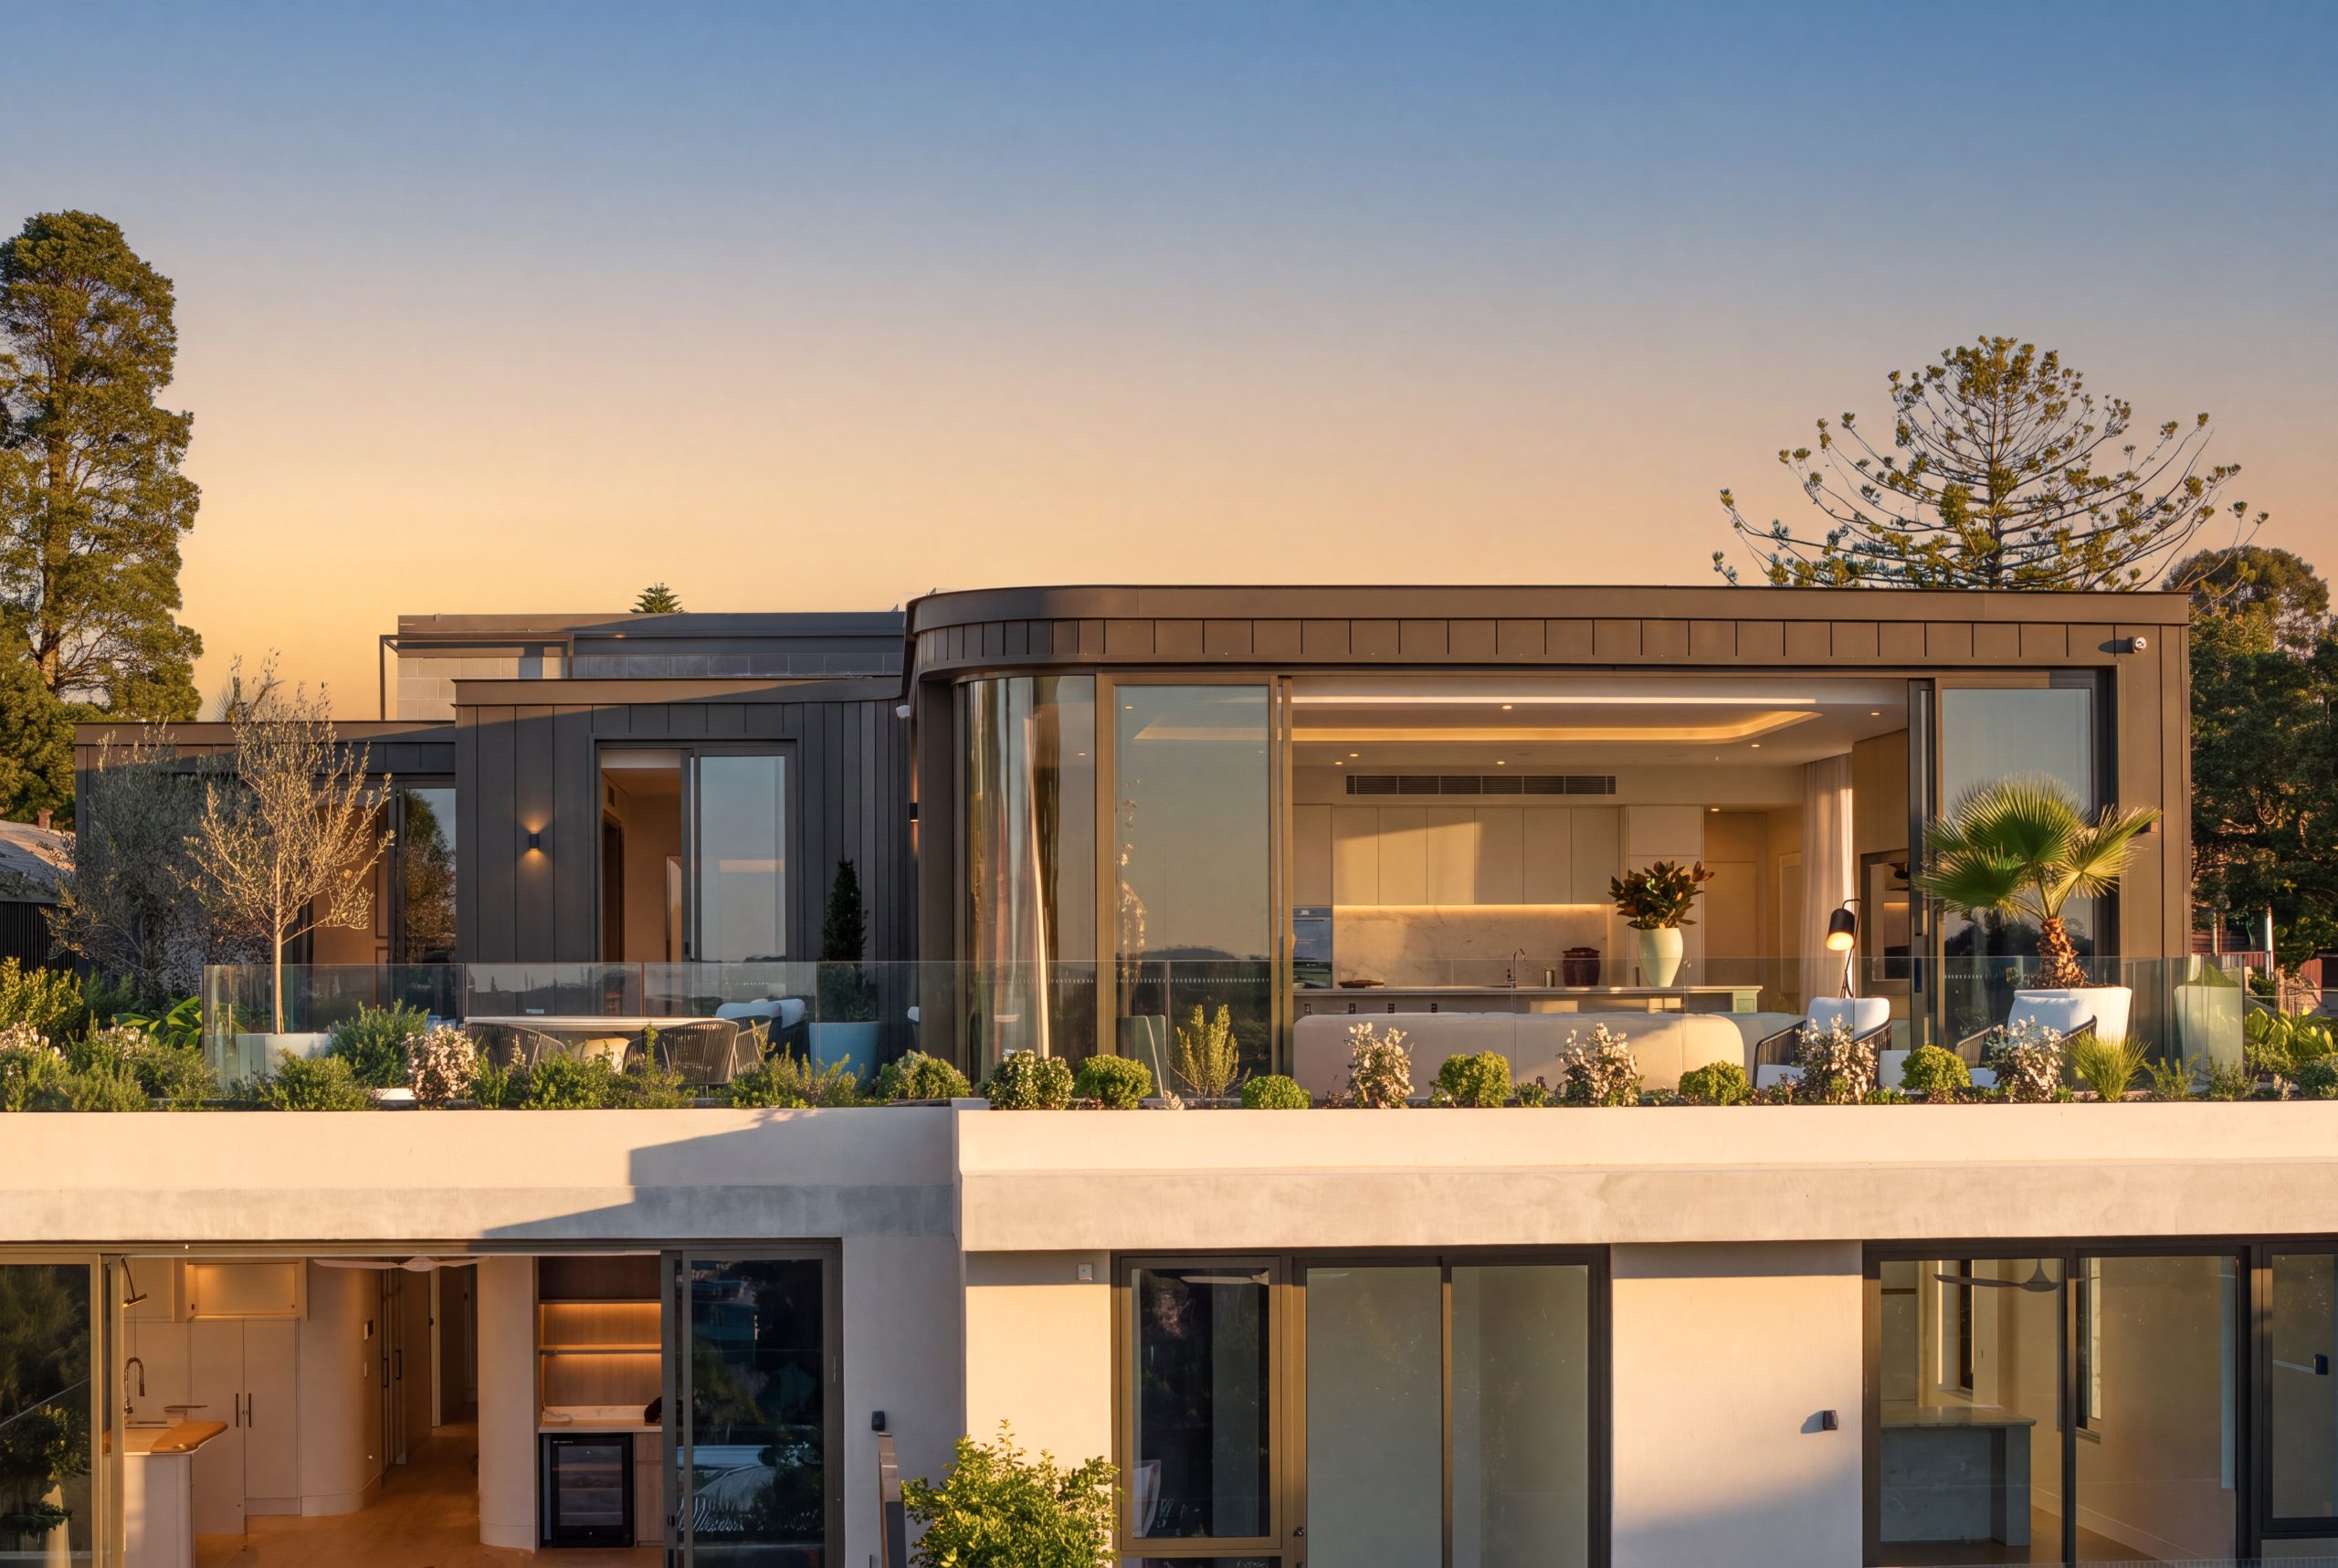
The completed penthouse at Park Residences showcases a considered approach to luxury apartment living, combining northern light, curated interiors and the privacy of a whole-floor residence.