Finding LGBTQ-Focused Investments Can Be Difficult. Here’s Where to Begin.

 5 min
While nearly half of U.S. investors surveyed by Morgan Stanley want to invest in companies led by or making products and services for the LGBTQ community, these investments are difficult to find unless you know where to look.
Several LGBTQ-focused ETFs failed in recent years due to lack of investment, though stock investors can still put money in firms with openly queer leadership, such as Tim Cook at Apple. While opportunities for LGBTQ investments stretch across asset classes—startups attract the most attention.
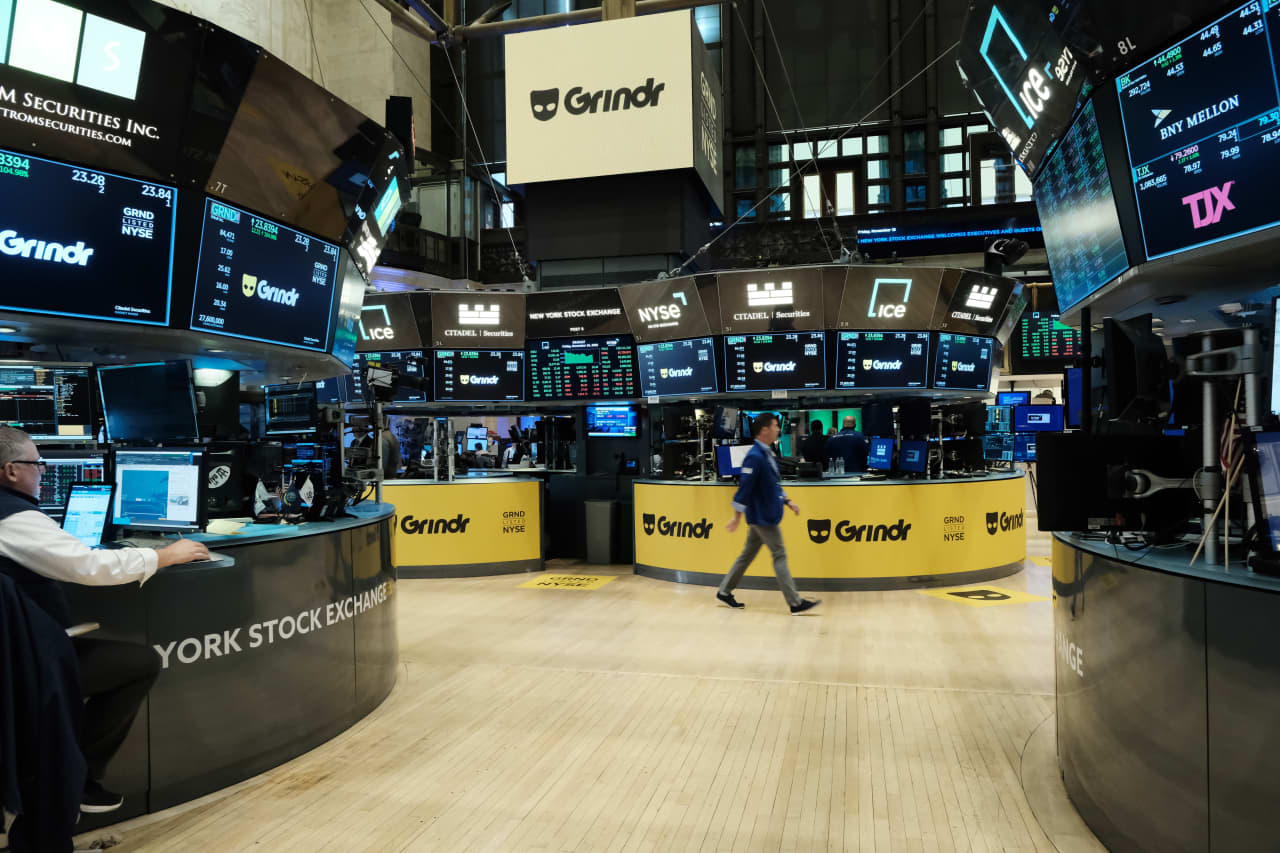
For an answer as to whether this strategy can be successful, look at Grindr. One of the most prominent LGBTQ startups, the social networking app went public in 2022 and has a US$1.78 billion market cap today.
“Almost in every industry that exists, there is an LGBTQ person building [a company],” says Jackson Block, CEO of New York-based LGBT+ VC, a nonprofit addressing investment in the LGBTQ community. This means wide-ranging opportunities to invest in privately-held LGBTQ companies.
Identifying such investments often centres on two key criteria, says William Burckart, co-founder of Colorful Capital, a venture capital firm that invests in early-stage LGBTQ startups: Investors want to know whether someone in the community leads the company or if they are the target market for products and services.
Individuals and families can invest directly in companies getting off the ground or in a growing number of niche funds. Colorful Capital and Gaingels are among several firms that have formed specifically to address a longstanding lack of opportunities for LGBTQ startup founders. Others, like Backstage Capital or Elevate Capital, focus on underserved founders more broadly, including those who are LGBTQ.
According to research from StartOut, a San Francisco-headquartered LGBTQ entrepreneurship nonprofit, only 0.5% of venture funding goes to LGBTQ founders, yet they create 44% more exits, where equity investors earn capital gains through the sale or stock listing of the company, and 114% more patents than the average founder.
Colorful Capital chose to invest in seed- and early-stage funding after determining it was the “glaring gap” that needed to be filled based on conversations with LGBTQ founders, says Burckart.
Backstage Capital and Gaingels, which are syndicates with multiple investors, will support companies at several stages of development. Meanwhile, Elevate Capital, which counts 7% of founders it supports as LGBTQ, offers three funds for investors depending on what stage of investment and type of business they are interested in.
There are economic reasons to consider LGBTQ investments: Multiple studies show correlations between diversity among firm leadership and company performance as measured by internal rates of return, risk management factors, and firm valuations. “From a purely financial benefits perspective, there’s real value in beginning to embrace and integrate that kind of diverse thinking,” Burckart says.
Gaingels, whose members have invested more than US$800 million since 2019, principally invests in health, fintech, and enterprise software, according to Dealroom.co. Recent deals include taking part in a post-seed, series A funding round for San Francisco-based social care platform Grayce and a seed-funding round for Menlo Park, Calif.-based financial community platform AfterHour.
More than 70 unicorns—firms that have reached US$1 billion valuations—have been funded at different stages by Gaingels. These include Seattle-based, goal-oriented telehealth platform Ro and Dapper Labs, a Vancouver-based digital games and entertainment firm.
Block, whose organisation has a mission to educate, train, and mobilise 10,000 LGBTQ and ally investors by 2030, suggests wealthy investors enter the venture capital fray by becoming a limited partner in a fund. This allows investors to get involved with less risk and comparatively steady return expectations compared to angel investing.
Geographically, many LGBTQ companies attracting investment are North American, though regional funds exist in Europe and Latin America, Block says.
For wealthy families, investing in LGBTQ-related businesses can be a strategy to engage the next generation, as products and investment strategies that advance LGBTQ equity and inclusion are in high demand among younger investors (56% of millennials and 67% of Gen Z, according to Morgan Stanley). This is unsurprising, given that Gallup polling suggests more than one in five Gen Z adults and one in 10 millennials identify as LGBTQ.
Morgan Stanley’s Institute for Sustainable Investing estimates that those interested in LGBTQ investments control about one-third, or US$20 trillion of U.S. wealth managers’ assets under management. With the impending generational wealth transfer, the bank says control of interested investors could grow to nearly half of the assets under management at all wealth managers. Block expects that creating opportunities for LGBTQ fund managers will also help grow LGBTQ investments, and will create a “natural pipeline” for them to find roles with major investment banks.
In identifying investments, Morgan Stanley offers strategies that screen-out certain companies, says Emily Thomas, head of Investing with Impact, Morgan Stanley Wealth Management, the bank’s platform featuring funds and other investment vehicles for values-based investing.
“Per our survey, 76% of investors interested in LGBTQ impact objectives are also interested in the ability to exclude companies that don’t explicitly include protections for LGBTQ people in their labour rights policies,” Thomas says.
Getty Images
There are also companies owned or run by individuals with family and friends who are LGBTQ and want to make sure their company helps support and gives back to the community.
Recently, a banking executive spoke about their experience being raised by lesbian parents at an LGBT+ VC ally event. Morgan Stanley reports 76% of heterosexual investors with an LGBTQ household member want such investment options, more than the general population.
The biggest barrier to finding LGBTQ investment strategies is being able to gather data on the community, Thomas says.
Individuals can have reservations about sharing information regarding sexual orientation or gender identity—54% of LGBTQ individuals in the U.S. live in areas without state-level protections. Ongoing stigma against the community also prevents some people from openly identifying as LGBTQ.
“Only with more data can we know the extent of inclusion in, and exclusion from, the structures that make up the foundation upon which the U.S. economy is built,” Colorful Capital said in a May report.
(There are forces trying to change this. Earlier this year, the U.S. Census Bureau’s monthly American Community Survey announced it is looking into asking about sexual orientation and gender identity.)
Because of the sensitive nature of data and laws around personally identifiable information, there isn’t readily available data on the percent of employees who identify as LGBTQ or what representation looks like at senior levels, unlike for gender diversity. Comparably more data is available on corporate policies on LGBTQ matters, so some asset managers use that to identify companies as investments, Thomas says.
“For example, [an] asset manager can tilt portfolios toward companies that offer domestic partner benefits to same-sex couples,” she says. Other strategies could include screening for companies that offer LGBTQ diversity training or have not faced Equal Employment Opportunity Commission disciplinary actions. Investors can also use benchmarks such as the Human Rights Campaign Corporate Equality Index, which scores about 1,400 publicly and privately held firms on several areas of LGBTQ policies and practices, including whether they offer domestic partner and transgender-inclusive benefits,
Institutional Allocators for Diversity, Equity, & Inclusion, a nonprofit group of asset owners aiming to promote those principles within investment management, has a publicly available diverse manager database, which allows funds to self-report LGBTQ affiliation, Thomas says.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
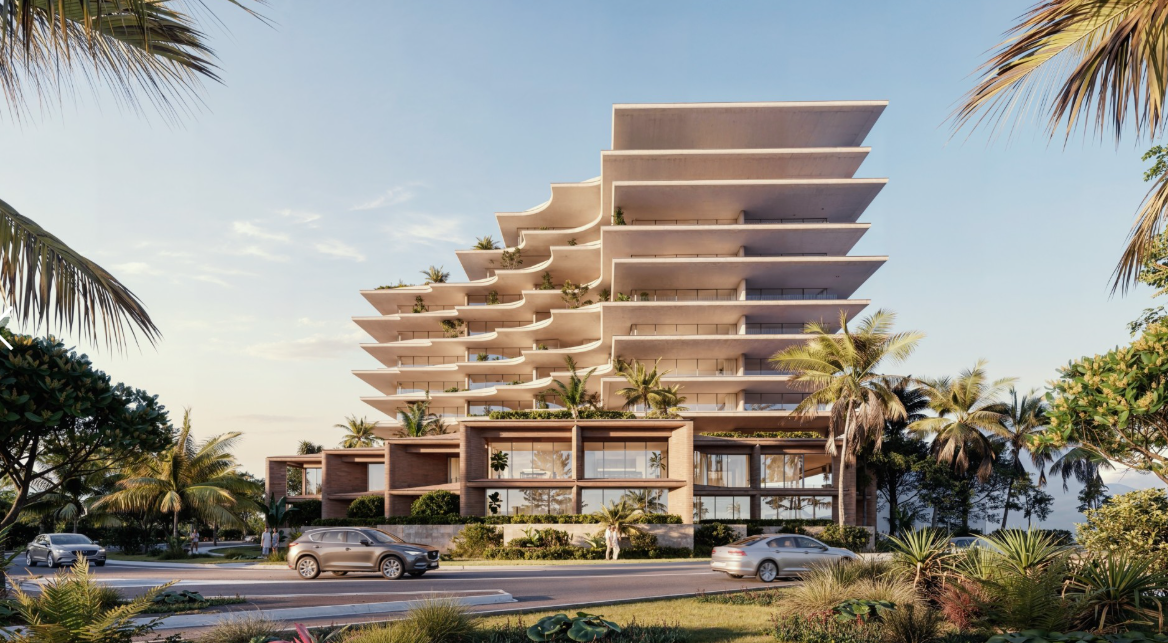
Queensland-based builder-developer MAYD has unveiled an exclusive first look at its anticipated ultra-luxury North Kirra mixed-use project as it lodges a minor amendment with the City of Gold Coast Council. The project sits across a 4,742sqm amalgamated landholding spanning seven parcels at 2–6 Pacific Parade and 27–33 Golden Four Drive, Bilinga, which MAYD secured in …
Continue reading “MAYD”s North Kirra Plans Unveiled Ahead of Early 2027 Launch”

Hand-built in Melbourne and limited to just 10 cars a year, the Zeigler/Bailey Z/B 4.4 is reshaping what a modern collector car can be.