Former Wells Fargo Advisors Sue the Company Over Cross-Selling

 3 min
Two former Wells Fargo advisors are suing the firm for breach of contract, unfair business practices, and retaliation after they say they resisted pressure from their supervisors to secretly transfer sensitive client information from the advisor and brokerage side of the company to the private bank.
The advisors, Karen Keusayan and Richard Green, are also alleging that Wells Fargo improperly withheld deferred compensation after they resigned in 2021 and joined Morgan Stanley , where they are still registered.
In their complaint, filed in Los Angeles County Superior Court, the advisors describe themselves as high-producing employees who were loyal to the company even through the “nightmarish” years of 2015 to 2017, when Wells Fargo’s banking division was “publicly scorned” for the fake account scandal.
“This is not the ‘sour grapes’ case of a disgruntled employee(s) who sought a promotion and did not get one,” the advisors say in their complaint. “Neither Ms. Keusayan nor Mr. Green ever wanted to leave Wells Fargo. The goal for each had always been to retire at Wells Fargo.”
Wells Fargo declined to comment on the lawsuit.
The two advisors joined forces in 2015 to form a “production partnership,” according to the complaint, which says they grew their book of business to more than $1 billion by 2020.
In 2018, Wells Fargo introduced a new element to its advisor compensation plan, according to the complaint. Advisors were expected to complete forms called client discovery reviews, or CDRs, detailing information about advisory clients. The plaintiffs say they were directed by a compliance officer to keep the forms secret from the clients themselves.
Instead, the CDRs were intended for Wells Fargo’s private bank, “not the broker-dealer/financial services side where plaintiffs worked,” according to the complaint.
They contend that advisors were pressured to work with clients to complete CDRs, which would be secretly shared with Wells Fargo private bankers who could use them as sales leads.
Before submitting the forms to count toward a quota that resulted in additional compensation, the advisors had to check three boxes stating that they had discussed the information with the client, that the information was accurate, and that they had offered the client an opportunity to obtain a copy of the document. On that last item, the plaintiffs allege that Wells Fargo essentially instructed the advisors to lie, explaining that the document didn’t belong to the advisors, but the bank, even though the information came from their own clients.
“[H]igh-ranking compliance personnel at Wells Fargo Advisors repeatedly told plaintiffs to never deliver or present the CDR to the client since, as it was explained by compliance, the CDR was a bank document,” the complaint states. “Worse, plaintiffs were told not to inform the client that a CDR had been prepared.”
The plaintiffs say that these “dishonest instructions” put them in an “impossible position” and that they soon began raising concerns with their superiors. But each time they spoke out, they were told by their supervisors to continue submitting the forms as a requisite part of the company’s compensation plan.
The complaint describes the advisors’ growing unease with being pressured to falsify the CDR submission document, as well as concerns over the personal privacy of their clients, whose information was allegedly being shared internally without their knowledge or permission.
The advisors say that their bosses undertook a retaliatory campaign against them for continuing to raise objections to the CDR program, “including by failing to provide the banking support that plaintiffs and their clients had come to expect as a benefit of being associated with a large, full-service, retail bank,” according to the complaint.
They also say that the advisors felt their jobs were at risk, offering examples of a hostile or coercive work environment. “Mr. Green was berated by a yelling supervisor in front of fellow employees, and Ms. Keusayan was informed that the bank would not issue a routine credit card to her sister (a customer) if a CDR was not on file,” according to the complaint.
The advisors say the deteriorating work environment ultimately led them to resign around July 2021, after which they were informed that they were ineligible for large sums of deferred compensation—$662,000 for Keusayan and nearly $814,000 for Green.
The advisors are seeking to recoup the deferred comp they say they are owed, and are asking the court for additional damages, as well as an injunction barring Wells Fargo from engaging in the conduct alleged in the complaint, among other relief.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.

A bold new era for Australian luxury: MAISON de SABRÉ launches The Palais, a flagship handbag eight years in the making.
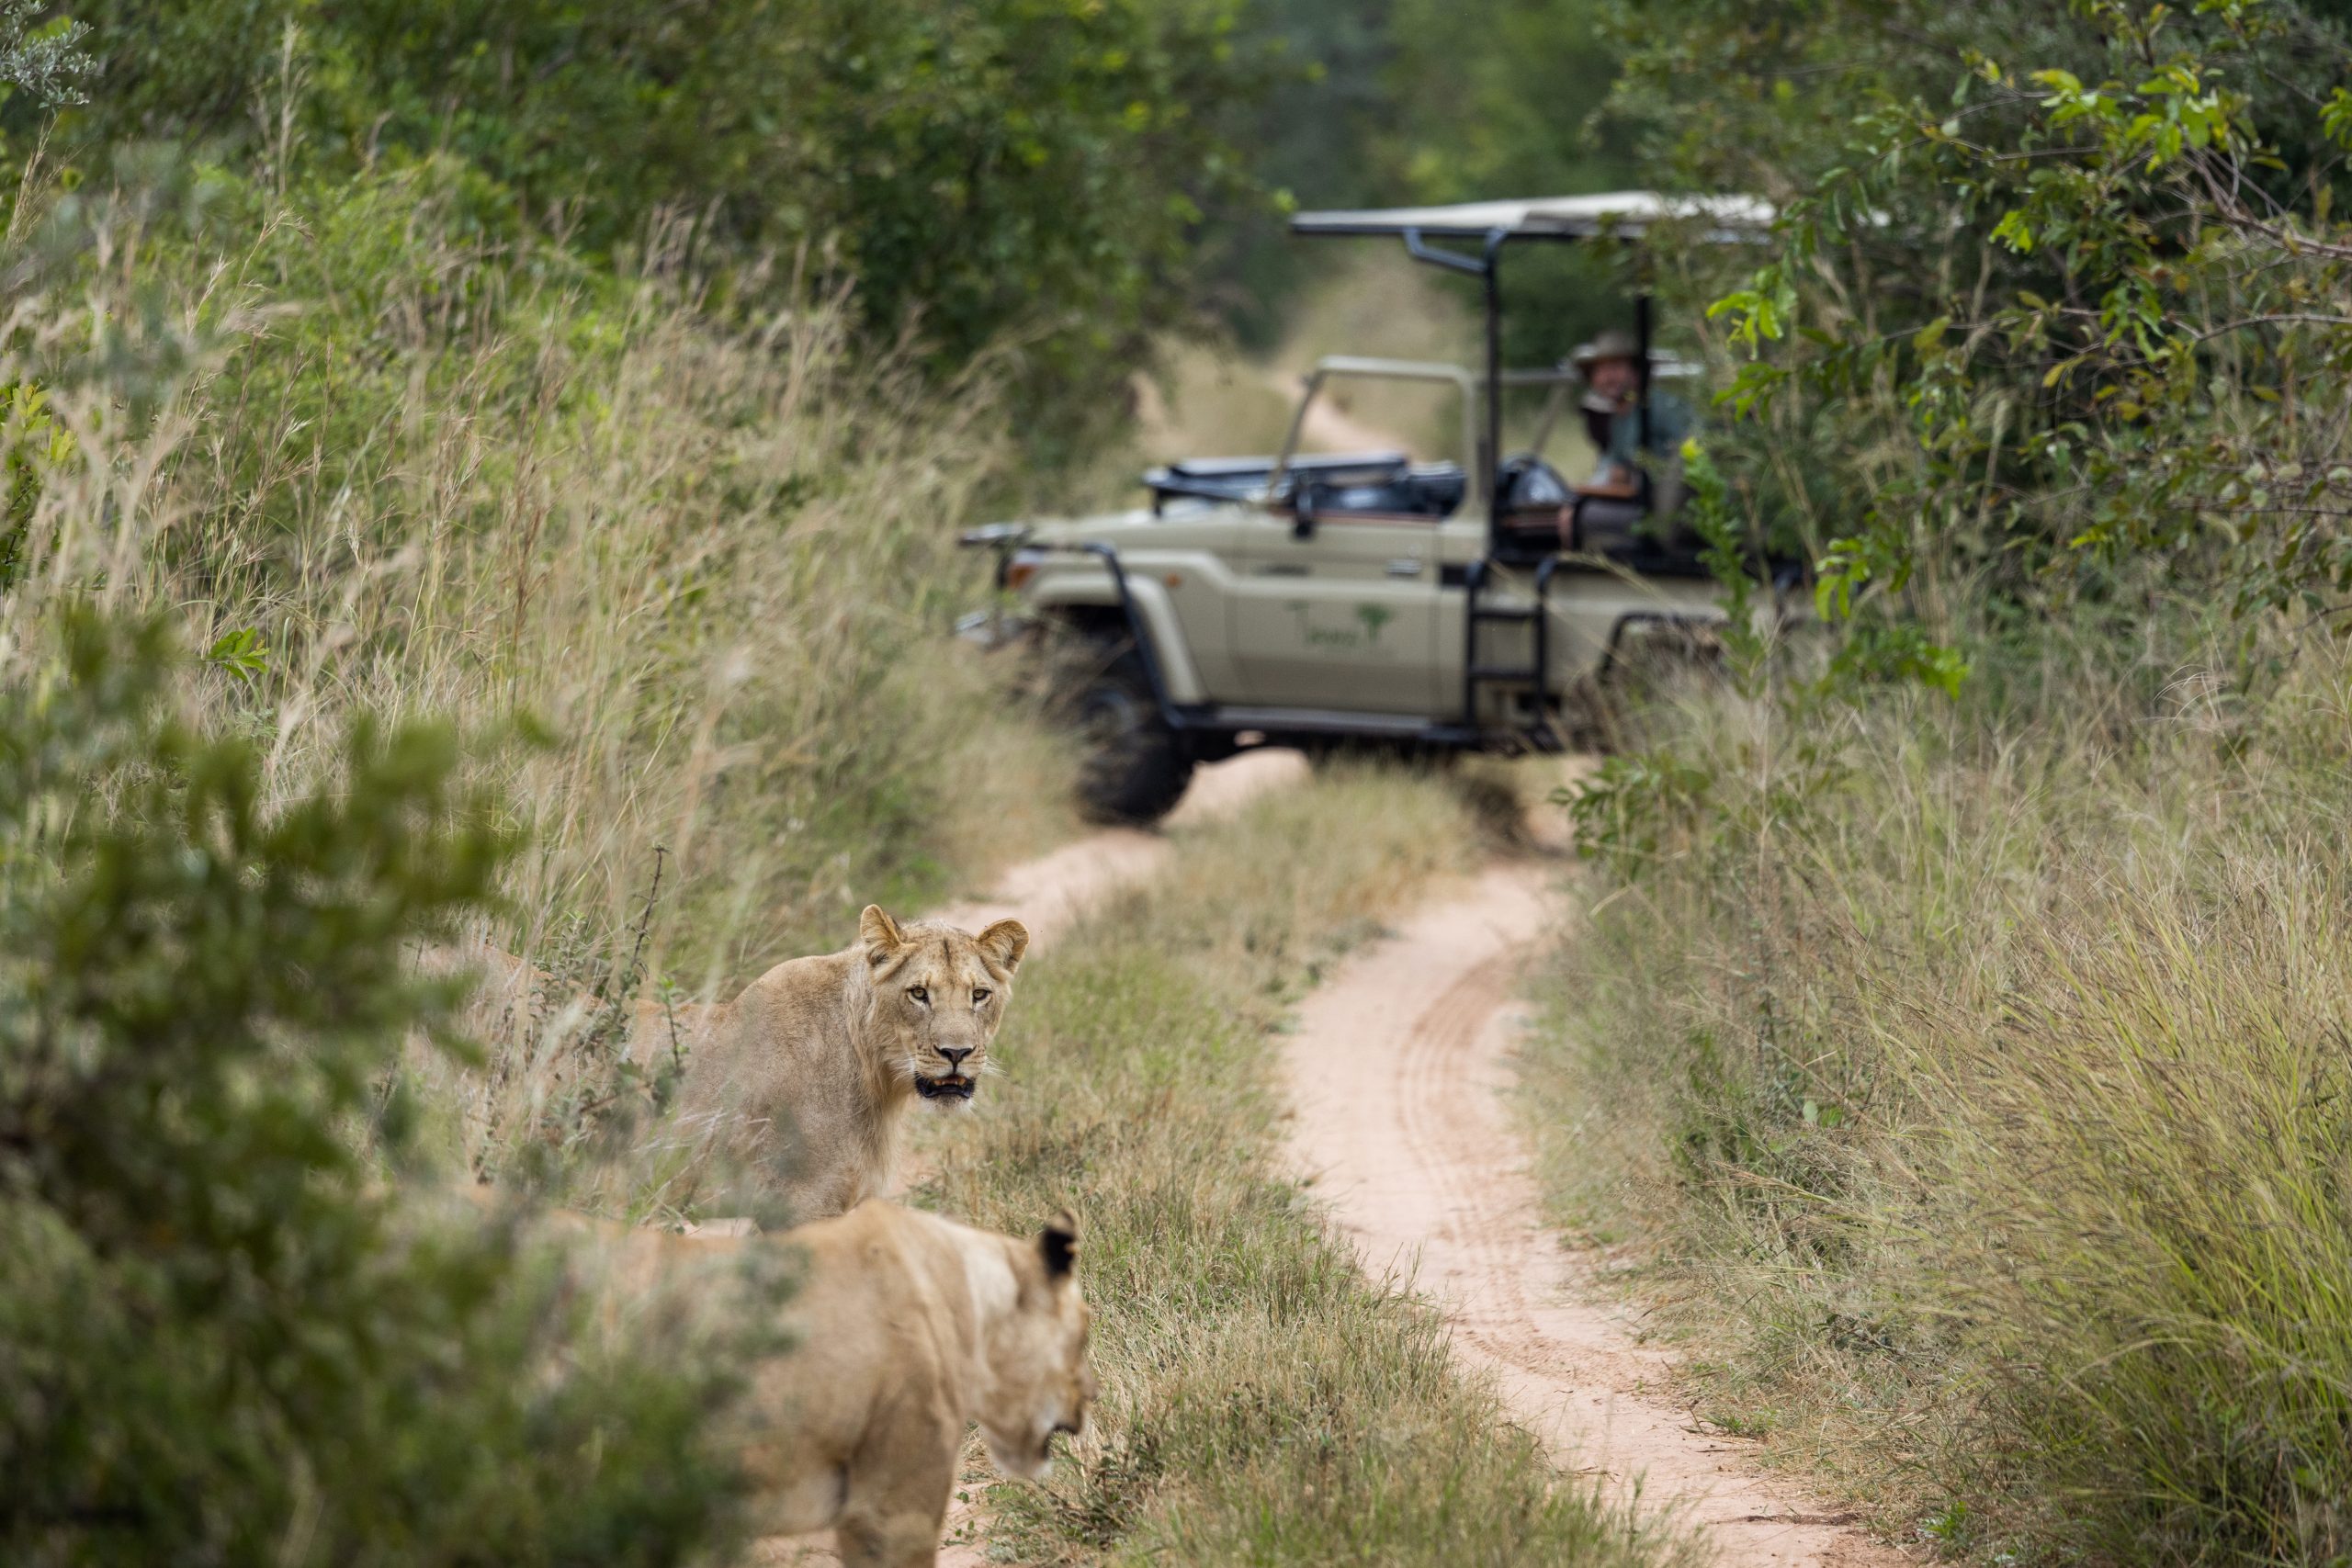
Exclusive eco-conscious lodges are attracting wealthy travellers seeking immersive experiences that prioritise conservation, community and restraint over excess.