Here’s What Retirement Looks Like for Single Women in America
Four retirees open up about their finances and how they spend their time

 7 min
The risk of running out of money in retirement rises for those with lower pay, longer lives or no partner.
Millions of single women wrestle with all three.
Women earn less than men on average during their working years and are more than twice as likely as men to leave the workforce for more than one year to care for children or ageing parents , according to a survey of 5,261 Americans that Goldman Sachs plans to release Monday.
This shortfall compounds in retirement. Social Security checks are 20% smaller for women who first claim at 62 to 64 years of age, compared with men the same age.
Single women, in particular, have smaller 401(k) and IRA nest eggs . On average, single women between 55 and 64 have about $88,600 in retirement savings, compared with $136,685 for single men and $423,800 for married couples in the same age group, according to Boston College’s Center for Retirement Research.
Women also tend to live longer , raising the projected total cost of retirement as they have to stretch their smaller savings over more years.
Despite these financial obstacles, single women find ways to pursue new ambitions in retirement, including launching businesses and traveling the world. They could have more time if their caregiving responsibilities have ended. With more freedom than many of their married counterparts, some women can make big changes without needing to compromise or negotiate.
We spoke in depth with four single women who have retired. Some have sizeable nest eggs, while others rely on Social Security benefits or earnings from part-time gigs. Each has found fulfilling ways to define retirement for herself.
Deb Hallisey saved diligently during her career as a consultant, and sought help from a financial adviser.
As a single woman, the Lawrenceville, N.J., resident said, “I knew it was going to be on me to provide for myself.”
All that planning was thrown off track after her father died in 2015. She had to put her work with clients on hold to help her mother—who was blind—find live-in help. When her billable hours dropped that year, she lost her job.
Hallisey, 66, sent résumés to consulting contacts, but she was tired of traveling and craved a new challenge.
She found it in becoming a caregiver for her mother, who died in 2022. In addition to handling her mother’s finances and medical appointments, Hallisey spent half of her weekends at her mother’s house to give her mom’s paid caregiver time off.
Angry and resentful, Hallisey quickly realised something had to change.
“When I was angry, my attitude gave Mom an attitude, and we’d start the weekend off wrong. There is a moment when you say, ‘I can’t keep doing that,’ ” she said.
Her mother urged her to write about her caregiving experiences, something Hallisey threw herself into in 2016, after meeting a successful blogger.
She soon launched a website, Advocate for Mom and Dad, and has written two books about caregiving. She speaks frequently on the topic and does consulting for families.
Hallisey saved $600,000 for retirement and built a $50,000 emergency account she used after the layoff. She currently takes $2,500 a month from her retirement savings and earns $500 a month from her business.
Thanks to the strong stock market, her balance is $525,000. Her home is valued at about $500,000 and she has paid off her mortgage.
In June, Hallisey plans to claim Social Security and use her $3,400 monthly benefit for living expenses. Her goal is to leave her IRA for emergencies, including future caregiving expenses.
She recently hired a financial professional to serve as her power of attorney if she becomes unable to manage her finances. After having done that for her mother, she said, “I could not in good conscience ask a friend to do that for me.”
She spends about $2,200 a month, including $260 for home and car insurance and $250 for food. She sets aside $750 a month for property taxes.
She never expected to tap in to retirement savings early, but has no regrets.
“I’m not making enough to support myself,” said Hallisey, who plans to write another book. “But I love it.”
Marianne Simpson retired slowly.
She chose to wind down her financial advisory business over three years, using the transition to test drive retirement while continuing to build up her nest egg. All this still didn’t fully prepare her, she said, for the moment she put her longtime home up for sale and closed the deal on her new life.
She left the Cleveland area and her 25-year career behind and bought a new place in Chicago close to her daughter, son-in-law and two young grandchildren.
With $2 million in retirement savings and a $3,800 monthly Social Security check, she’s in much better shape than most retirees. She also knows better than most how one’s health and lifespan can largely dictate how long money lasts.
“My daughter tells me to spend more on myself, but my mother lived to 101 so I want to make sure I don’t run out of money,” Simpson said.
As a single adult, she said it is critical that she can manage any future healthcare challenges independently and not have to rely on friends or family.
She now spends about $11,000 a month, around half of which goes to setting aside reserves for large expenses such as taxes and insurance. Her big yearly expenses are about $10,000 for insurance including her long-term care and personal umbrella policies, $10,000 to charity and $15,000 in property taxes. Simpson spends roughly $12,000 a year on travel, including her recent two-week trip to Spain.
She volunteers in her church’s shelter for Venezuelan migrants, cooking dinners and doing laundry. She also volunteers several times a month at a local secondhand store where all of the receipts go to local charities.
“The volunteer work helps give me a new sense of purpose,” she said.
Simpson has met new friends, though socialising as a single woman isn’t always easy, she said.
“Much of the world still moves in couples,” she said.
Stephanie Perry retired at age 41.
Perry was inspired by the FIRE movement, which stands for Financial Independence, Retire Early. Those in it save aggressively and pare spending so they can leave work decades ahead of schedule.
“Retirement is the freedom to be anywhere in the world at any time,” she said.
When she told her parents she was quitting her pharmacy tech job to live the rest of her life traveling the world, they worried about her mental health. Eight years later, her parents see how happy she is and have come around to the idea, she said.
Perry does work, but no more than 10 to 20 hours a week on average. She earns money through house sitting, a YouTube channel, virtual coaching and co-hosting events for Black women. She only takes on projects she likes.
Early retirees often call this part-time approach “barista FIRE.”
Since her early retirement, she has saved more than $100,000 in a Vanguard IRA. She has no debt and all her various side hustles add up to a six-figure income, she said. Perry has traveled to more than 30 countries, including Australia, South Africa and Cambodia.
Now 49, Perry never pictured this life when she was in her 20s and 30s.
Perry said she was miserable working the overnight shift at the pharmacy. She revenge-shopped and ran up debt to temporarily soothe her spirit. The bank foreclosed on her house.
She began following YouTubers who were enjoying early retirement and an itinerant lifestyle. She wanted to retire, too.
She spends about $2,500 a month, on average, including travel medical insurance, her cellphone and food. She lives out of two suitcases and stores the rest of her belongings at her parents’ home in Delaware, where she visits three or four times a year.
Perry checks in with family and friends in the U.S. regularly through video calls. She goes on the occasional date, but has no plans to get married.
Perry never wants to own a home again and has no plans to live full time in the U.S. She’s working on a book for Black women about how they can leave their 9-to-5 jobs. She would like to settle down in Mexico or Costa Rica one day but hasn’t immediately made preparations for retiring from working entirely.
“I’m never going back to my old life,” she said.
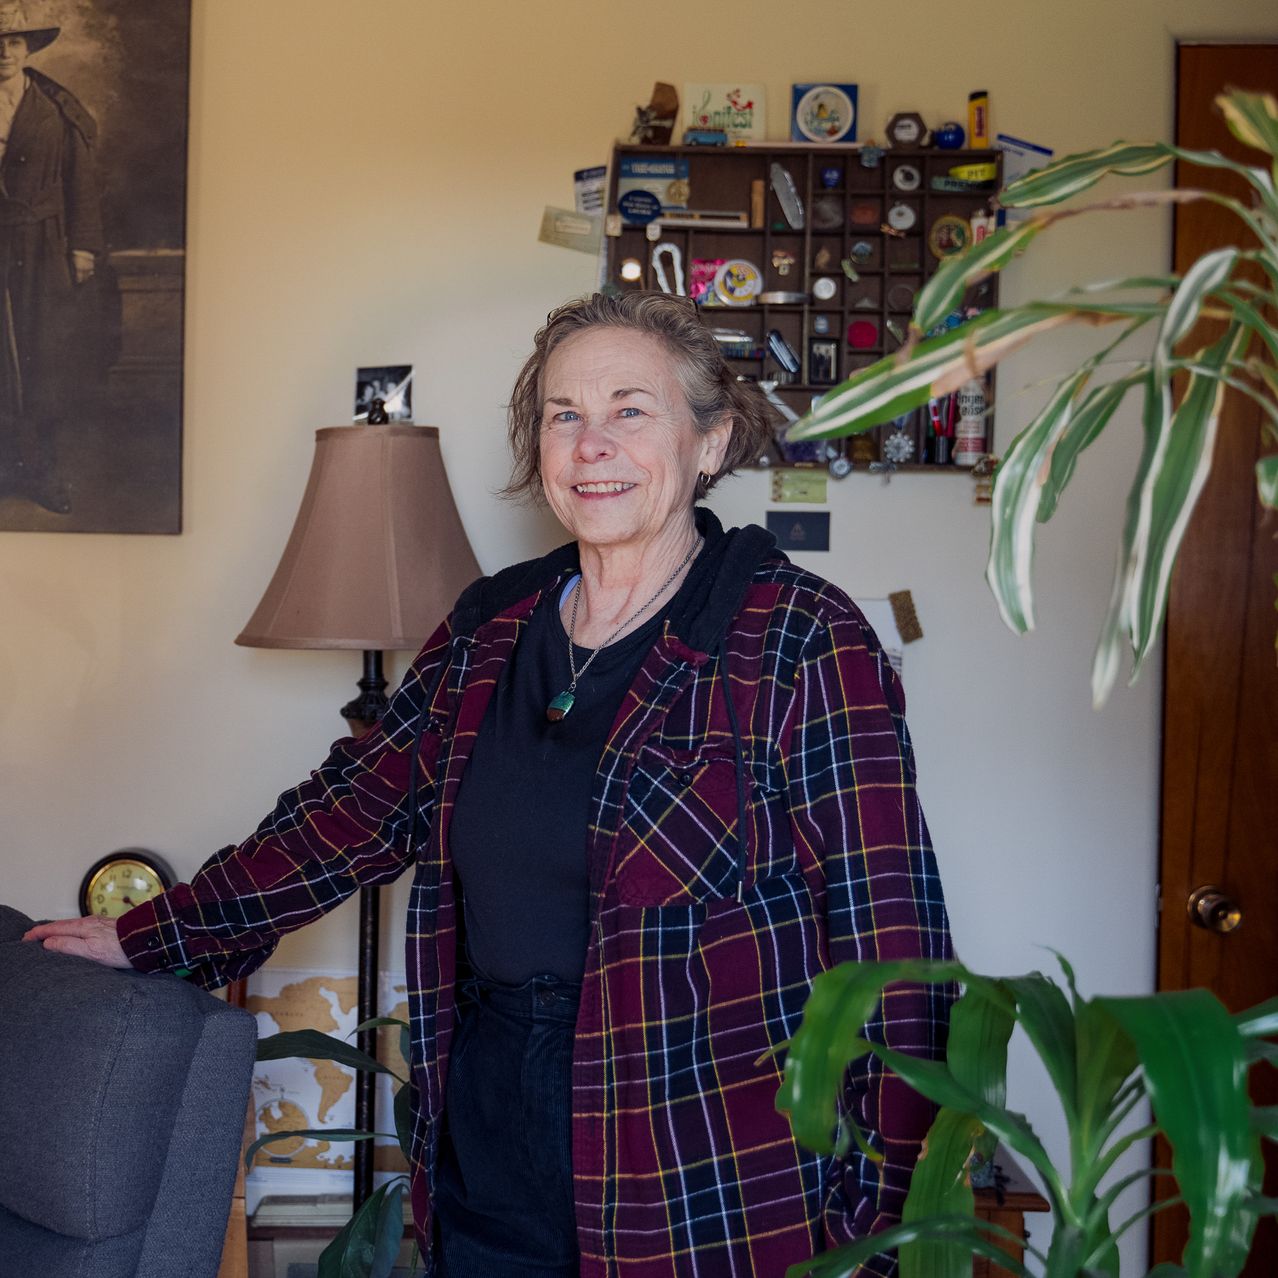
Lori Renee Fye , 65, joined the U.S. Air Force after high school, serving in a mobile radar unit in Germany and at bases across the U.S.
She continued traveling after the military, working in administrative jobs for a conservative pundit in Washington, D.C., an apple baron in Texas, and the chairman of a Native American tribe in California. After her divorce in 2014, she sought refuge in European travel.
After her younger brother’s divorce in 2018, she returned to the Canton, Ohio, area where she grew up. She came to provide emotional support and never left.
“This is the place that made me, gave me my work ethic and basic values,” said Fye. “There is a thing called a sense of place. I’ve realised I’m back in my place.”
Canton is more diverse than she remembered. No one is shocked anymore at the sight of a woman riding a motorcycle, as Fye used to do, she said.
This fall, Fye began volunteering about 30 hours a week at a newly opened LGBTQ+ community centre, Queer in Canton. She gives tours and helps organise the cafe and a clothing donation closet.
Though she says she’s an introvert, Fye enjoys meeting new people, even a group of teens that gathers weekly at Queer in Canton.
“Young kids usually get on my nerves,” she said. But “seeing them hang out together is one of the greatest joys I get from the place. It gives them a place to go and be with other kids who are different and not be bullied.”
Fye, who earned about $70,000 at the peak of her career, lives on her Social Security check of $1,665, plus the $100 her former spouse sends her each month.
She wishes she had worked a little longer to boost her Social Security benefit.
She pays monthly rent of $500 to her brother, who owns the two-family home they share, bordering a woodsy area with a creek.
“I feel very secure here. He pays for the water and Wi-Fi. I pay for the trash collection and the bulk of the mortgage,” she said. “It’s nice to be with someone I can trust to be there for me. Everybody needs one person. My brother is my person in a lot of respects.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
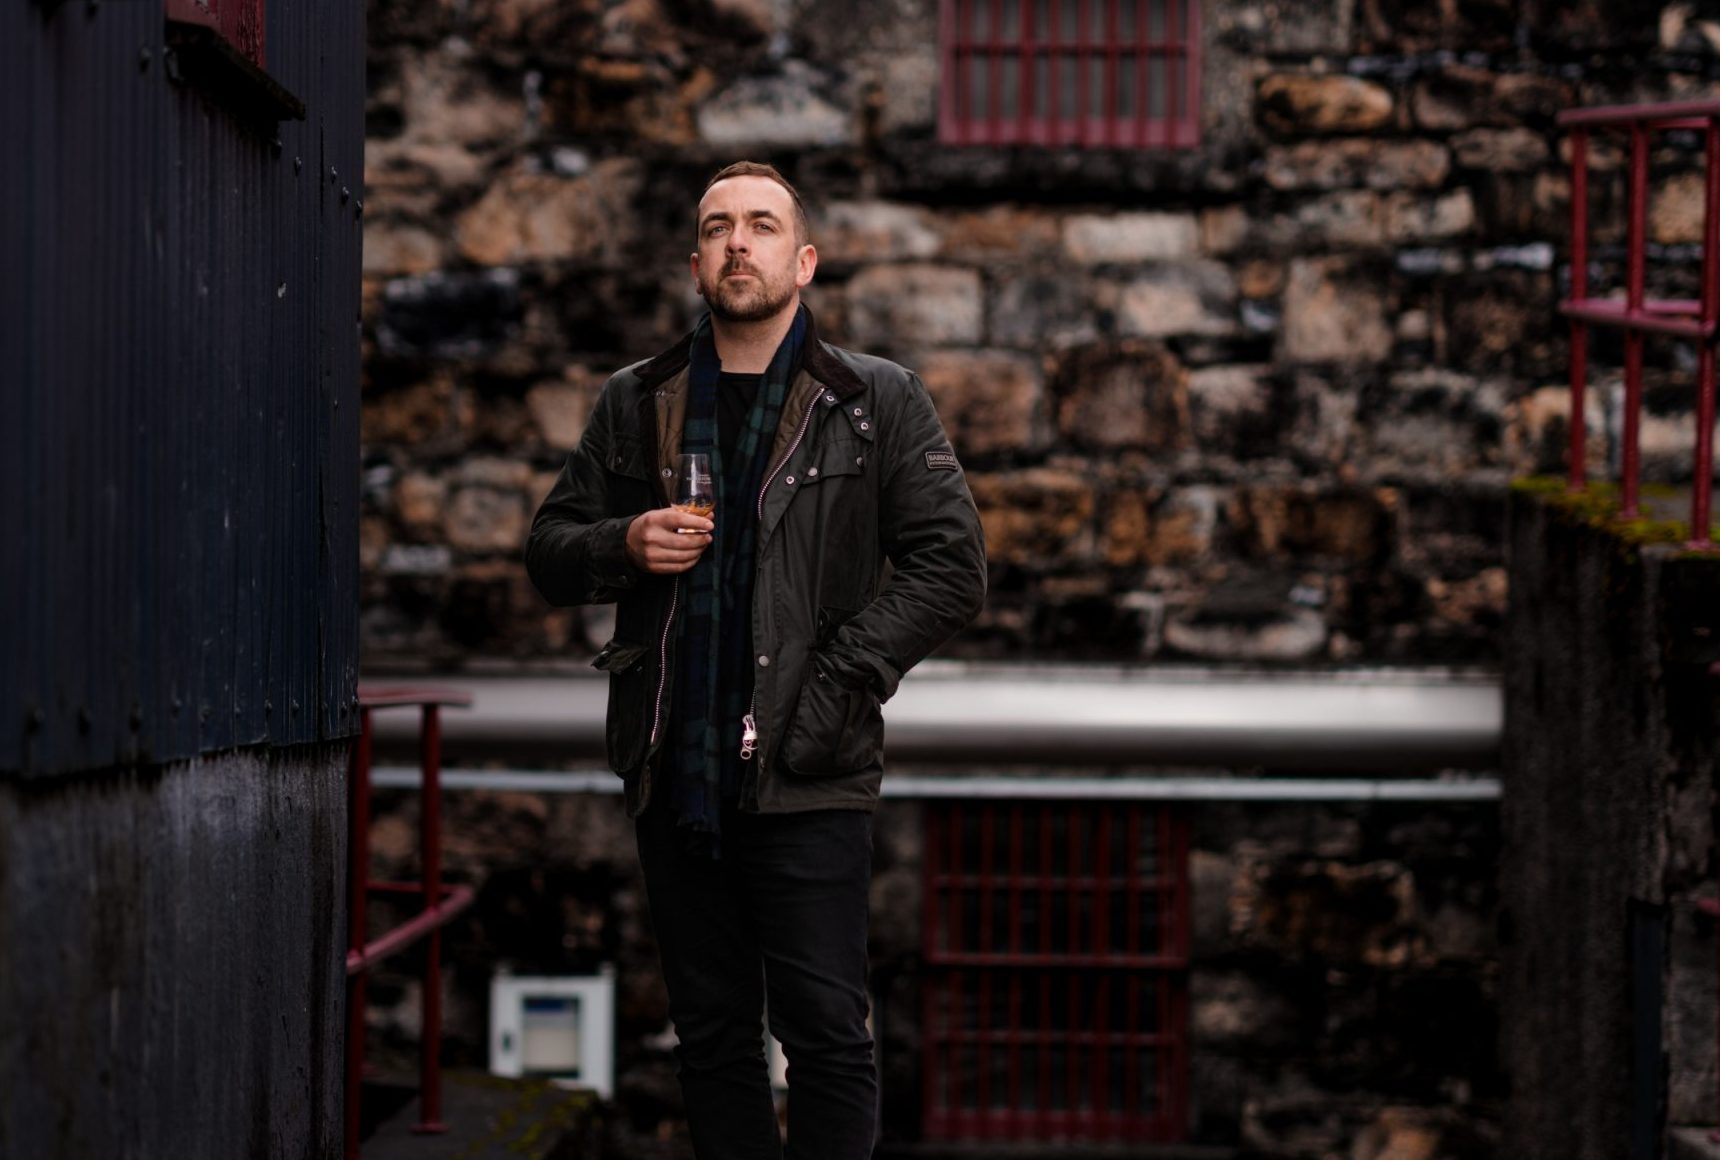
Scotch whisky expert, luxury hospitality strategist and Keeper of the Quaich inductee Ross Blainey is bringing a new philosophy of luxury experiences to Citizen Kanebridge.

The PG rating has become the king of the box office. The entertainment business now relies on kids dragging their parents to theatres.