How to Handle Making More—or Less—Money Than Your Friends

 4 min
Over the past year, I’ve watched as one friend lost a job, another scored a life-changing bonus, two took huge pay cuts and yet another sold a home at a large profit. As for me, my financial life sort of stayed the same. But what did all this mean for my friendships? An individual change in someone’s financial situation can have ripple effects throughout our greater social groups and wider peer networks, researchers and therapists say. One person’s financial loss and another’s sudden windfall can affect the ways in which we stay connected with our friends, and fights about money can lead to personal money problems or even friend breakups.
“The perception is ‘Oh, we’re on the same path,’ and as you get older, that’s not the case,” says Blake Blankenbecler , a financial therapist and friendship educator. “There is space to talk about it with your friends. But can it be cringy to talk about? Yes. Is it important to talk about? Yes.”
Humans typically gravitate toward people who are similar to us in some way, and we cling to that sense of similarity as the friendship grows and changes, says Rebecca Adams , professor of social work at the University of North Carolina-Greensboro. Individual privileges like family money, inherited wealth and more don’t always mean that perception is accurate, of course; but at the onset of a friendship, this sameness breeds closeness.
A growing divide
When we meet in college (as I met the folks now making up one of my oldest and dearest friend groups) or deskside at a job (how I bonded with two of my newer besties) we perceive ourselves to be on equal financial footing with the people we hold close. We chased down bargain-store deals and planned ad hoc dinner parties of rent-week leftovers. During an internship in New York, my best friend and I crammed together in the world’s tiniest sublet, subsisting off Trader Joe’s coupons and our dreams for the future. But more than a decade removed from those days, our financial lives have branched in all sorts of different directions. As we grow—or not—in our respective careers, these gaps in income and wealth will only widen, says Rhaina Cohen , a podcast producer and author of the coming book on friendship, “The Other Significant Others.” But we’re also loathe to change our behaviour or discuss how these individual ups and downs will affect the glue holding the friend group together.
“In my early mid-20s, people were pretty open about what they could and couldn’t afford, and things being expensive, but I think as people have risen up the career ladder, there is less conversation about that,” Cohen says. “The awkwardness of acknowledging that people are in really different places keeps people from having those conversations. But as we get older, these divides are more likely to crop up.”
Opening up the conversation
More often than not, the friend who’s suffered a financial setback feels the burden of communicating their new needs to the group—but doing so can be much, much harder to put in practice. Ashley Appelman , a 36-year-old living in Washington, D.C., took a significant pay cut after making a big career transition a few years back. At the time, her social calendar stayed packed with numerous friends’ weddings and bachelorette parties. Rather than bow out of these commitments or suggest cheaper alternatives, she decided that putting flights on her credit card and forgoing her savings goals was worth avoiding awkward conversations and pitiful glances.
“You don’t want to disappoint people,” she says. “I have given into so many things where I didn’t really have the budget, and I just did it.”
In her four decades of financial advising, Eileen Freiburger , managing director of the Garrett Planning Network, says she has often seen people’s behaviour change after a big money move in either direction. The friend in a lower-paying job finds themselves spending far outside their means, or the pal with more in the bank feels guilty after picking the expensive restaurant for dinner.
“Who you surround yourself with and your own value system will actively impact the next stages of how you handle your money,” Freiburger says. “Are you picking up those tabs because suddenly you can? Are you trying to spend with the Joneses?”
From her perspective, she has seen immense value in holding on to people who can ground you in your original values system, the rules you lived by before these “life happens” moments rocked your financial life. Sometimes, these people are the old friends from before; other times, they’re new friends you make after.
Finding the path forward
Financial advisers and friendship educators agree: Whichever side of the financial divide you now find yourself, the way forward for many true friendships is having more open, honest conversations about money and how it affects our relationships. These don’t have to be scary or stilted discussions, Cohen says, and they don’t have to happen in overtly formal, intimidating settings.
She recommends using a real-life example to open up a bigger conversation. For instance, if you’re buying tickets to an event, ask your friend how much money they plan to spend and why. That, in turn, can kick off a much deeper conversation about your relative finances. Cohen recommends a thoughtful line that struck me as especially empathetic and easy: “What would be helpful from me to make sure we’re on the same page about what we do together and how we spend money?’”
“There is so much that goes unsaid in friendship,” she says. “What I would want people to do is talk, to have open conversations with their friends about big transitions and big differences.”
Personally, I’ve been the friend in both positions: the richer friend and the definitely-not-rich one. I recently passed on a luxe vacation with one set of dear friends. I agonised over the decision, fantasising about suddenly finding a great flight deal or stumbling upon a can’t-miss hotel deal. After enough hours staring at travel booking sites, though, I knew my budget just couldn’t stomach it. And even though my friends understood—and of course they did! They’re good friends for a reason!—I had to hype myself up to send the “Hey guys, I’ve been thinking about our trip…” text.
Admitting I had to back out felt like a tiny failure, like I wasn’t as committed to the friendship as I had been in years past. But when another pal recently took a large pay cut as she pursued a more demanding—and lower-paying—career, I found myself on the other side of the table. After a handful of conversations about her reduced salary and inflexible schedule, I remembered my own struggle to send that text. I took the initiative to bring up the new discrepancy, suggesting we move our usual dinner-and-drinks hangouts to a lower-key TV night in. Six months later, I have to say: Both of our budgets are happier for it.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

The megamansion was built for Tony Pritzker, heir to the Hyatt Hotel fortune and brother of Illinois Gov. JB Pritzker.
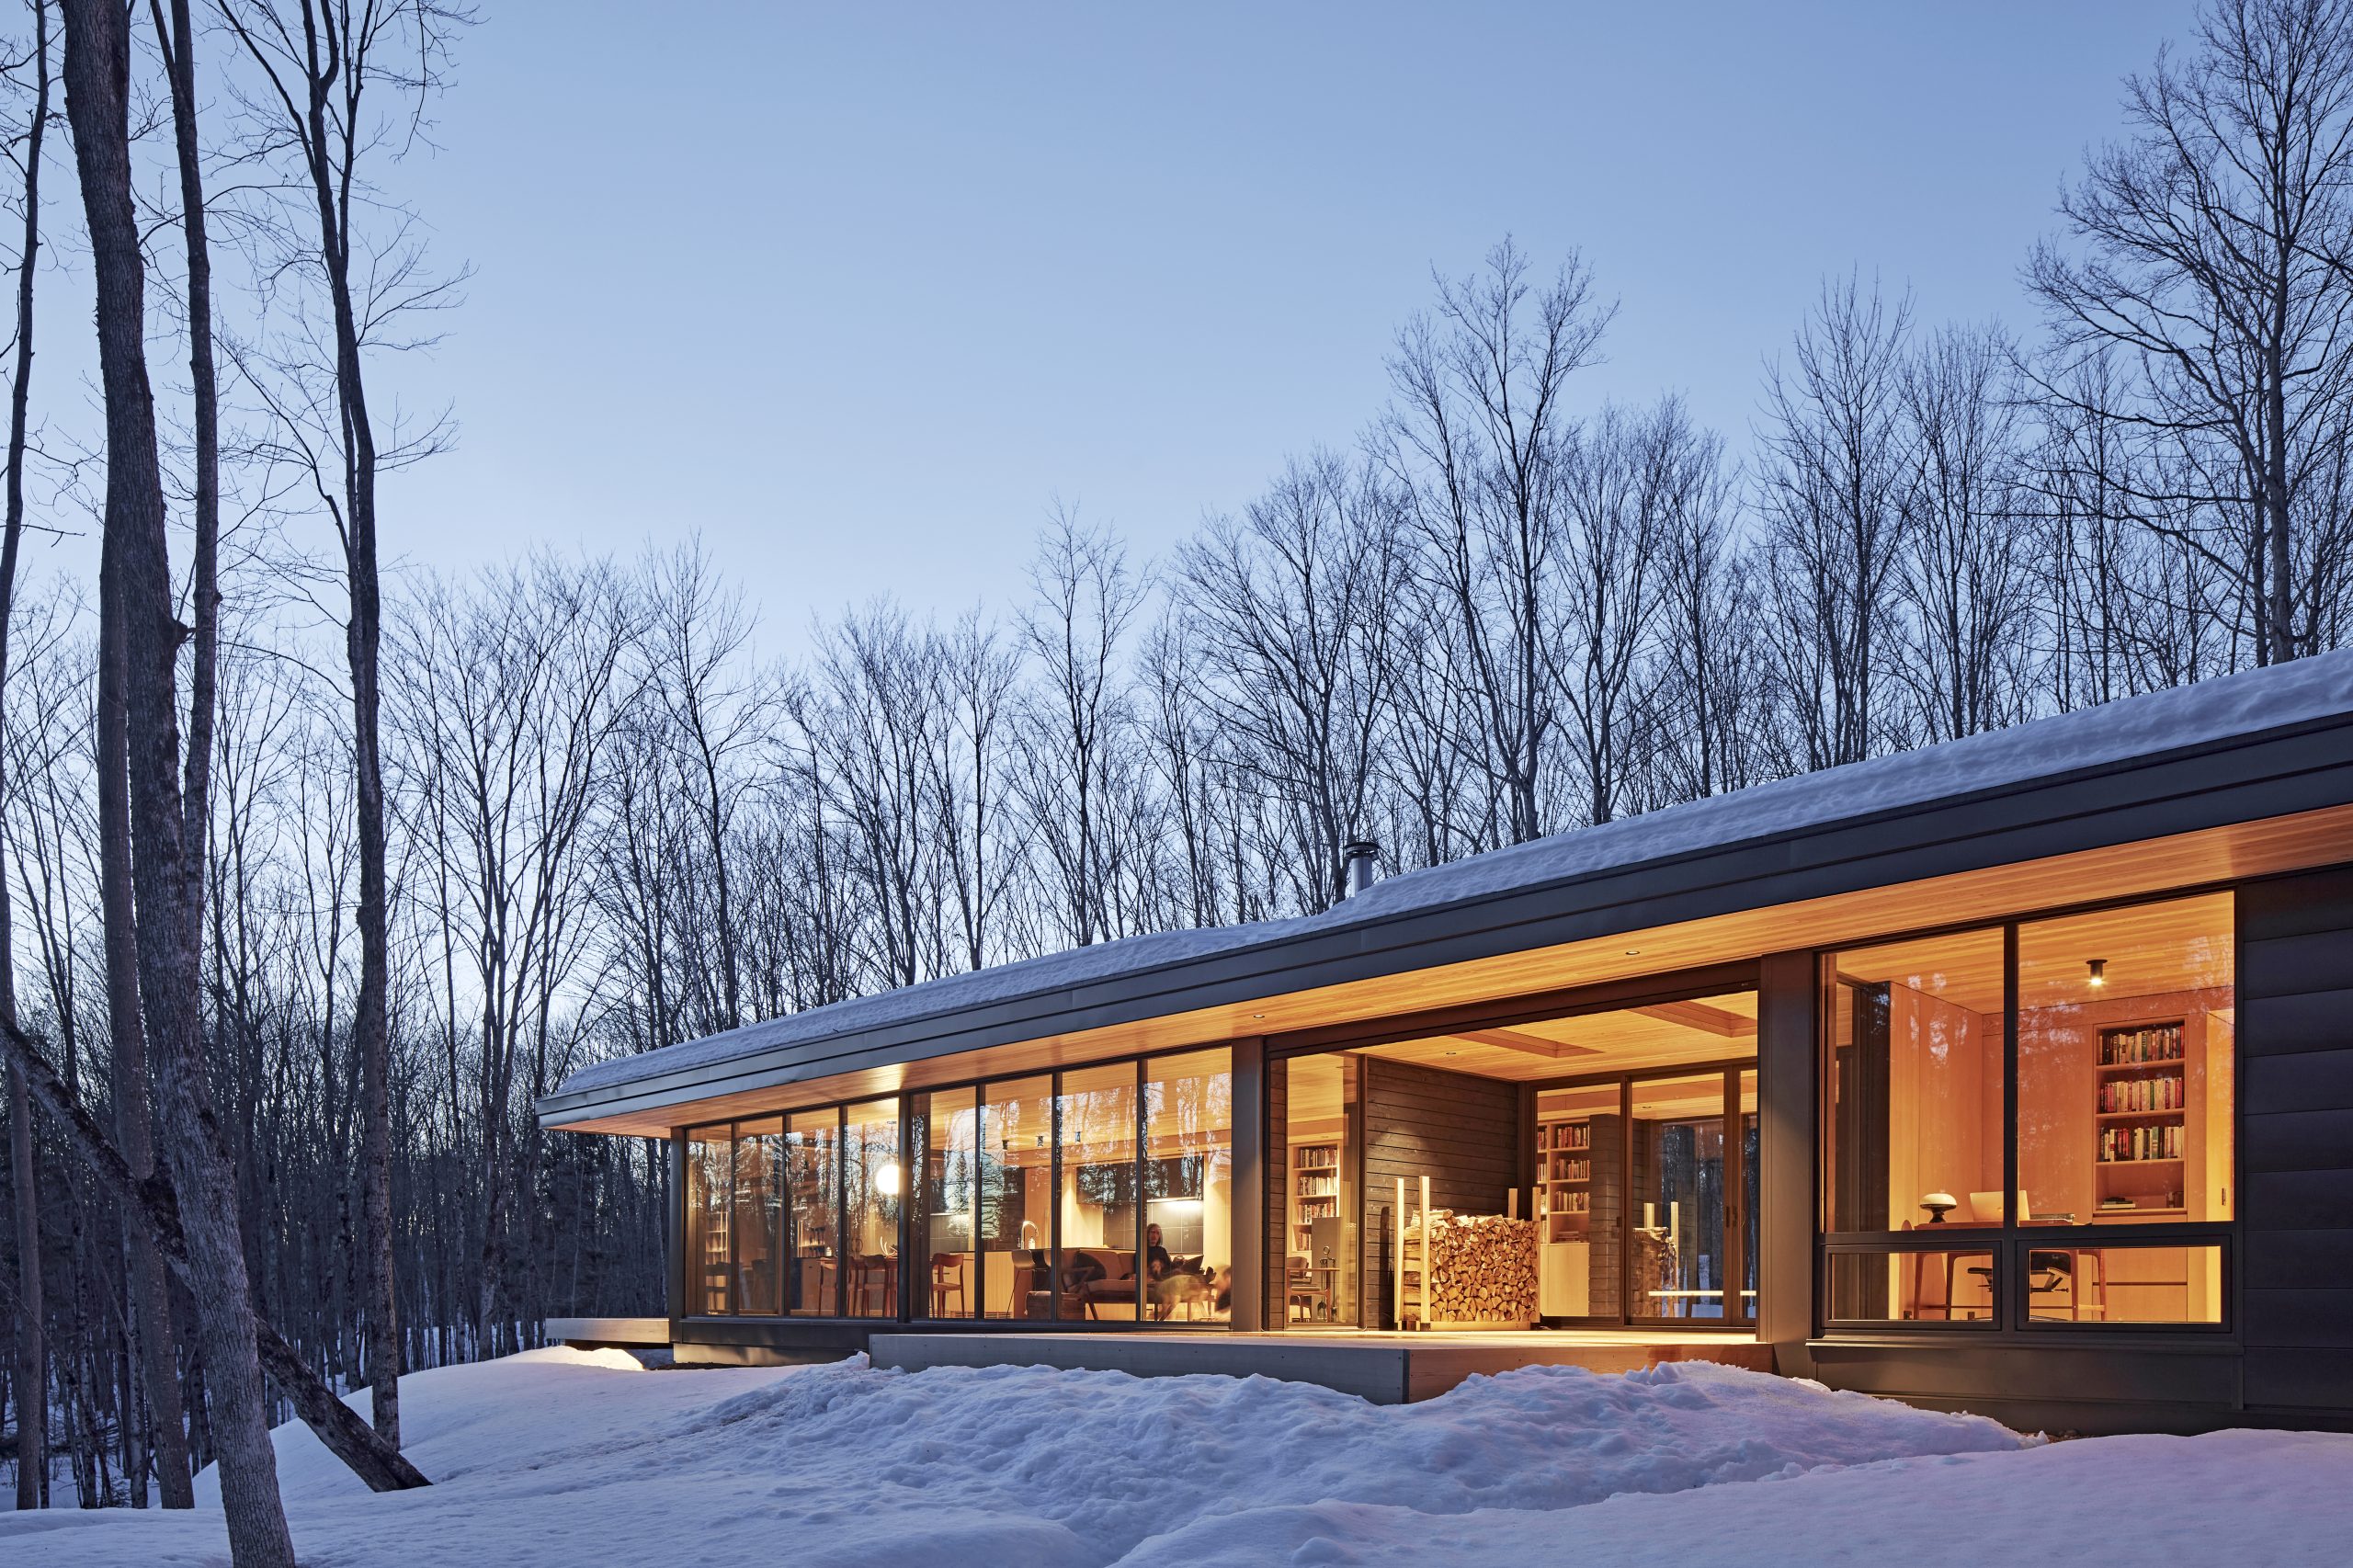
From reworked homes to remote retreats, designers are prioritising warmth and a deeper connection to landscape.