Metallica’s European Tour Showcases Renewable-Energy Big Rigs—And Their Limits
The heavy-metal band is using natural gas and vegetable oil to power its 7,200-mile journey, but filling trucks up on sustainable fuels still has a long way to go

 3 min
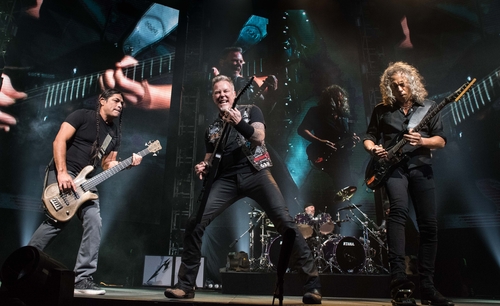
Metallica, the band that blazed a trail for thrash metal with rugged guitar riffs and relentless drumbeats, is trying to do something similar for trucks powered by sustainable fuels.
The group, a rock music mainstay since their 1986 hit album “Master of Puppets,” is looking to burnish its bona fides on social issues by using rigs powered by fuels including biomethane and vegetable oil on its European tour this summer.
Working with European truck maker Iveco, the authors of songs including “Battery” and “Fuel” (sample lyric: “Fuel is pumping engines / Burning hard, loose and clean / And I burn, churning my direction / Quench my thirst with gasoline.”) aim to show that sustainable transportation in heavy-duty trucking is possible on European highways dotted with alternative-fuelling stations.
But the trucks’ limitations and the workarounds the band’s logistics providers are undertaking on the meticulously-planned 7,200-mile journey winding through the continent from Sweden to Spain also illustrate how far trucking is from using cleaner fuels in regular operations.
“You have limited options because of the lack of the infrastructure,” said Natasha Highcroft, a director of Suffolk, U.K.-based Transam Trucking, which provides logistics for Metallica and other bands. “We use alternative fuels as and when we can, as much as possible, but until the infrastructure is there it’s very difficult.”
The trucks run on natural gas, vegetable oil, electricity and hydrogen fuel cells, and will be hauling giant video screens, lighting and instruments across nine countries.
The workhorses of Metallica’s tour will be 10 heavy-duty trucks powered by renewable natural gas—such as methane from landfills—and four heavy-duty trucks running on biodiesel or hydrogenated vegetable oil. The trucks, dramatically decked out in Metallica’s fierce logo, can travel about 1,000 miles between refuelling.
Both fuels provide a significant reduction in emissions compared with regular diesel, although emissions experts say they aren’t nearly as clean as battery-electric or hydrogen fuel cell technologies.
The tour was due to kick off this week in Munich, Germany, and over the next two months will cover the continent from Italy and Spain in southern Europe to Denmark and Norway. The longest journey between shows, from Warsaw to Madrid, covers almost 1,800 miles.
Iveco, which is providing the eco-friendly trucks for Metallica’s tour, makes both battery-electric and hydrogen fuel cell big-rig engines, the types that governments in Europe and the U.S. are trying to press on truckers as soon as possible. But because of the lack of charging and fuelling stations on the long legs between gigs, the battery-electric and hydrogen trucks will be mostly for promotional use at concerts, said Gerrit Marx , chief executive of the Italian truck maker.
Marx said Iveco wants to highlight that renewable natural gas and hydrogenated vegetable oil are “more available and ready” than batteries and hydrogen while also being “way better than fossil diesel.”
Europe has hundreds of liquefied natural gas and hydrogenated vegetable oil, or HVO, refuelling stations. A representative for British energy major Shell , which is working with Iveco on the tour, said Metallica’s low-carbon journey wouldn’t have been possible even a couple of years ago.
Shell says its customers can access HVO in five European countries and renewable natural gas in Germany and in the Netherlands. That means that when low-carbon options aren’t available, the Iveco trucks will be fuelled with regular LNG and the HVO trucks will be fuelled with regular diesel.
A Shell representative said the Metallica tour will buy carbon credits to offset “unavoidable emissions“ generated by the low-emission trucks.
U.S. companies are also using renewable natural gas and biodiesel to reduce carbon emissions. But trucking specialists say the fuels aren’t available in sufficient quantities to power the world’s fleets, which is why regulators are pushing battery-electric and hydrogen fuel cell vehicles.
Trucking executives say the costs of operating those technologies are double or triple those of diesel and that they aren’t workable in a highly-competitive, low-margin industry like trucking.
Lars Stenqvist , chief technology officer at truck maker Volvo Group , said it is important that high-profile performers like Metallica amplify the capabilities of sustainable fuels.
Truckers will only adopt the technology when customers demand it, he said, so “This is music to my ears.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.

The PG rating has become the king of the box office. The entertainment business now relies on kids dragging their parents to theatres.