Questions Potential Business Partners Should Ask Themselves
Starting a new company with somebody requires a hard conversation. Better now than later.

 5 min
You and a friend have a can’t-miss idea for a new business. You’ve got a great name, and the logo is perfect.
It is time to ask each other some hard questions.
Talking up front about tough subjects like how you work, how you deal with stress and your expectations for the business can save lots of headaches later. “Most issues are neutral when you discuss them ahead of time,” says Jane Brodsky , who ran a barre-and-spin studio with a partner for 10 years in Washington, D.C. “But in the heat of the moment, issues become personal and larger than they need to be.”
Here are crucial questions that should be settled at the start to help make the partnership succeed.
How did your family communicate?
Maybe you were raised in a family that talked through disagreements to find solutions. But maybe your partner grew up in a house where the loudest voice won. That could be a problem when issues arise in the business: Experts say that when people are under stress, they often fall back on behaviours that were imprinted at home—and different styles could clash.
At Happy Being, a company that sells nutritionally enhanced teas and drink powders, the three co-founders discussed communication style before they started the business. “We discovered that one partner gets triggered if he feels no one is listening,” says co-founder Dutch Buckley . “It goes back to an early fear of not being heard.” (For his part, co-founder Josemaria Silvestrini says that early on he “definitely needed the validation of being recognised and being right.”)
So, the three work at making sure everyone has a say in meetings, and they made a rule that no one’s work is ever belittled. On the flip side, when someone on the team accomplishes something, someone else on the team draws attention to it.
What does success look like to you? And failure?
While these may seem obvious—like, the business either succeeds or fails—everyone’s definition is different, and they are surprisingly specific. Certainly, monetary goals or anything that can be enumerated will help partners envision each other’s goals. Is one looking to grow slowly with customers and suppliers in the community and get to better than break even after three years, while the other wants to be cash-flow positive in year one and scale quickly to sell the business to a larger entity after 10 years? There’s a lot of success and failure in between those two outcomes, depending on your perspective.
Silvestrini of Happy Being recommends hashing it out together on the whiteboard until everyone agrees on an explicit definition of success for the company. “Hopefully, it’s an easy 10-minute conversation,” he says. “Because if founders have different objectives, the boat is going nowhere.”
What does everyone bring to the table?
It is crucial to discuss what each partner is contributing to the partnership in terms of expertise, experience, network and money. Kathryn Zambetti , an executive coach specialising in founder relationships, recommends taking an honest strengths-and-weaknesses inventory of yourself and your partner and then discussing what you both bring to the table. The exercise will help delineate which responsibilities naturally suit each partner, and it will highlight areas that will require additional work or outsourcing.
The clearer the roles can be defined, the better. If you are opening a bakery, you and your partner shouldn’t both be good at just making bread. Someone needs to handle marketing, suppliers, leases and licensing, financials and hiring and managing employees.
Why are you doing this?
You and your partner need to be in complete alignment on your motivations. Does this venture need to support your family or merely add to your vacation fund? Are you doing it to prove your father or your high-school econ teacher wrong? Any answer other than unfailing commitment to the mission or the product is a red flag.
“Your north star has to be something bigger than money to succeed,” says Buckley. “People will go through things that test them, but if money is the only motive, that won’t be enough.”
What pushes your buttons?
Just like in a marriage, you want to know best how to support and protect your business partner. Understanding what puts each of you in a fight-or-flight mode can be key to getting the best out of each other.
Do you need to be consulted on all decisions, or just major ones? Do you need to be recognized as the leader and sit at the head of the table? Do you fear having to downsize your home if the business fails?
What does your workday look like?
Does a day at the office mean working 9 to 5? Can the work be done remotely and on your own time? If you work well at night and need rapid responses to questions, is it a problem having a partner whose phone goes on “do not disturb” every evening at 7? Having the conversation and understanding expectations is key.
When Buckley started Happy Being, the team learned that one of the partners got up very early. “I had to tell him, ‘We don’t want 6 a.m. calls.’ ”
Do you like taking gambles?
A penchant for lottery tickets, Las Vegas gambling or high-adrenaline activities like skydiving shows a potential partner’s tolerance for risk and whether that aligns with your own. There will be countless decisions early on in a business concerning risk, and the partners need to be on the same page.
So ask about it. You go into the venture planning and hoping for success, but how much money or time is your partner willing to lose if it doesn’t succeed? How much of their parents’ or in-laws’ money would they bet on the partnership?
Is the business more important than the friendship?
Many business partners start as friends. But would you each be willing to give priority to making the right decision for the business, even if it means possibly hurting the friendship? Would you each be capable of letting the other one go if it was better for the company? Most advisers recommend choosing a partner who has a common business goal and letting the friendship build from that, rather than trying to build a partnership on top of a strong friendship.
“Your business partner will be one of your most intense relationships, but it shouldn’t fulfill every role in your life,” says Amy Jurkowitz, entrepreneur and co-founder of branding adviser Bread Ventures. “You need to be compatible in how much energy you will both put into the business.”
If the partnership doesn’t work out, how will it end?
A co-founder relationship is a binding agreement with financial and emotional repercussions, just like a marriage. But starting a business has the added stress of having the company—the baby—arrive on day one. If there is a divorce, who gets custody?
The more specific you can be about potential breakups, the better. If you are both putting capital in at the start, would you expect to get that out if you exited? What if, several years in, one partner can’t continue to struggle without a regular paycheck and leaves—and the next year the company finally turns a profit or is bought by another company? Would the partner who left get a share of the money?
These discussions should help make it clear that the survival of the company—and not the partnership or the friendship—is the ultimate goal. Those who have been through a business breakup recommend involving a third party to help sort through these issues at the outset.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A&K Sanctuary unveils Kitirua Plains Lodge, a sustainability-focused luxury property shaped by landscape, local craft and contemporary safari architecture.
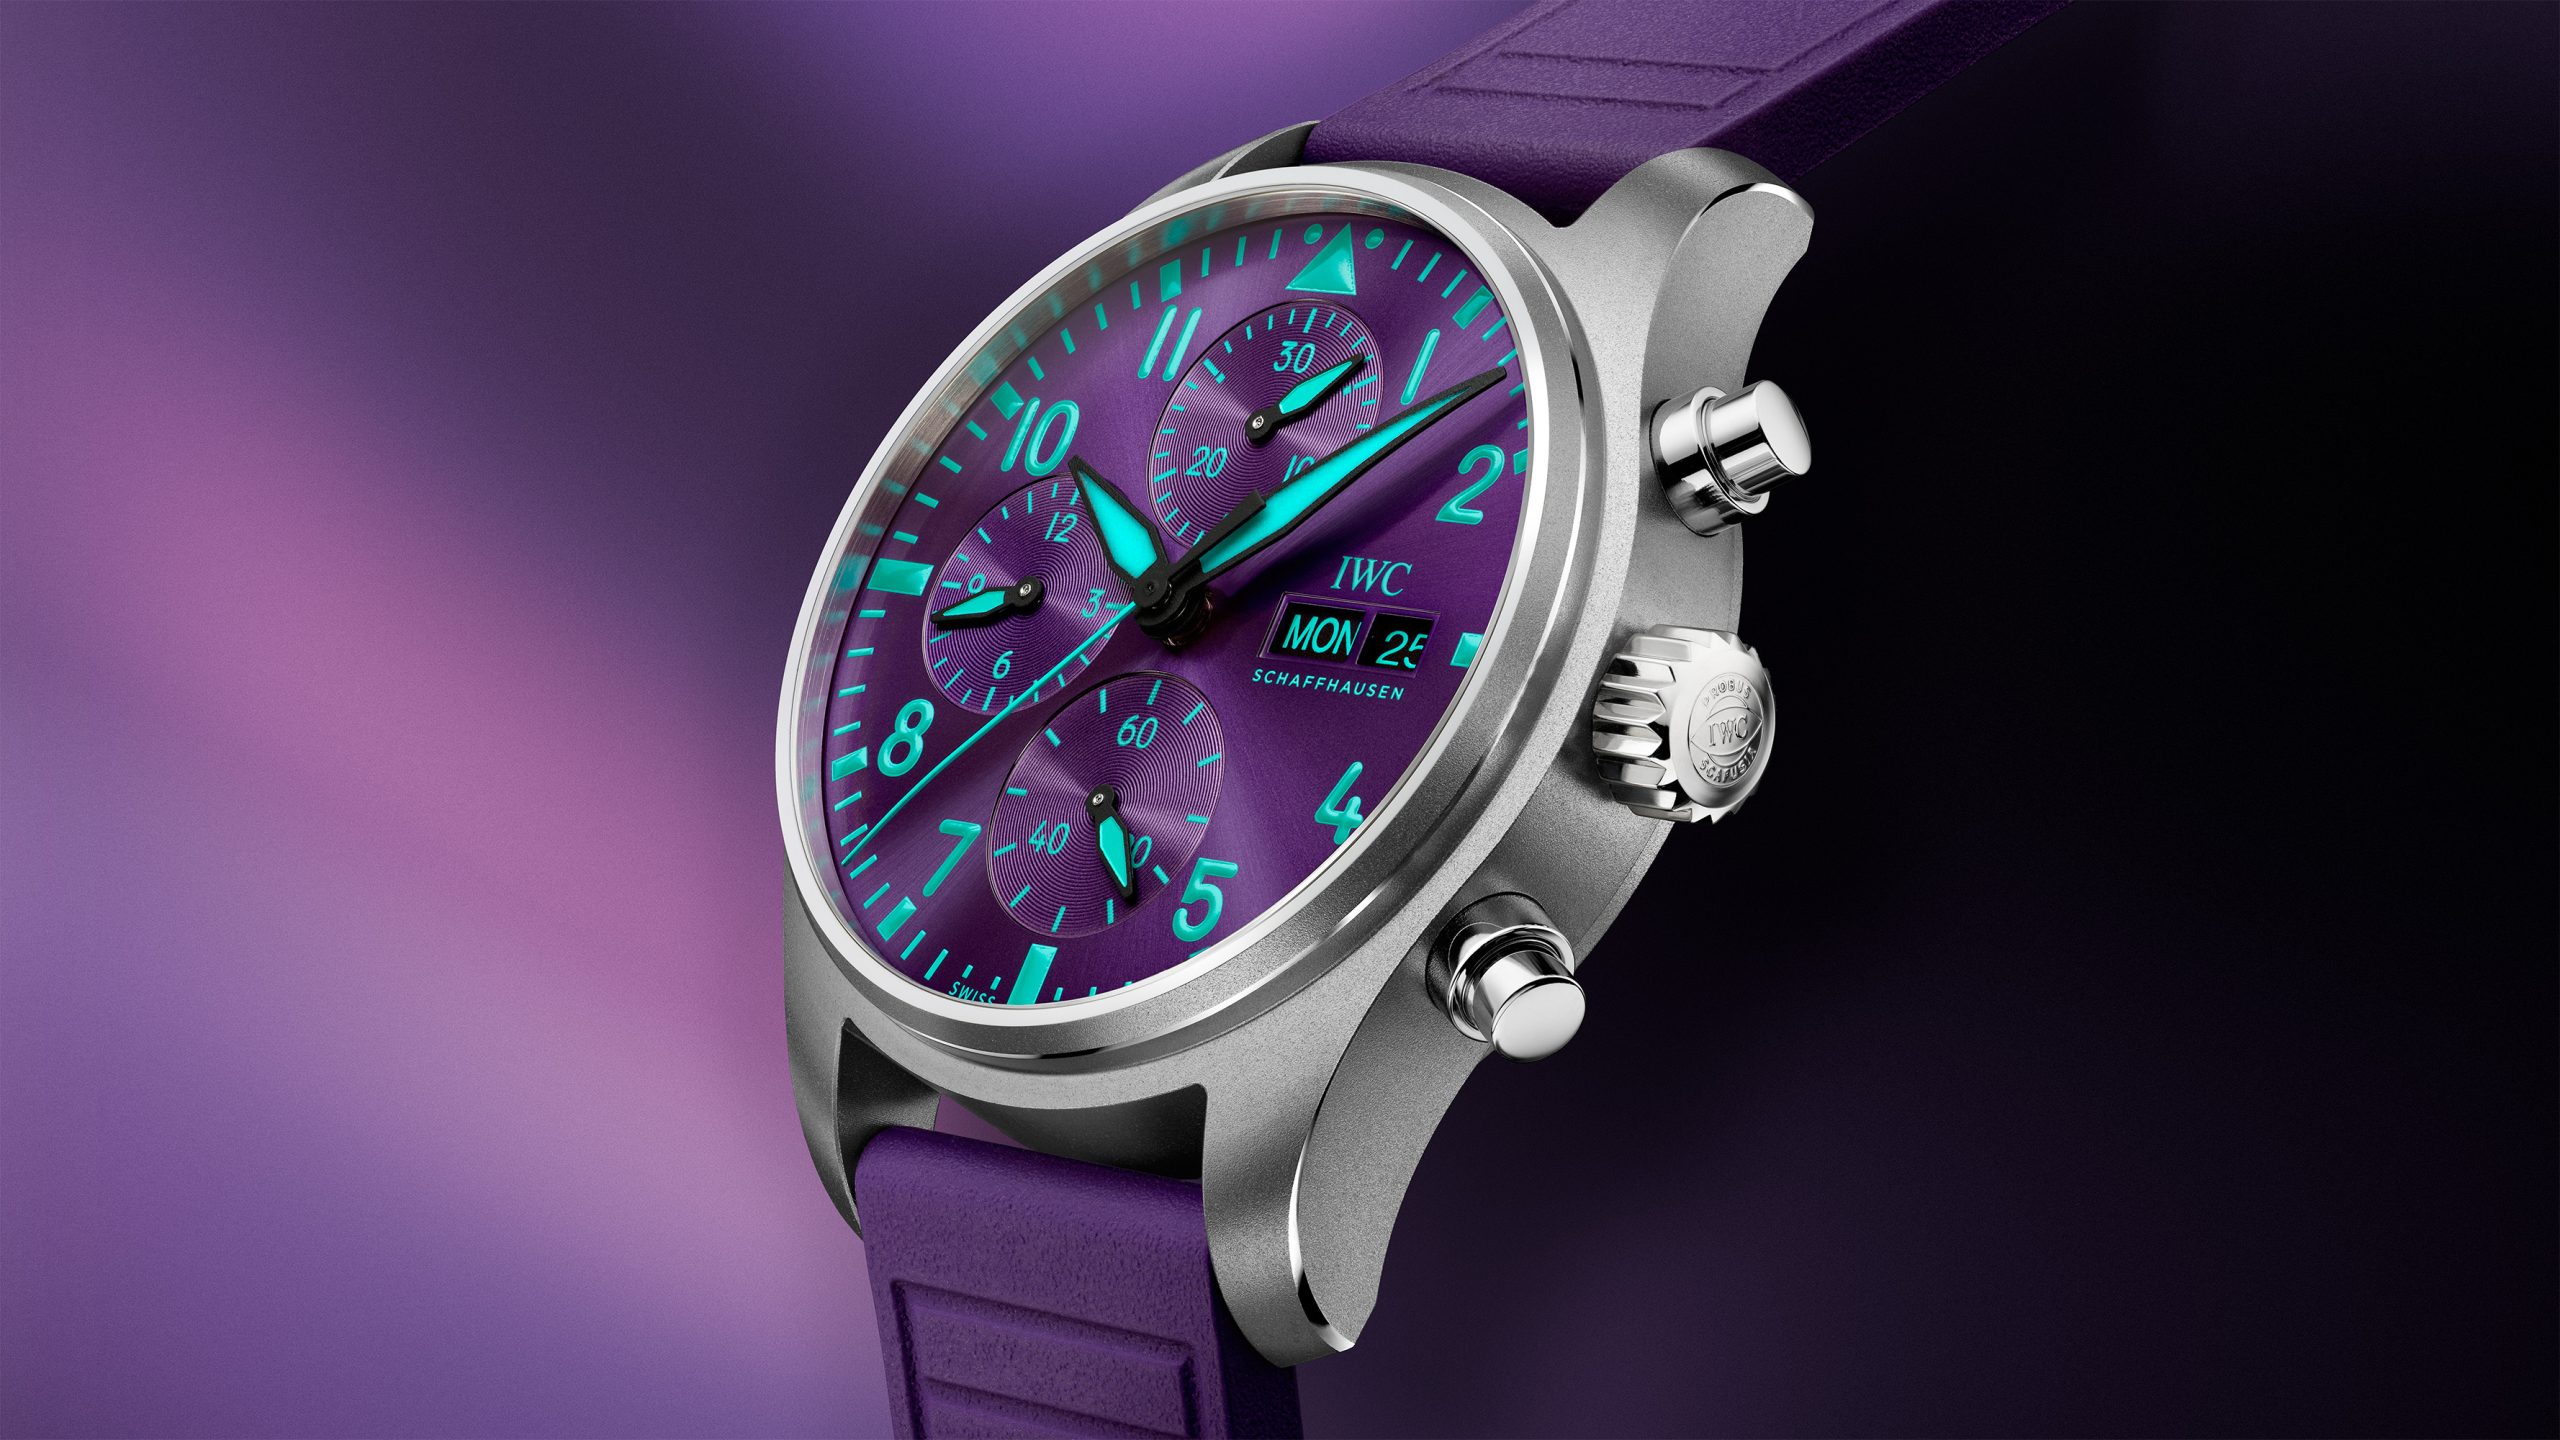
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”