Sam Altman’s Counter-Rebellion Leaves OpenAI Leadership Hanging in the Balance
AI startup’s ousted chief executive tries to negotiate his return

 3 min
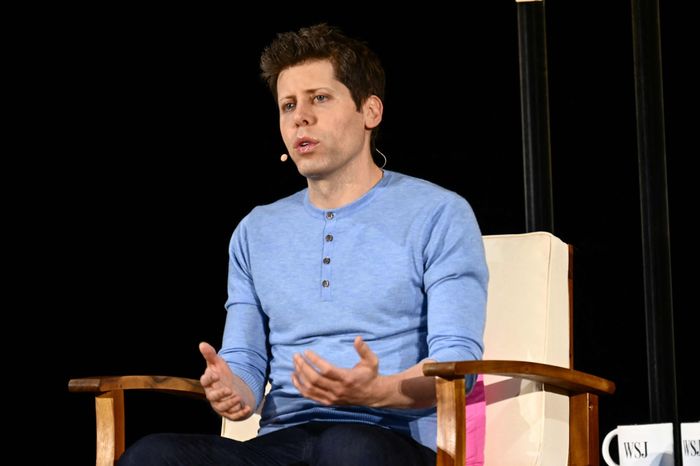
SAN FRANCISCO—Two days after Sam Altman was ousted from OpenAI, he was back at the company’s office, trying to negotiate his return.
The former chief executive officer entered with a guest badge on Sunday and posted on X: “first and last time i ever wear one of these.”
The leadership of the company that created the hit AI chatbot ChatGPT remained unclear Sunday, as investors and many employees pushed over the weekend to restore Altman. He has been engineering a countercoup to retake control of one of Silicon Valley’s most valuable and high-profile startups.
The abrupt shake-up at OpenAI turns on one of the oldest tales in Silicon Valley: a breakup between a founder and his board.
But in this case it was a very particular kind of founder—the face of Silicon Valley’s artificial-intelligence revolution—and a very particular kind of board, which was tasked with making social good a priority over profit. The rupture threatens the future of the company and the billions of dollars investors had put into it.
Altman has also been considering starting his own venture, potentially with talent from OpenAI. He is pursuing both tracks: On Sunday morning, Chief Technology Officer and interim CEO Mira Murati sent a note to staff saying Altman would be returning to the San Francisco office later that day as discussions to reinstate him continued.
Over the weekend, Altman made clear to his allies that if he does return, he wants a new board and governance structure, people familiar with the matter said.
Two days after the board fired Altman, different explanations persisted for the initial firing. The board said Friday it pushed out the CEO after it concluded he hadn’t been candid with the company’s directors. It didn’t elaborate.
Over the weekend, people close to Altman said the ouster had more to do with disputes around the safety of the company’s artificial-intelligence efforts and a power struggle with one co-founder and board member in particular, Ilya Sutskever.
On Sunday, a person familiar with the board stood by the board’s statement citing Altman’s lack of candor. This person said there was no single precipitating incident but rather a mounting loss of trust over communications with Altman that led it to remove him as CEO. The person declined to offer examples.
The ouster from OpenAI wasn’t the first time Altman was asked to leave a company. Several years ago, senior leaders at the venture firm Y Combinator asked Altman to step down as president after mounting concerns about the time he was spending on his other business endeavours, including at OpenAI, according to investors briefed by the venture firm’s executives—information not previously reported.
In addition to OpenAI, Altman recently hatched plans for two new business endeavours. He enlisted Apple’s former chief design officer, Jony Ive, to create a consumer hardware device. And he recently spent weeks in the Middle East gauging investor interest for a new startup aiming to create low-cost chips needed to train OpenAI’s artificial-intelligence models, people familiar with the matter said.
It is unclear whether those efforts, or the communication around it, played into Altman’s dismissal. Bloomberg earlier reported on the new chips venture. The Information and the Financial Times earlier reported the new Ive venture.
With his firing from OpenAI, Altman quickly got the upper hand in terms of public messaging. The board didn’t use a communications or law firm in its dealings, people familiar with the board said, expecting that the OpenAI team would help them. But Altman had loyalty from investors and employees.
The board ended up isolated as social media exploded with shock and support for Altman. His largest backers, including Microsoft and Thrive Capital, immediately on Friday began pressing for Altman’s position to be restored. Microsoft CEO Satya Nadella began working with Altman that evening on his next steps, people familiar with Altman said.
Despite his business success, Altman had been losing the support of a board whose constituents changed as the company’s commercial efforts powered ahead. It was a board structure that he had ironically helped create and publicly promoted as he encountered questions about AI safety.
Before Friday’s dust-up, the board consisted of six people, including Altman. Then, it abruptly removed Greg Brockman, OpenAI’s president and a close friend of Altman’s, and voted to oust Altman. None of the four board members remaining were affiliated with the company’s big investors. It isn’t clear whether the vote was unanimous.
The board that took the action was down from the nine seats it had earlier in the year and lacked at least one key prior Altman backer. Earlier this year, Reid Hoffman, a Silicon Valley venture capitalist with a long history of supporting Altman, stepped down after starting a rival company to OpenAI.
Separately, Shivon Zilis, a tech executive at Elon Musk’s brain-implant startup Neuralink, and Will Hurd, who started a presidential campaign, also left this year.
The board had been working to fill those empty seats for months, though the process stalled, according to a person familiar with the matter.
The other four directors are: Adam D’Angelo, a former Facebook executive and the founder of the question-and-answer website Quora; Tasha McCauley, an adjunct senior management scientist at Rand; Helen Toner, a director at a Washington nonprofit; and OpenAI’s chief scientist, Sutskever.
Altman this weekend was furious with himself for not having ensured the board stayed loyal to him and regretted not spending more time managing its various factions, people familiar with his thinking said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
When the Writers Festival was called off and the skies refused to clear, one weekend away turned into a rare lesson in slowing down, ice baths included.

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.