Social-Media Influencers Aren’t Getting Rich—They’re Barely Getting By
Platforms are paying less for popular posts, brands are pickier about partnerships and a possible TikTok ban looms

 9 min
Many people dream of becoming social-media stars like YouTube’s MrBeast or TikTok’s Charli D’Amelio . But for most who pursue careers as content creators, just making ends meet is a lofty goal.
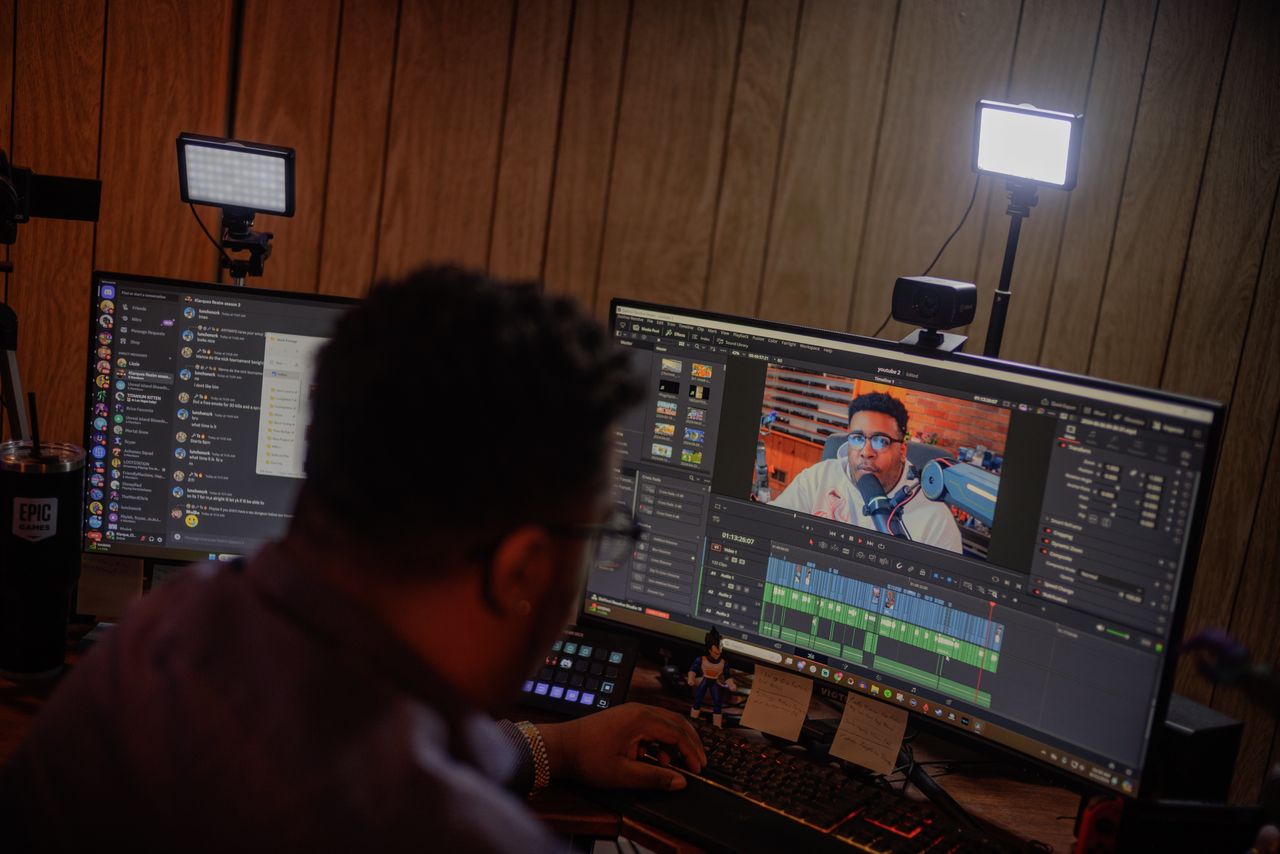
Clint Brantley has been a full-time creator for three years, posting videos on TikTok, YouTube and Twitch where he comments on news and trends related to the online game “ Fortnite .” Despite having more than 400,000 followers, and posts that average 100,000 views, his income last year was less than the median annual pay for full-time U.S. workers in 2023—$58,084, based on Bureau of Labor Statistics data .
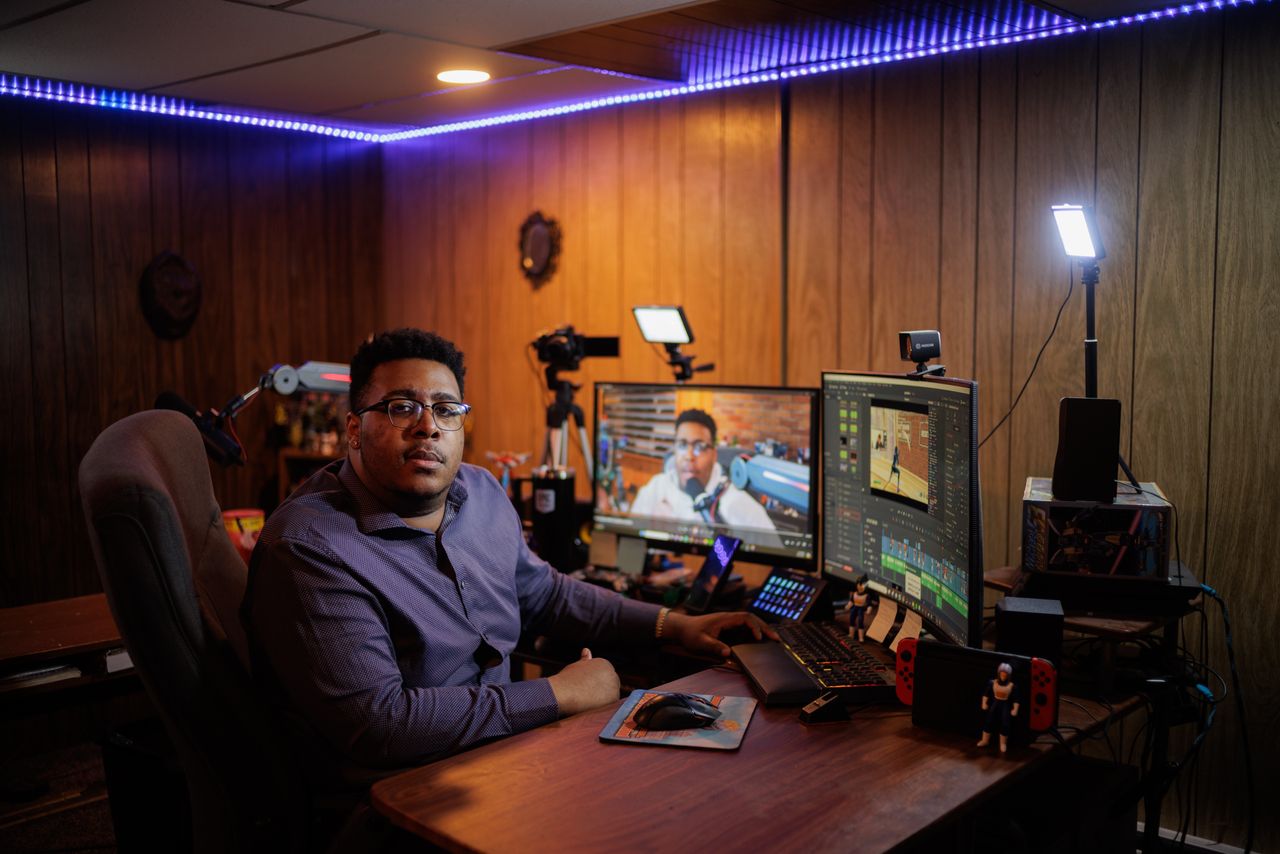
The 29-year-old is hesitant to commit to an apartment lease because the money he gets, mainly from online tips and sponsorship deals, arrives randomly and could vanish at any moment. For now, he’s living with his mom in Washington state.
“I’m vulnerable,” he says.
Earning a decent, reliable income as a social-media creator is a slog—and it’s getting harder. Platforms are doling out less money for popular posts and brands are being pickier about what they want out of sponsorship deals. The real possibility of TikTok potentially shutting down in 2025 is adding to creators’ anxiety over whether they can afford to stick with the job for the long haul.
Few overnight sensations
Hundreds of millions of people around the globe regularly post videos and photos to entertain or educate social-media users. About 50 million earn money from it, according to a 2023 report from Goldman Sachs . The investment bank expects the number of creator-earners to grow at an annual rate of 10% to 20% through 2028, crowding the field even further. The Labor Department doesn’t track wages for these creators, also known as influencers.
It can take months or years to earn money as a creator, often through a combination of direct revenue from social-media platforms, sponsorship deals, merchandise sales and affiliate links. But those who stick with it eventually see some returns, surveys show. Creators say that’s because you can learn what kind of posts most resonate with an audience, which can lead to more followers and, in turn, more moneymaking opportunities.
But money doesn’t mean big bucks . Last year, 48% of creator-earners made $15,000 or less, according to NeoReach, an influencer marketing agency. Only 13% made more than $100,000.
The gap reflects multiple factors, including whether creators work full- or part-time, the kind of content they put out and when they started. People who jumped into the space during the height of Covid-19 lockdowns—and who focused on a niche such as fashion, investing or lifestyle hacks—say they benefited from the surge in social-media use during that time.
A small number of creators shot to fame, propelling the occupation to the top of career wish lists for many teens (and adults). But behind the scenes, creators say the job is gruelling. They need to constantly produce compelling posts or risk losing momentum. They spend their days planning, filming and editing posts while also working to make inroads with advertisers and interacting with fans.
“It is a lot more work than most people realise,” says Emarketer analyst Jasmine Enberg. “Creators who make a living doing it have been at it for many years. Most are not overnight sensations.”
Like other self-employed professionals, creators don’t get paid time off, healthcare benefits, retirement contributions and other perks that companies typically provide for their workers. That reality, coupled with stubbornly high inflation and mortgage rates , is making it more difficult to get by as a creator.
“Everything is more expensive, especially groceries,” says Jason Cooper of Mobile, Ala.
A few years ago, Cooper dreamed up a sassy sock puppet named Sock Cop, who cracks dad jokes in live and recorded videos for TikTok and Twitch . He currently makes $500 to $600 a month, almost entirely from tips.
He thinks he could probably haul in a lot more if he went full-time. But with no guarantee, the 37-year-old father doesn’t want to quit his marketing job and risk losing health coverage. He now spends a few hours in the evening and on weekends on Sock Cop. If he had more time, he would feel the need to constantly make videos.
“You’ve got to feed the beast,” says Cooper.
Shrinking platform payouts
TikTok’s $1 billion creator fund, which ran from 2020 to 2023, doled out money to eligible creators for posting to the platform. Others joined in . YouTube’s TikTok competitor, Shorts, allowed creators to earn anywhere from $100 to $10,000 a month with its temporary fund. Instagram’s Reels Play bonus program rewarded creators with fluctuating payouts. Snapchat ’s Spotlight rewards program gave $1 million a day to the platform’s top creators.
Today, the platforms have revamped or completely changed how they pay creators—doing away with their funds.
Qualifications for TikTok’s current rewards program include having an account with at least 10,000 followers with a minimum of 100,000 views in the past month. Instagram is currently testing a seasonal, invitation-only program that rewards creators for sharing Reels and photos.
YouTube debuted an ad-revenue share model last year, in which qualifying creators with more than 1,000 subscribers and 10 million public Shorts views in the past 90 days receive 45% of revenue from ads that occur between posts. Snapchat has a program that gives creators who meet certain criteria, such as having at least 50,000 followers and 25 million monthly views, a portion of the ad revenue that appears between Stories. Its Spotlight program also continues to dole out money to creators.
Creators who opt into these programs or bonuses aren’t guaranteed a significant payday.
Yuval Ben-Hayun originally became popular on TikTok in 2020 because of his posts about the word-puzzle game Wordle. The 29-year-old New Yorker eventually expanded into linguistic and other education content, and by early 2023, was able to support himself and his bills of over $4,000 a month.
TikTok had closed its fund by then but was testing its creator rewards program. Ben-Hayun said in March he received about $200 to $400 per million views, and it’s steadily declined since then—even as his follower count reached 2.9 million.
The followers are still there, but the money isn’t. He recently hit a new low, receiving only $120 for a video with 10 million views.
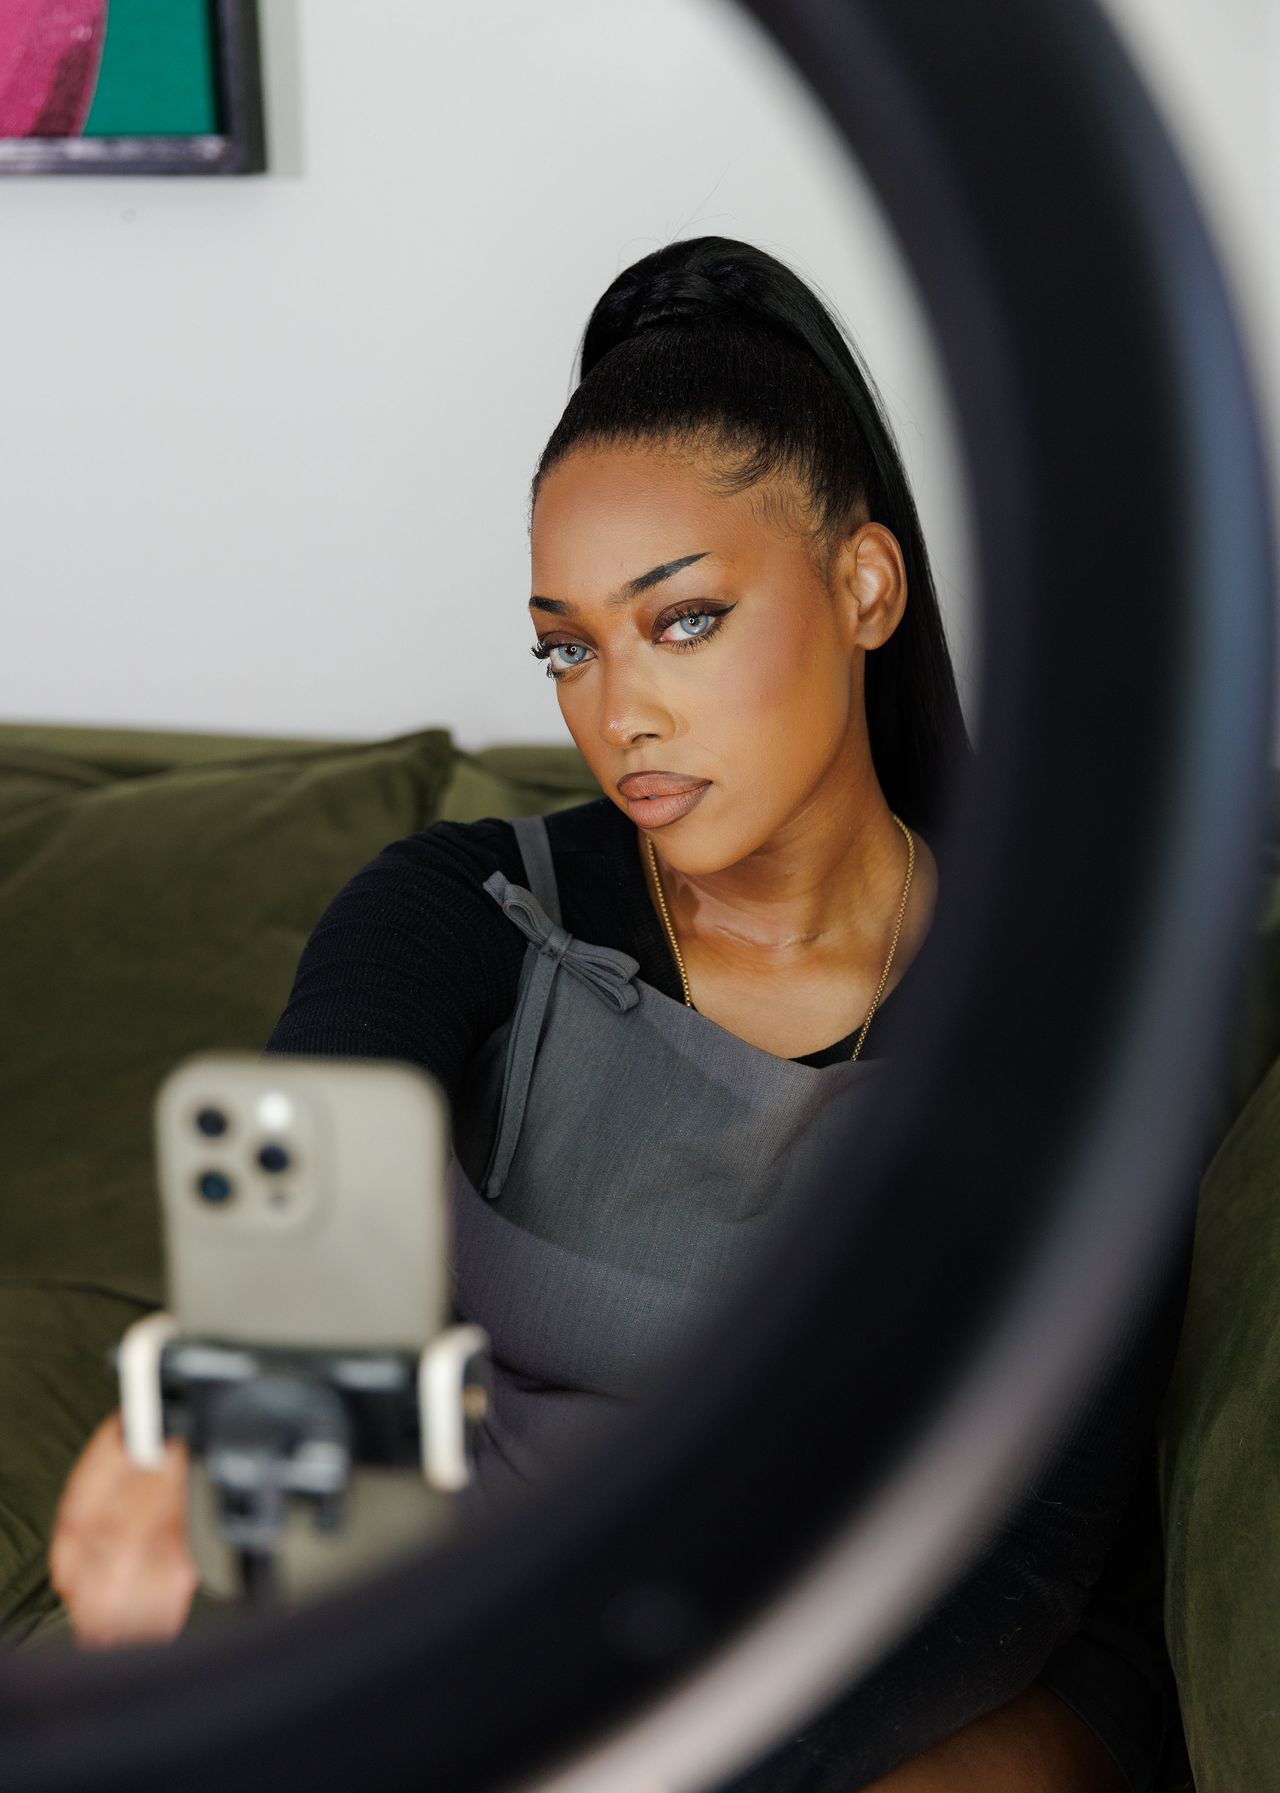
Danisha Carter is frustrated that TikTok and other platforms sold the idea of content creation as a job, but later withdrew the financial incentives. Thanks to creators’ efforts, she says, consumers are now hooked on social feeds, bringing the platforms billions of dollars in annual revenue.
The 26-year-old has 1.8 million TikTok followers, and her posts about beauty and exercise, along with opinions on topics ranging from dating to online bullying, regularly receive hundreds of thousands of views. TikTok has paid her a total of $12,000, Carter says. She sells merchandise for additional income, bringing in about $5,000 last year.
“Creators should be paid a fair percentage based on what the apps are making off creators,” says Carter. “There should be more transparency into how we’re paid, and it should be consistent.”
A TikTok spokeswoman declined to comment.
YouTube said it paid more than $70 billion to creators, artists and media companies in the past three years, and more than 25% of channels in the ad-revenue share model are now making money through it. “We remain committed to putting our full energy into what matters most for our creators, viewers and advertisers,” a spokeswoman said.
A future without TikTok?
Many creators and advertisers credit TikTok, which pioneered the short-form video genre, with driving stronger engagement than its industry peers. TikTok has gained more than 170 million users in the U.S. since its launch in 2016—including, Pew Research Center says, a third of American adults. They spend an average of 78 minutes a day on the app, according to market-intelligence firm Sensor Tower.
TikTok may not be available in the U.S. for much longer, at least not in its current form. In April, President Biden signed a bill into law that will force a sale or ban of the app by Jan. 19, 2025. U.S. lawmakers have expressed worries that TikTok poses a national security risk. TikTok’s parent company, Beijing-based ByteDance, has said it can’t and won’t sell its U.S. operations by the deadline.
ByteDance sued the U.S. government, alleging the new law violates its First Amendment rights. Several U.S. creators also sued. The U.S. Court of Appeals for the District of Columbia Circuit will hear arguments in September for both cases.
“To lose TikTok would be kind of devastating,” says Brandon Granberg , a 31-year-old creator from Bayville, N.J., known for interacting with strangers in public places in silly ways.
Granberg struggled for years to attract viewers on the app before one viral post two years ago took his follower count from 5,000 to more than one million. Recently he made $1,000 from a TikTok program that launched last year called TikTok Creative Challenge, which allows creators to earn money by making video ads for brands that don’t appear on their personal profiles. He also earned $2,800 for producing four TikTok videos promoting a website for people with foot fetishes. Granberg says he found it creepy, but did it because he needed the money.
While he hasn’t landed many other sponsored posts, he’s grown his income significantly by making marketing videos for small businesses over the past year. Most clients find Granberg on TikTok. “If it gets banned, it will definitely hurt me,” he says.
Changing tastes and algorithms
This year, U.S. social-media creators as a whole are expected to make $13.7 billion, according to Emarketer. The research firm projects the majority of that—$8.14 billion, or 59%—will come from brand sponsorships.
Advertisers have always led in compensating creators, paying out far more money than the social-media platforms and fans who buy merchandise or dole out tips. But these days, advertisers expect more from creators than just large followings, according to agency and talent representatives. They want to see evidence of strong engagement in the form of saved and shared posts, plus the demographics of creators’ audiences.
“Brands are looking at metrics that are far less predictable for creators and also very difficult to price yourself on,” says Sarah Peretz, a business-strategy consultant in Los Angeles who helps creators negotiate partnerships and deals with advertisers.
Some brands are more controlling than in the past, says Sarah Steele, a 34-year-old creator in Tulsa, Okla., who started making TikTok videos about being a working mom in 2020. “Now it’s, ‘We’re paying you and this is what we want you to say.’ ”
Earlier this year, Steele says an advertiser insisted she cite legal disclaimers in a series of sponsored Instagram posts. “It felt like I was reading off a teleprompter,” she says. “As a consumer it even turned me off to the brand a little bit.”
Creators, meanwhile, are having a tougher time attracting viewers, thanks to algorithm changes and other factors beyond their control. And while more advertisers are looking to partner with creators than in the past, “increased activity leads to increased competition,” says Peretz.
Another change is that advertisers now prefer to work with just a handful of creators on long-lasting deals rather than experiment with several on one-off projects, says Jess Hunichen, of Shine Talent Group.
Hunichen co-founded the talent-management agency in 2015, when TikTok didn’t exist and influencer marketing was still relatively new. Back then, an average deal size between an influencer and brand was usually below $1,000. Now, the average deal per campaign is around $10,000, she says.
Worth the hustle
Ronit Halmos of Los Angeles began making TikTok videos earlier this year that she describes as quick-reviews of restaurants, bars and more “with some sass and attitude.”
The 27-year-old, a full-time technology recruiter, recently landed her first advertiser deal. A kombucha brand asked her to make a 30-second post featuring her take on a line of flavours. Though it ended up getting less attention from viewers than her usual fare, she made $1,500 from about 30 minutes of work.
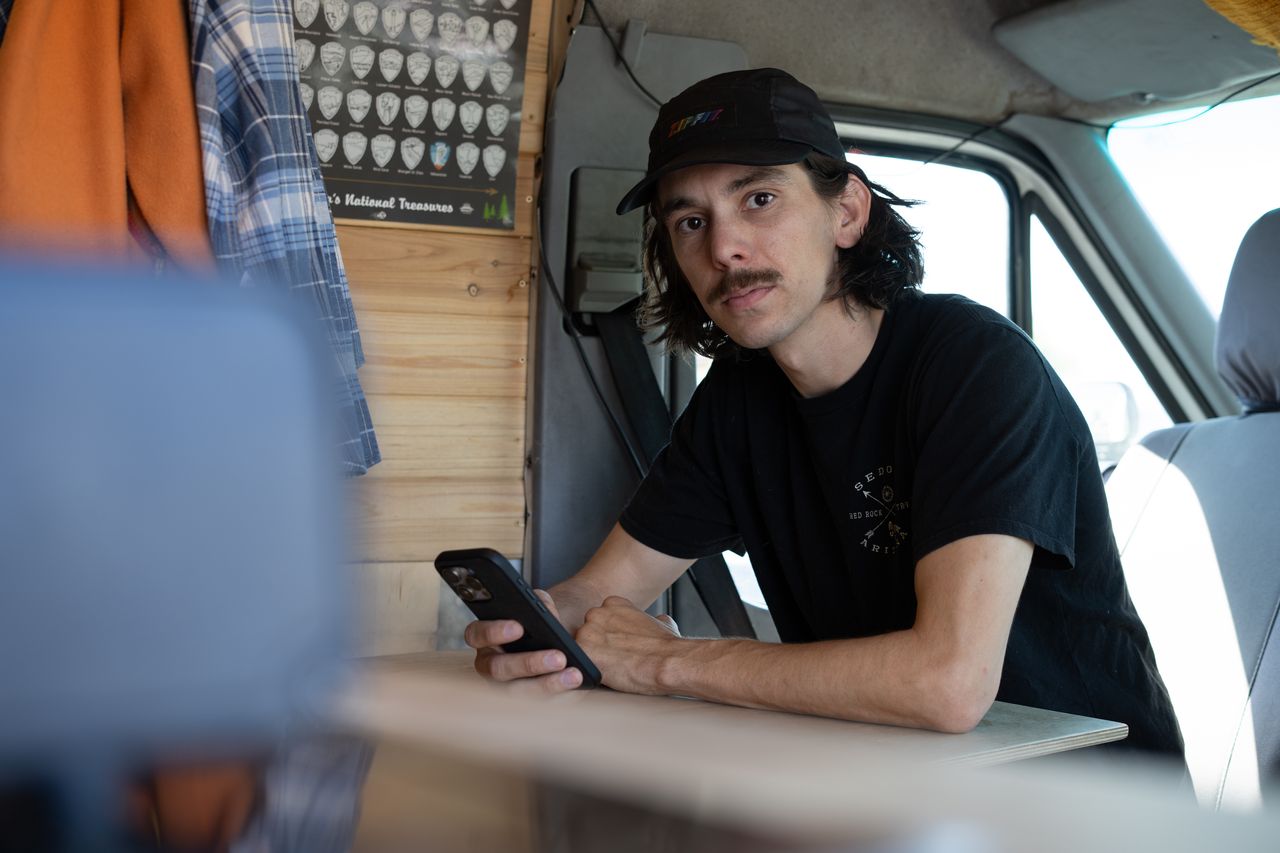
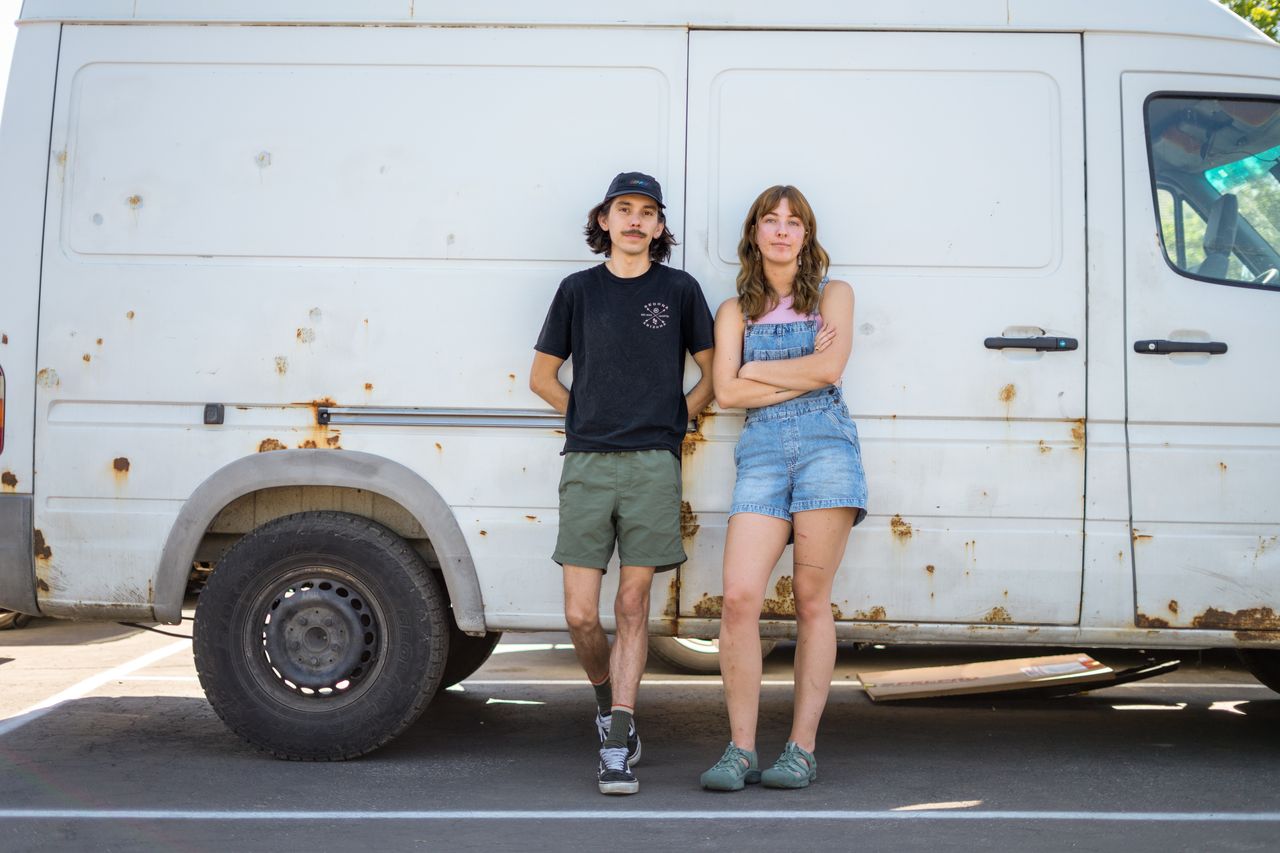
Tyler Haven , a 27-year-old traveling around the Pacific Northwest, charges $250 to $300 to make promotional videos that brands can post to their own social channels, and around $1,200 for posts that appear on either his Instagram account with more than 41,000 followers or his TikTok account with more than 10,000 followers.
Since January, he’s been posting videos documenting his “van-life” with his wife, Oak Haven: Their primary residence is a fully paid, fully decked-out 2004 Mercedes Sprinter T1N.
Haven said it’s been easy to grow his following organically. He believes it’s because his posts don’t depict some unattainable, picture-perfect life.
He quit his job in June to pursue full-time content creation.
“Even if I were to make $2,000 a month, which is absolutely nothing—that’s less than most people’s rent—I could live on that,” Haven says.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A long-standing cultural cruise and a new expedition-style offering will soon operate side by side in French Polynesia.

ABC Bullion has launched a pioneering investment product that allows Australians to draw regular cashflow from their precious metal holdings.