




Inside ‘Billionaires’ Bluff’: Why Paradise Cove Keeps Drawing the Superrich
Residents of this Malibu enclave include Marc Andreessen, Laurene Powell Jobs and Beyoncé and Jay-Z

 5 min
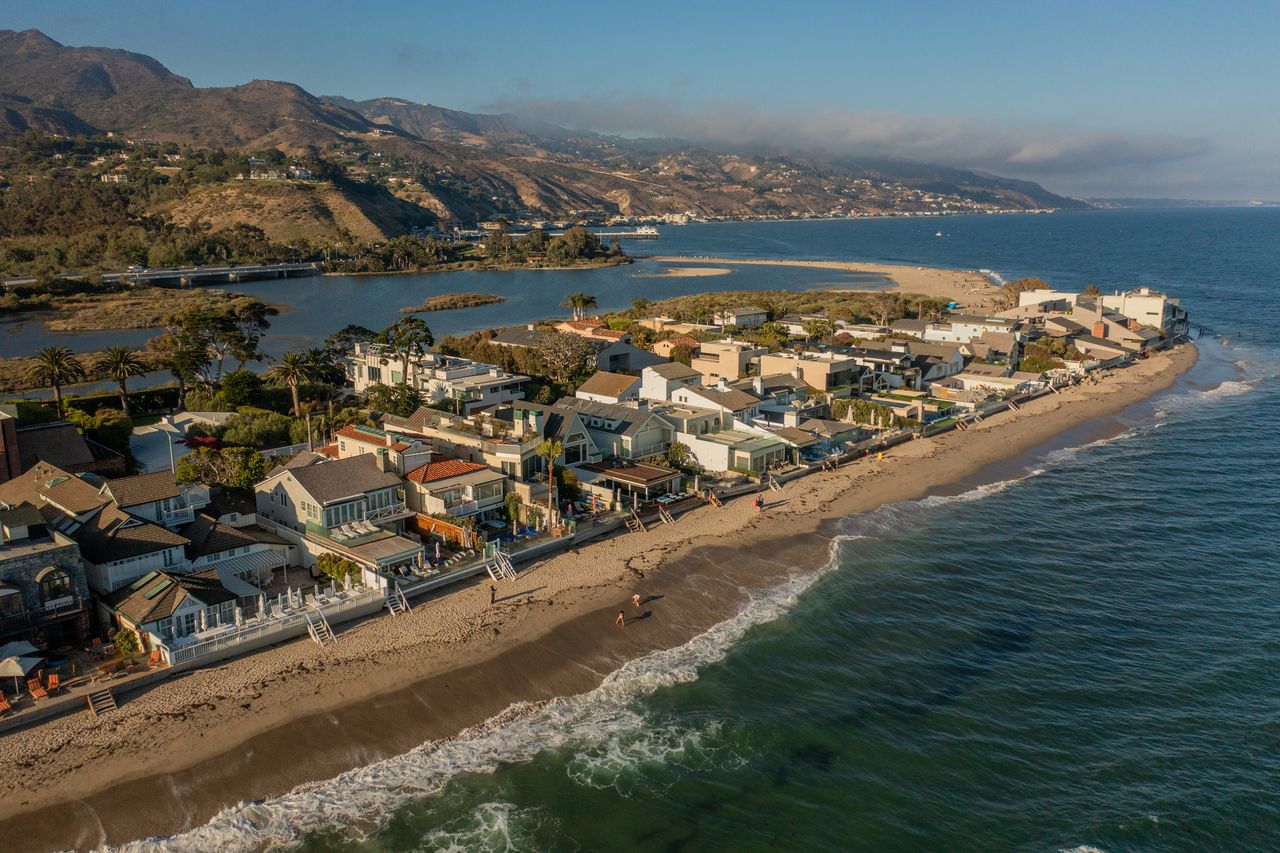
Driving north in Malibu, Calif., on the famed Pacific Coast Highway, there is a spot where the road veers away from the ocean, and the views are replaced by a hillside, thick foliage and, in some places, a man-made barrier. Many drivers have no idea they are driving past some of the world’s most expensive homes, including a recently-expanded compound owned by the widow of Apple visionary Steve Jobs.
Beyond that hillside sits a roughly 1-mile stretch of beach known as Paradise Cove, known to local realtors as “Billionaires’ Bluff.” It is so exclusive that, since 2020, three of the approximately 25 homes there have sold for $100 million or more, making up a third of the deals that closed at that price point in the Los Angeles area during the same period. Two have broken the record for the most expensive home ever sold in California at the time of each sale.
They include transactions by household names such as Beyoncé and Jay-Z, as well as technology heavyweights such as venture capitalist Marc Andreessen , WhatsApp co-founder Jan Koum and Laurene Powell Jobs . Some buyers have gone to great lengths to piece together their blufftop Paradise Cove compounds over time.
“Rich people like to congregate and they’ve congregated here,” said local agent Leonard Rabinowitz. “It makes them feel safe and more comfortable.”
In some ways, the location, roughly 35 miles from Downtown Los Angeles, seems like an unlikely destination for the country’s wealthiest people. To the north is Paradise Cove Mobile Home Park, widely regarded as the most expensive trailer park in America. Dating to the 1950s, when the then-owners allowed commercial fishermen to park campers there, the park is a throwback to the days before Malibu was brimming with the super rich. Its roughly 250 trailers and manufactured homes have since drawn celebrities such as Stevie Nicks and Matthew McConaughey, who have helped drive prices of the trailers into the millions of dollars. A casual beachfront cafe sits at the base of the bluff.
On the other side of the trailer park, on the cusp of Paradise Cove, sits an estate long owned by Barbra Streisand. To the south is the iconic Geoffrey’s restaurant, which has been serving surf and turf from its oceanfront patio since 1983.
Local realtors say the appeal of the Cove is obvious. Rather than a beach house on the sand or a blufftop mansion with more far-reaching views, homes in Paradise Cove offer the best of both worlds. Sitting behind gates off the highway, the houses are largely shielded from public view and occupy multi-acre parcels much larger that those typically available in nearby Point Dume or in the neighbouring celebrity-filled Malibu Colony. Most of the homes are also shielded from the view of their neighbours. “If you do see them, you’re seeing the corner of a roof in the distance,” said local agent Kurt Rappaport , who has sold many of the homes on the cove.
A lot of the homes also offer direct beach access via private pathways and some include beachfront cabanas or smaller homes on the sand. One formerly owned by singer Kenny Rogers has a private funicular, a type of cable railroad, that leads from the blufftop house to the ocean.
While publicly accessible, the beach at Paradise Cove is rarely busy, since there is limited parking, though it is a draw for local surfers, local agents said. Some might recognise it from the 1970s television hit “The Rockford Files,” starring James Garner, which was filmed at the cove.
A steady drumbeat of big-ticket deals in recent years has helped cement the stretch’s reputation as the most sought-after beachfront enclave in California.
Most famously, entertainment power couple Beyoncé and Jay-Z paid $190 million for a mansion designed by Japanese architect Tadao Ando. The blufftop house, measuring about 42,000 square feet, was designed by Ando for prominent art collectors Bill and Maria Bell, who spent a dozen years constructing what Maria Bell has said is a “sculpture as much as it is a building.” The deal, which closed in May 2023, was briefly the most expensive ever in the state.
Before that, a deal by venture capitalist Marc Andreessen and his wife, Laura Arrillaga-Andreessen, on the same blufftop held the record. In 2021, they paid $177 million for a 7-acre compound formerly owned by fashion mogul Serge Azria and his wife, Florence Azria. That property includes a roughly 10,000-square-foot main residence, two guesthouses, a cinema and a spa.
More recently, Powell Jobs, founder of philanthropic and investment company Emerson Collective, added a $94 million property to her private Paradise Cove compound, bringing her total aggregate spending in the cove to more than $170 million. The assemblage has involved separate transactions with four sellers spanning from 2015 to 2024.
Other major transactions include WhatsApp co-founder Jan Koum’s purchase of two neighbouring compounds for a combined $187 million in 2020 and 2021, as well as movie producer Edward H. Hamm Jr’s $91 million deal to buy a home from British videogame designer Jonathan Burton and his ex-wife, Helen Musk, in 2023. In 2022, billionaire media mogul Byron Allen also paid $100 million for a Malibu estate formerly owned by self-storage billionaire Tammy Hughes Gustavson.
These wealthy newbies join a string of well-known names on the bluff. They include tennis legend John McEnroe, “The Apprentice” creator Mark Burnett, and Kari Clark, the wife of the late television host Dick Clark.
Leonardo DiCaprio is also doing construction on a home on Paradise Cove; he bought the site, which is next to the home owned by Burnett, for $23 million in 2016, according to property records and a person familiar with the deal. His property was formerly owned by director Ridley Scott.
Values in Paradise Cove have shot up so significantly thanks in large part to the lack of available inventory, Rappaport said. Since prices there are so high, the cove doesn’t typically draw speculators. Owners there are so rich they usually don’t need the money and don’t typically sell, unless they have had a significant change in circumstances, he said. One of the few available homes on the cove is an $85 million Greek-inspired estate owned by Peter O’Malley, the former owner of the Los Angeles Dodgers. O’Malley has owned the 2.5-acre property since around 2000 and is selling following the death of his wife, Annette O’Malley, last year.
When properties do come up, “there’s usually a neighbour to buy it,” Rappaport said.
Homeowners such as those on the cove don’t always start out with a plan to assemble a larger compound. Those plans shape up over time as opportunities arise, Rappaport said. The larger footprints mean increased privacy and protected views and limit the chance that homeowners will have to deal with construction on the neighbouring lot. “They think, ‘Oh, it would be nice to have the house next door,’ ” he said.
Even as the broader Los Angeles luxury market has been hobbled by interest rate increases, a drop in demand from foreign purchasers and an exodus of high-net worth individuals to lower-tax states, the Paradise Cove market has continued to post record deals.
“It reminds us that these home sales have nothing to do with the broader market they sit within,” said appraiser Jonathan Miller of Miller Samuel. “It’s a very specifically designed submarket and its success doesn’t wash over onto the whole housing market.”
Miller said it isn’t uncommon in ultrahigh-end communities for transactions to happen in clusters as they have in Paradise Cove.
“There is one big transaction and then a lot of copycats around it. I think it’s FOMO,” he said, using the popular acronym for “fear of missing out.”
In the overall L.A. market, the slowdown in deals has been compounded by a new mansion transfer tax, which applies only to the city of Los Angeles. It has “killed off excess demand,” particularly from developers and property speculators who plan to flip the properties, Miller said. Previously, that represented a significant portion of the buyer pool and the market fed on itself, he said. The new tax, enacted last year, requires sellers to pay 4% on sales of homes priced between $5 million and $10 million, and 5.5% on sales of properties at $10 million or above.
While sales are up 15% year-over-year in the overall luxury Los Angeles market, eight-figure sales are rare. None have closed in the city of Los Angeles since the introduction of the tax, according to data from Stephen Shapiro, co-founder of Westside Estate Agency.
The tax has only made sellers more resolute about their pricing, local agents said.
“Our problem [in Los Angeles] has been that the buyers think that it’s a buyer’s market and the sellers have been feeling like they’ll get their price if they hold out,” said agent Jade Mills of Coldwell Banker Realty.
In Paradise Cove, buyers are under no such illusion that the market favours them.
“They are willing to step up,” Mills said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
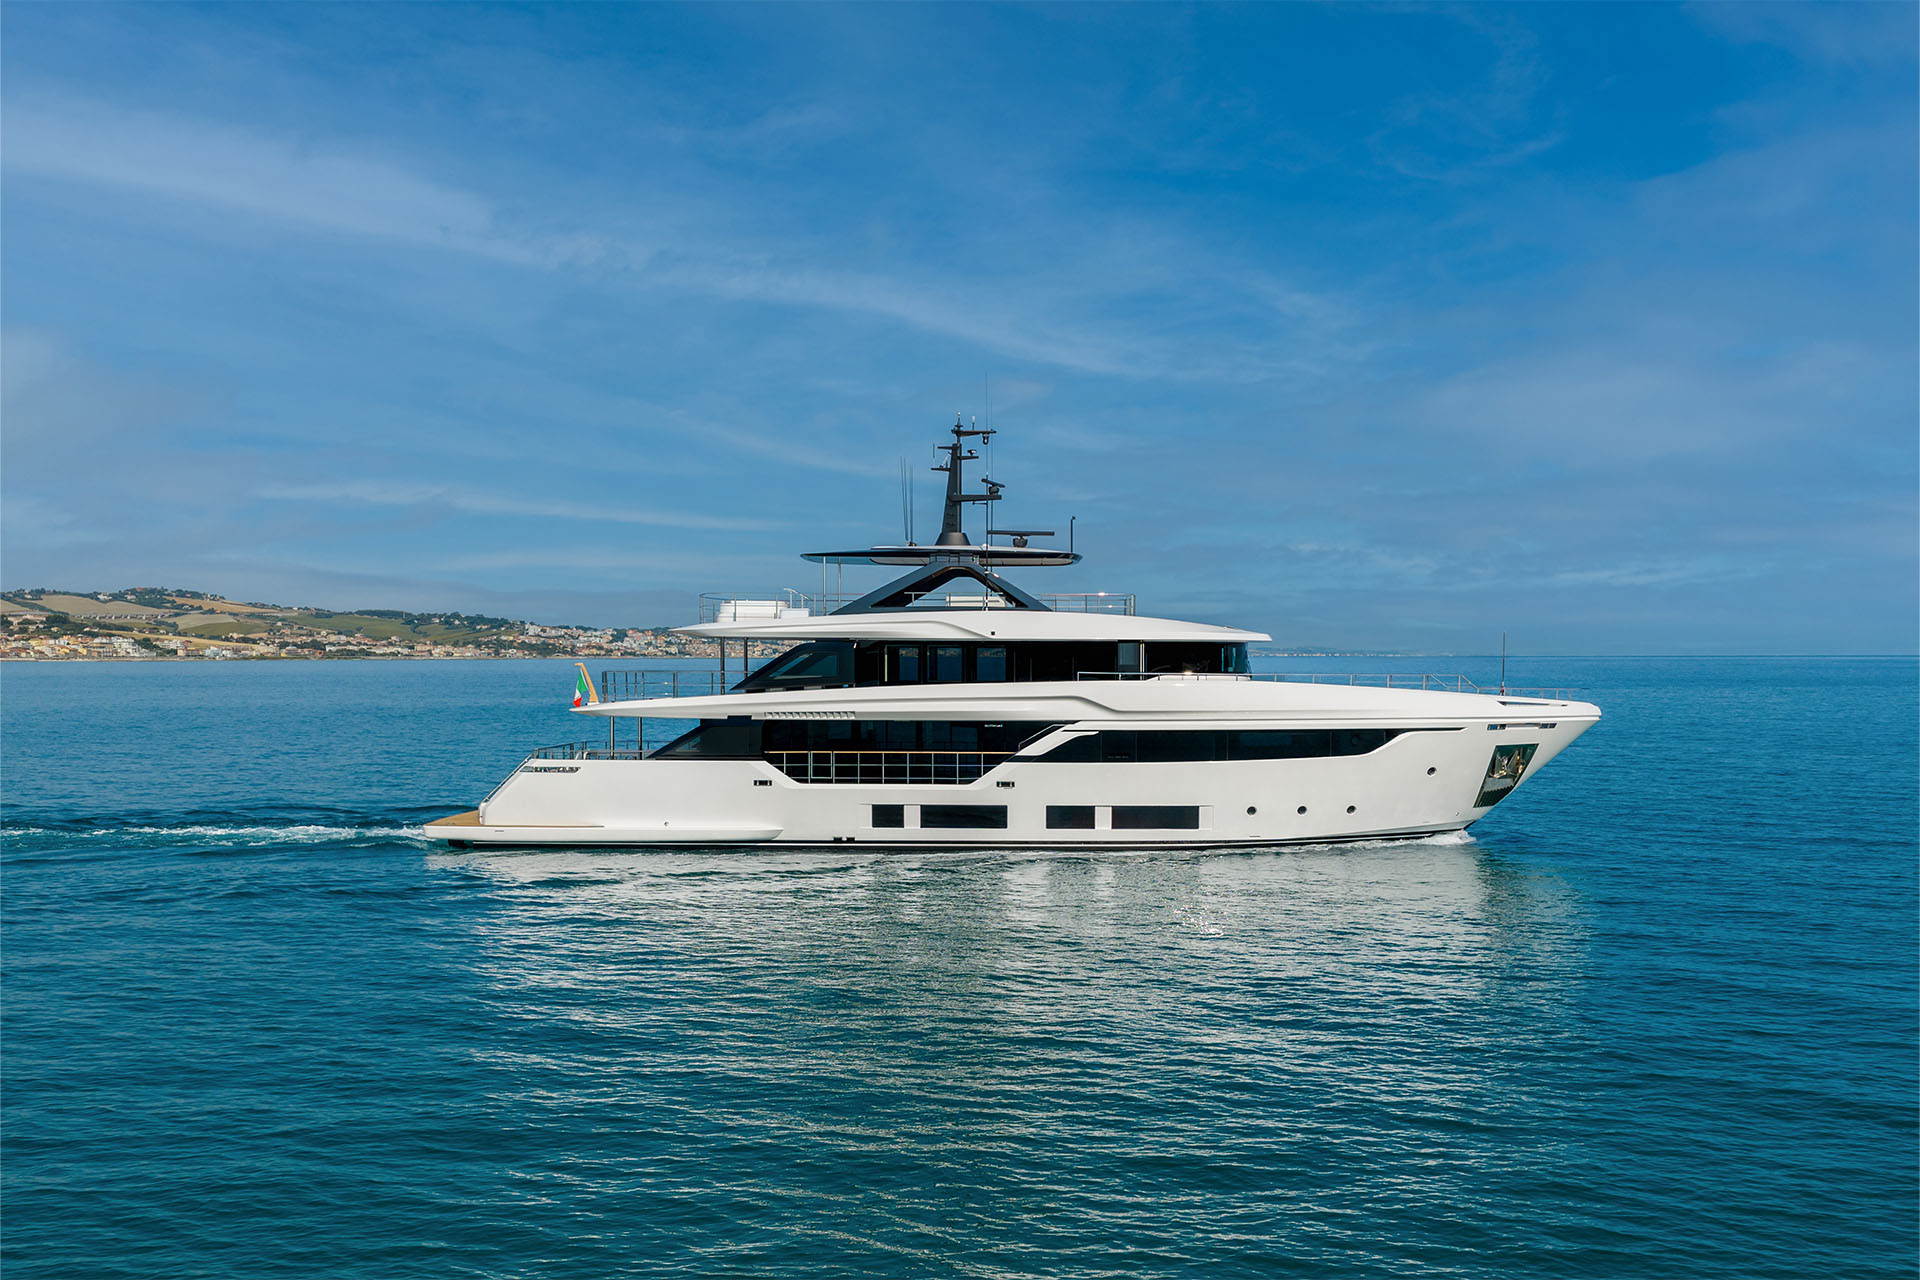
Four decks, 34.5 metres and a made-to-measure interior: step aboard the new Custom Line Navetta 35, unveiled at Cannes.
New detached-home sales fell 10% nationally in August, led by a 27% decline in Victoria, raising concerns about construction starts in 2027.
2 min
Australia’s hoped-for recovery in housing construction is losing momentum before it has had time to close the national supply gap.
Sales of new detached homes fell 10 per cent nationally in August, according to the Housing Industry Association’s survey of major volume builders across the five largest mainland states. It was the fourth consecutive monthly decline.
The fall was broad rather than isolated. Victoria recorded the largest retreat, down 27 per cent, followed by Queensland at 20.2 per cent, New South Wales at 17.5 per cent, South Australia at 10.8 per cent and Western Australia at 8.2 per cent.
Across the three months to August, sales were 19.3 per cent below the preceding three-month period and 7.7 per cent lower than the equivalent period a year earlier.
New-home sales matter beyond the immediate fortunes of volume builders. They are an early indicator of future starts: buyers sign contracts, finance is finalised, approvals are secured and construction follows months later. A sustained sales decline during the middle of 2026 is therefore likely to weaken commencements during 2027.
The slowdown reflects the collision of several pressures. Households have absorbed multiple interest-rate rises, reducing borrowing capacity and increasing the repayment cost attached to a new build. Established-home prices have softened in some markets, weakening the relative appeal of waiting through a construction period. Builders continue to face elevated labour and material costs.
The Reserve Bank’s August analysis showed new-dwelling construction prices increased 1.8 per cent during the June quarter and 5.3 per cent over the year. It attributed part of the pressure to oil-derived building products and other conflict-related costs.
Policy uncertainty can also cause buyers and investors to defer large commitments. But the precise contribution of any single tax or regulatory change is difficult to isolate from rates, confidence, land prices and construction costs. The HIA survey should be read as an indicator from large builders rather than a complete count of every dwelling sale.
The figures complicate progress towards the Housing Accord target of 1.2 million homes. The National Housing Supply and Affordability Council reported 308,000 completions since the Accord began and 244,000 dwellings under construction in the March quarter. Approvals and commencements had improved, but falling sales risk undermining the next wave.
For developers and governments, the warning is that planning approvals alone do not create homes. Projects need finance, viable construction pricing and buyers able to settle. If one part fails, approved supply can remain on paper.
Data box
National August new-home sales: Down 10 per cent
Three months to August: Down 19.3 per cent from the preceding three months
Year-on-year three-month comparison: Down 7.7 per cent
Victoria: Down 27 per cent
Queensland: Down 20.2 per cent
New South Wales: Down 17.5 per cent
South Australia: Down 10.8 per cent
Western Australia: Down 8.2 per cent

Micro-needling promises glow and firmness, but timing can make all the difference.
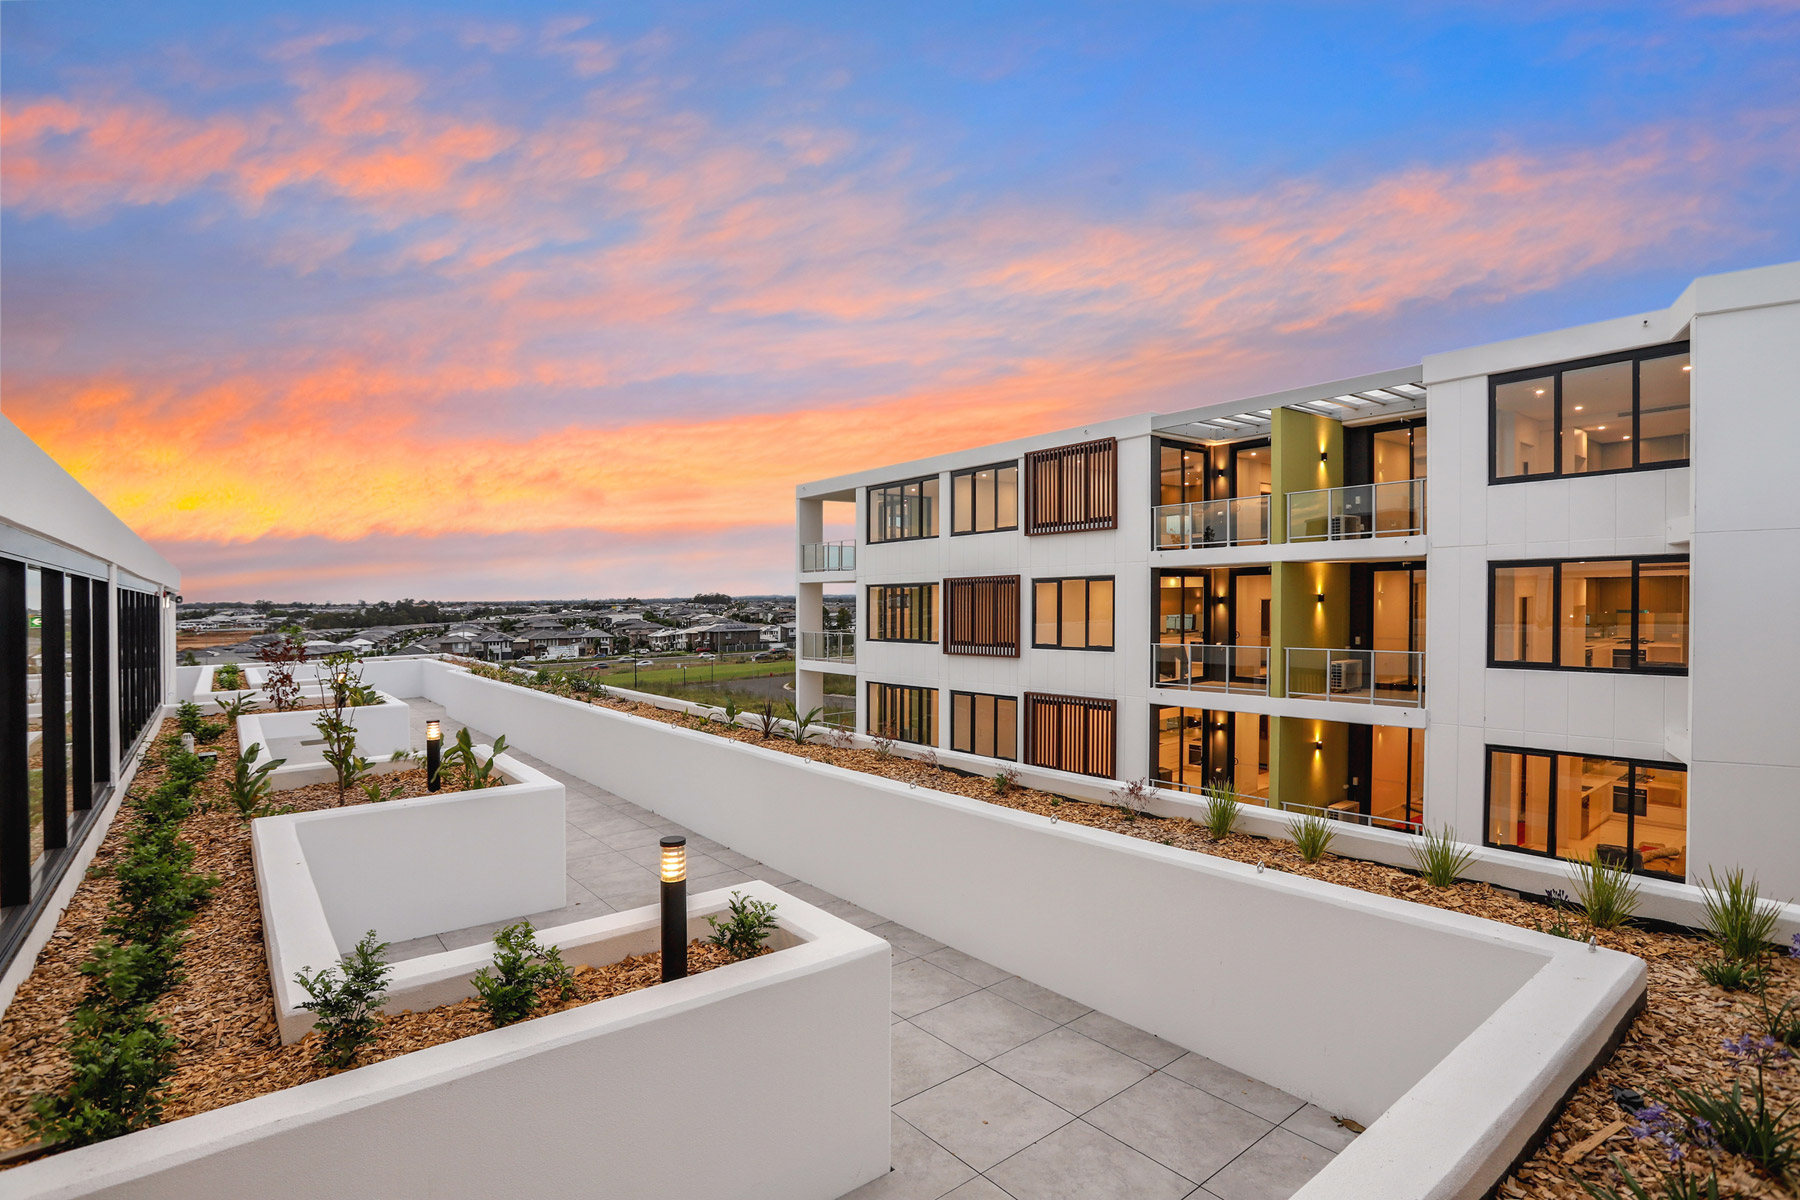
Ophora Tallawong has launched its final release of quality apartments priced under $700,000.


