The Lifespan of Large Appliances Is Shrinking
Appliance technicians blame a push toward computerisation and an increase in the quantity of components inside a machine

 4 min
Our refrigerators, washing machines and ovens can do more than ever, from producing symmetrical ice cubes to remotely preheating on your commute home. The downside to all these snazzy features is that the appliances are more prone to breaking.
Appliance technicians and others in the industry say there has been an increase in items in need of repair. Yelp users, for example, requested 58% more quotes from thousands of appliance repair businesses last month than they did in January 2022.
Those in the industry blame a push toward computerisation, an increase in the quantity of individual components and flimsier materials for undercutting reliability. They say even higher-end items aren’t as durable.
American households spent 43% more on home appliances in 2023 than they did in 2013, rising from an inflation-adjusted average of $390 to $558, according to Euromonitor International. Prices for the category declined 12% from the beginning of 2013 through the end of 2023, according to the Labor Department.
One reason for the discrepancy between spending and prices is a higher rate of replacement, say consumers, repair technicians and others. That’s left some people wishing they had held on to their clunky ’90s-era appliances and others bargaining with repair workers over intractable ice makers and dryers that run cold.
“We’re making things more complicated, they’re harder to fix and more expensive to fix,” says Aaron Gianni, the founder of do-it-yourself home-repair app Plunjr.
Horror stories
Sharon J. Swan spent nearly $7,000 on a Bosch gas range and smart refrigerator. She thought the appliances would last at least through whenever she decided to sell her Alexandria, Va., home and impress would-be buyers.
That was before the oven caught fire the first time she tried the broiler, leading to a 911 call and hasty return. The ice-maker in the refrigerator, meanwhile, is now broken for the third time in under two years. Bosch covered the first two fridge fixes, but she says she’s on her own for the latest repair, totalling $250, plus parts.
“I feel like I wasted my money,” says the 65-year-old consultant for trade associations.
A Bosch spokeswoman said in an emailed statement that the company has been responsive to Swan’s concerns and will continue to work with her to resolve ongoing issues. “Bosch appliances are designed and manufactured to meet the highest quality standards, and they are built to last,” she said.
Kevin and Kellene Dinino wish they had held on to their white dishwasher from the ’90s that was still working great.
The sleeker $800 GE stainless steel interior dishwasher they purchased sprang a hidden leak within three years, causing more than $35,000 worth of damage to their San Diego kitchen.
Home insurance covered the claim, which included replacing the hardwood down to the subfloor and all their bottom cabinetry, but kicked the Dininos off their policy. The family also went without access to their kitchen for months.
“This was a $60 pump that was broken. What the hell happened?” says Kevin, 45, who runs a financial public-relations firm.
A GE Appliances spokeswoman said the company takes appliance issues seriously and works quickly to resolve them with consumers.
Increased complexity
Peel back the plastic on a modern refrigerator or washing machine and you’ll see a smattering of sensors and switches that its 10-year-old counterpart lacks. These extra components help ensure the appliance is using only the energy and water it needs for the job at hand, technicians say. With more parts, however, more tends to go wrong more quickly, they say.
Mansoor Soomro, a professor at Teesside University, a technical college in Middlesbrough, England, says home appliances are breaking down more often. He says that manufacturers used to rely mostly on straightforward mechanical parts (think an on/off switch that triggers a single lever). In the past decade or so, they’ve transitioned to relying more on sophisticated electrical and computerised parts (say, a touch screen that displays a dozen different sensor-controlled wash options).
When a complicated machine fails, technicians say they have a much harder time figuring out what went wrong. Even if the technician does diagnose the problem, consumers are often left with repairs that exceed half the cost of replacement, rendering the machine totalled.
“In the majority of cases, I would say buying a new one makes more economic sense than repairing it,” says Soomro, who spent seven years working at Siemens , including in the home-appliances division.
These machines are also now more likely to be made with plastic and aluminium rather than steel, Soomro says. High-efficiency motors and compressors, too, are likely to be lighter-duty, since they’re tasked with drawing less energy .
A spokeswoman for the Association for Home Appliance Manufacturers says the industry has “enhanced the safety, energy efficiency, capacity and performance of appliances while adding features and maintaining affordability and durability for purchasers.” She says data last updated in 2019 shows that the average life of an appliance has “not substantially shifted over the past two decades.”
When simpler is better
Kathryn Ryan and Kevin Sullivan needed a new sensor to fix their recently purchased $1,566 GE Unitized Spacemaker washer-dryer. GE wasn’t able to fix the sensor for months, so the couple paid a local technician $300 to get the machine working.
The repairman also offered them a suggestion: Avoid the sensor option and stick to timed dries.
“You should be able to use whatever function you please on a brand new appliance, ideally,” says Sullivan, a 32-year-old musician in Burbank, Calif.
More features might seem glamorous, Frontdoor virtual appliance tech Jim Zaccone says, but fewer is usually better.
“Consumers are wising up to the failures that are happening and going, ‘Do I really need my oven to preheat while I’m at the grocery store?’” jokes Zaccone, who has been in the appliance-repair business for 21 years.
He just replaced his own dishwasher and says he bought one with “the least bells and whistles.” He also opted for a mass-market brand with cheap and readily available parts. Most surprisingly, he chose a bottom-of-the-line model.
“Spending a lot of money on something doesn’t guarantee you more reliability,” says Zaccone.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

With two waterfronts, bushland surrounds and a $35 million price tag, this Belongil Beach retreat could become Byron’s most expensive home ever.
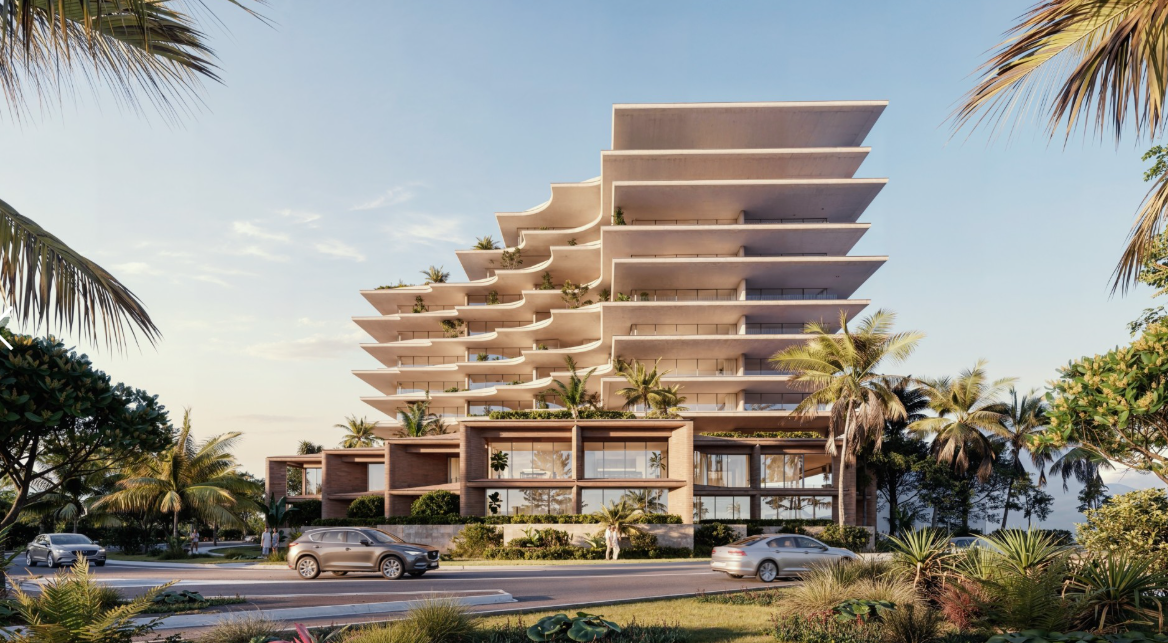
Queensland-based builder-developer MAYD has unveiled an exclusive first look at its anticipated ultra-luxury North Kirra mixed-use project as it lodges a minor amendment with the City of Gold Coast Council. The project sits across a 4,742sqm amalgamated landholding spanning seven parcels at 2–6 Pacific Parade and 27–33 Golden Four Drive, Bilinga, which MAYD secured in …
Continue reading “MAYD”s North Kirra Plans Unveiled Ahead of Early 2027 Launch”