The Well-Heeled Are Headed to Puglia, the End of Italy’s Boot

 5 min

The heel of Italy’s boot is its hospitable heartland, at least to a growing contingent of savvy travellers who find themselves turning to Puglia time and again, perhaps at first for its rusticity, but now for its lavish resorts. It’s been a long time coming for the historically overlooked region and its 500 miles of coastline, most of which is devoid of the crowds overstuffing other parts of the country.
“Puglia is authentic but contemporary, relaxing but full of vibrant energy,” says Aldo Melpignano, owner of Borgo Egnazia, a luxury resort that has helped put the region on the map for international travellers. “It’s becoming more and more an international travel destination, but you can still discover hidden gems and unspoiled places.”
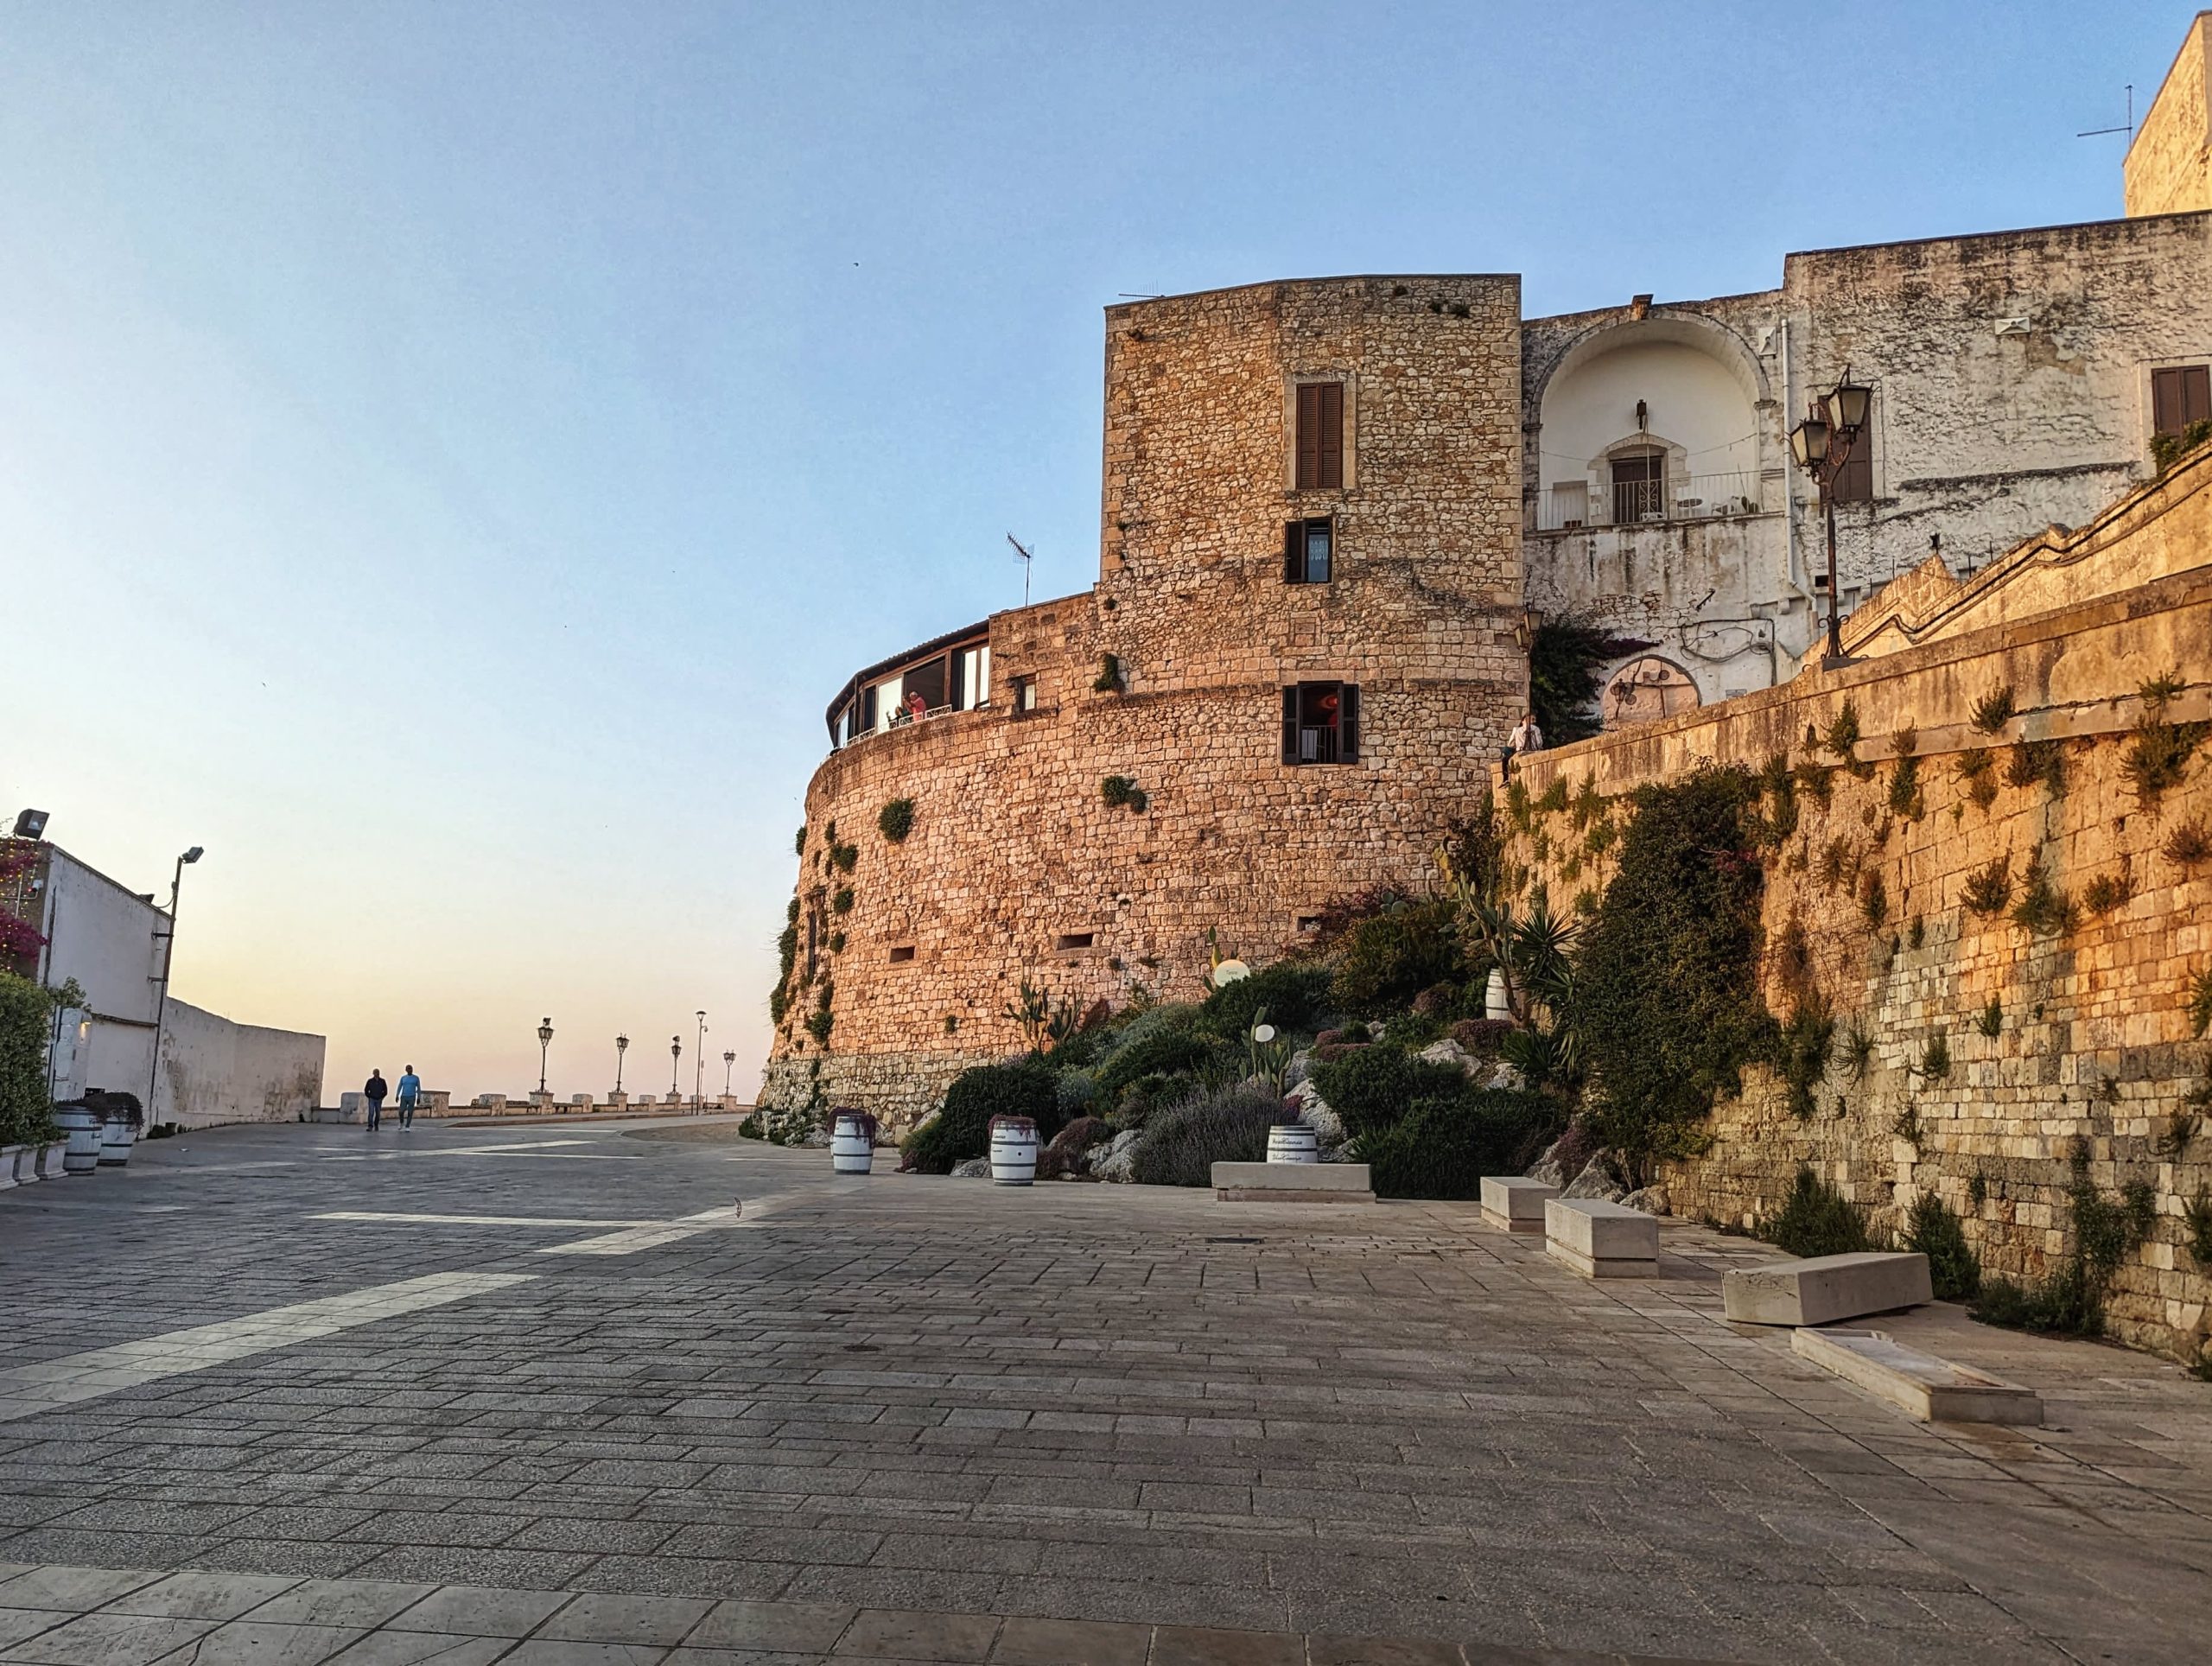
Charming towns line the Adriatic coastline like whitewashed pearls on a string, from Lecce to Brindisi, onward to Ostuni and Monopoli, continuing north to Bari and Trani. The countryside in between showcases the remnants of conical trulli, traditional stone-hut residences, found amid endless olive groves. Its every facet has a distinct Puglian feel, an inimitable aura of charm and hospitality that cannot be replicated.
The Growth of Puglia’s Luxury Scene
“Sometimes when you are in a luxury resort in the Côte d’Azur or Sardinia or Mexico, you feel like you could be anywhere, you don’t have a sense of place” says Vito Palumbo, CEO of Tormaresca winery. “When you are in Borgo Egnazia or Torre Coccaro, though, you know you are in Puglia, you know that you’re in a masseria that has been revamped into a beautiful resort with a very strong Puglian identity.”
Jake Emen
It’s been a quarter century since Tormaresca was acquired by wine conglomerate Antinori, whose financial backing and know-how helped modernize its efforts, transforming its distinctive terroir and native grapes—such as Primitivo, Negroamaro, Aglianco, and Fiano—into sought-after varieties. In more recent years, Palumbo has grown into a role as the face of Tormaresca, but also as the de facto ambassador for Puglia on the whole, dedicated to touting the appeal of his home region.
Puglia’s beloved masserias, or farm estates constructed in village-like fashion, replete with small walkways and central gathering plazas, offer a different spin on Italian luxury and hospitality, versus the villas of Tuscany, the cliff top properties along the Amalfi coast, or the grand dames of Venice and Florence.
One of the initial masserias to make a splash was Masseria Il Melograno, whose grounds are studded with gnarled and wizened 600-year-old olive trees and purple bougainvillea flowers. But when Borgo Egnazia opened in 2010, following a six-year, reported €150 million project, it set the region on a luxurious new path, gaining recognition as one of the top properties in Italy and across continental Europe.
With that kind of success, it was perhaps inevitable that large, international brands would follow course. Rocco Forte added Masseria Torre Maizza to its portfolio in 2018, and in early 2021, Four Seasons announced an Ostuni project, signalling it would be a new construction with direct beach access and 150 villa-style guest rooms. Around the same time, Belmond purchased Masseria Le Taverne, a 17th-century farm estate, and is amid extensive renovations while aiming to maintain the property’s heritage and character.
Jake Emen
“Puglia’s popularity has grown significantly for those looking to explore a different part of Italy and to discover the region’s spectacular coastlines and beautiful beaches, rich history, and exceptional culinary offerings,” says Bart Carnahan, Four Seasons president of global business development and portfolio management.
The Roots Are in the Vineyards and the Olive Groves
At the heart of Puglia’s culinary movement is an appreciation for its local ingredients, from burrata to olive oil and a wealth of fresh seafood.
“Puglia is Italy’s most important region for extra-virgin olive oil production,” Palumbo says, citing overall output and a breadth of styles, with at least 60 types of olives found on millions of trees. Yet, as with the region’s wine, the quality of its olive oil was long overlooked, with the majority being sold in bulk. “Puglian olive oil is going places, and it’s the same story as the wine. There are more strong Puglian olive oil brands than Tuscan ones now.”
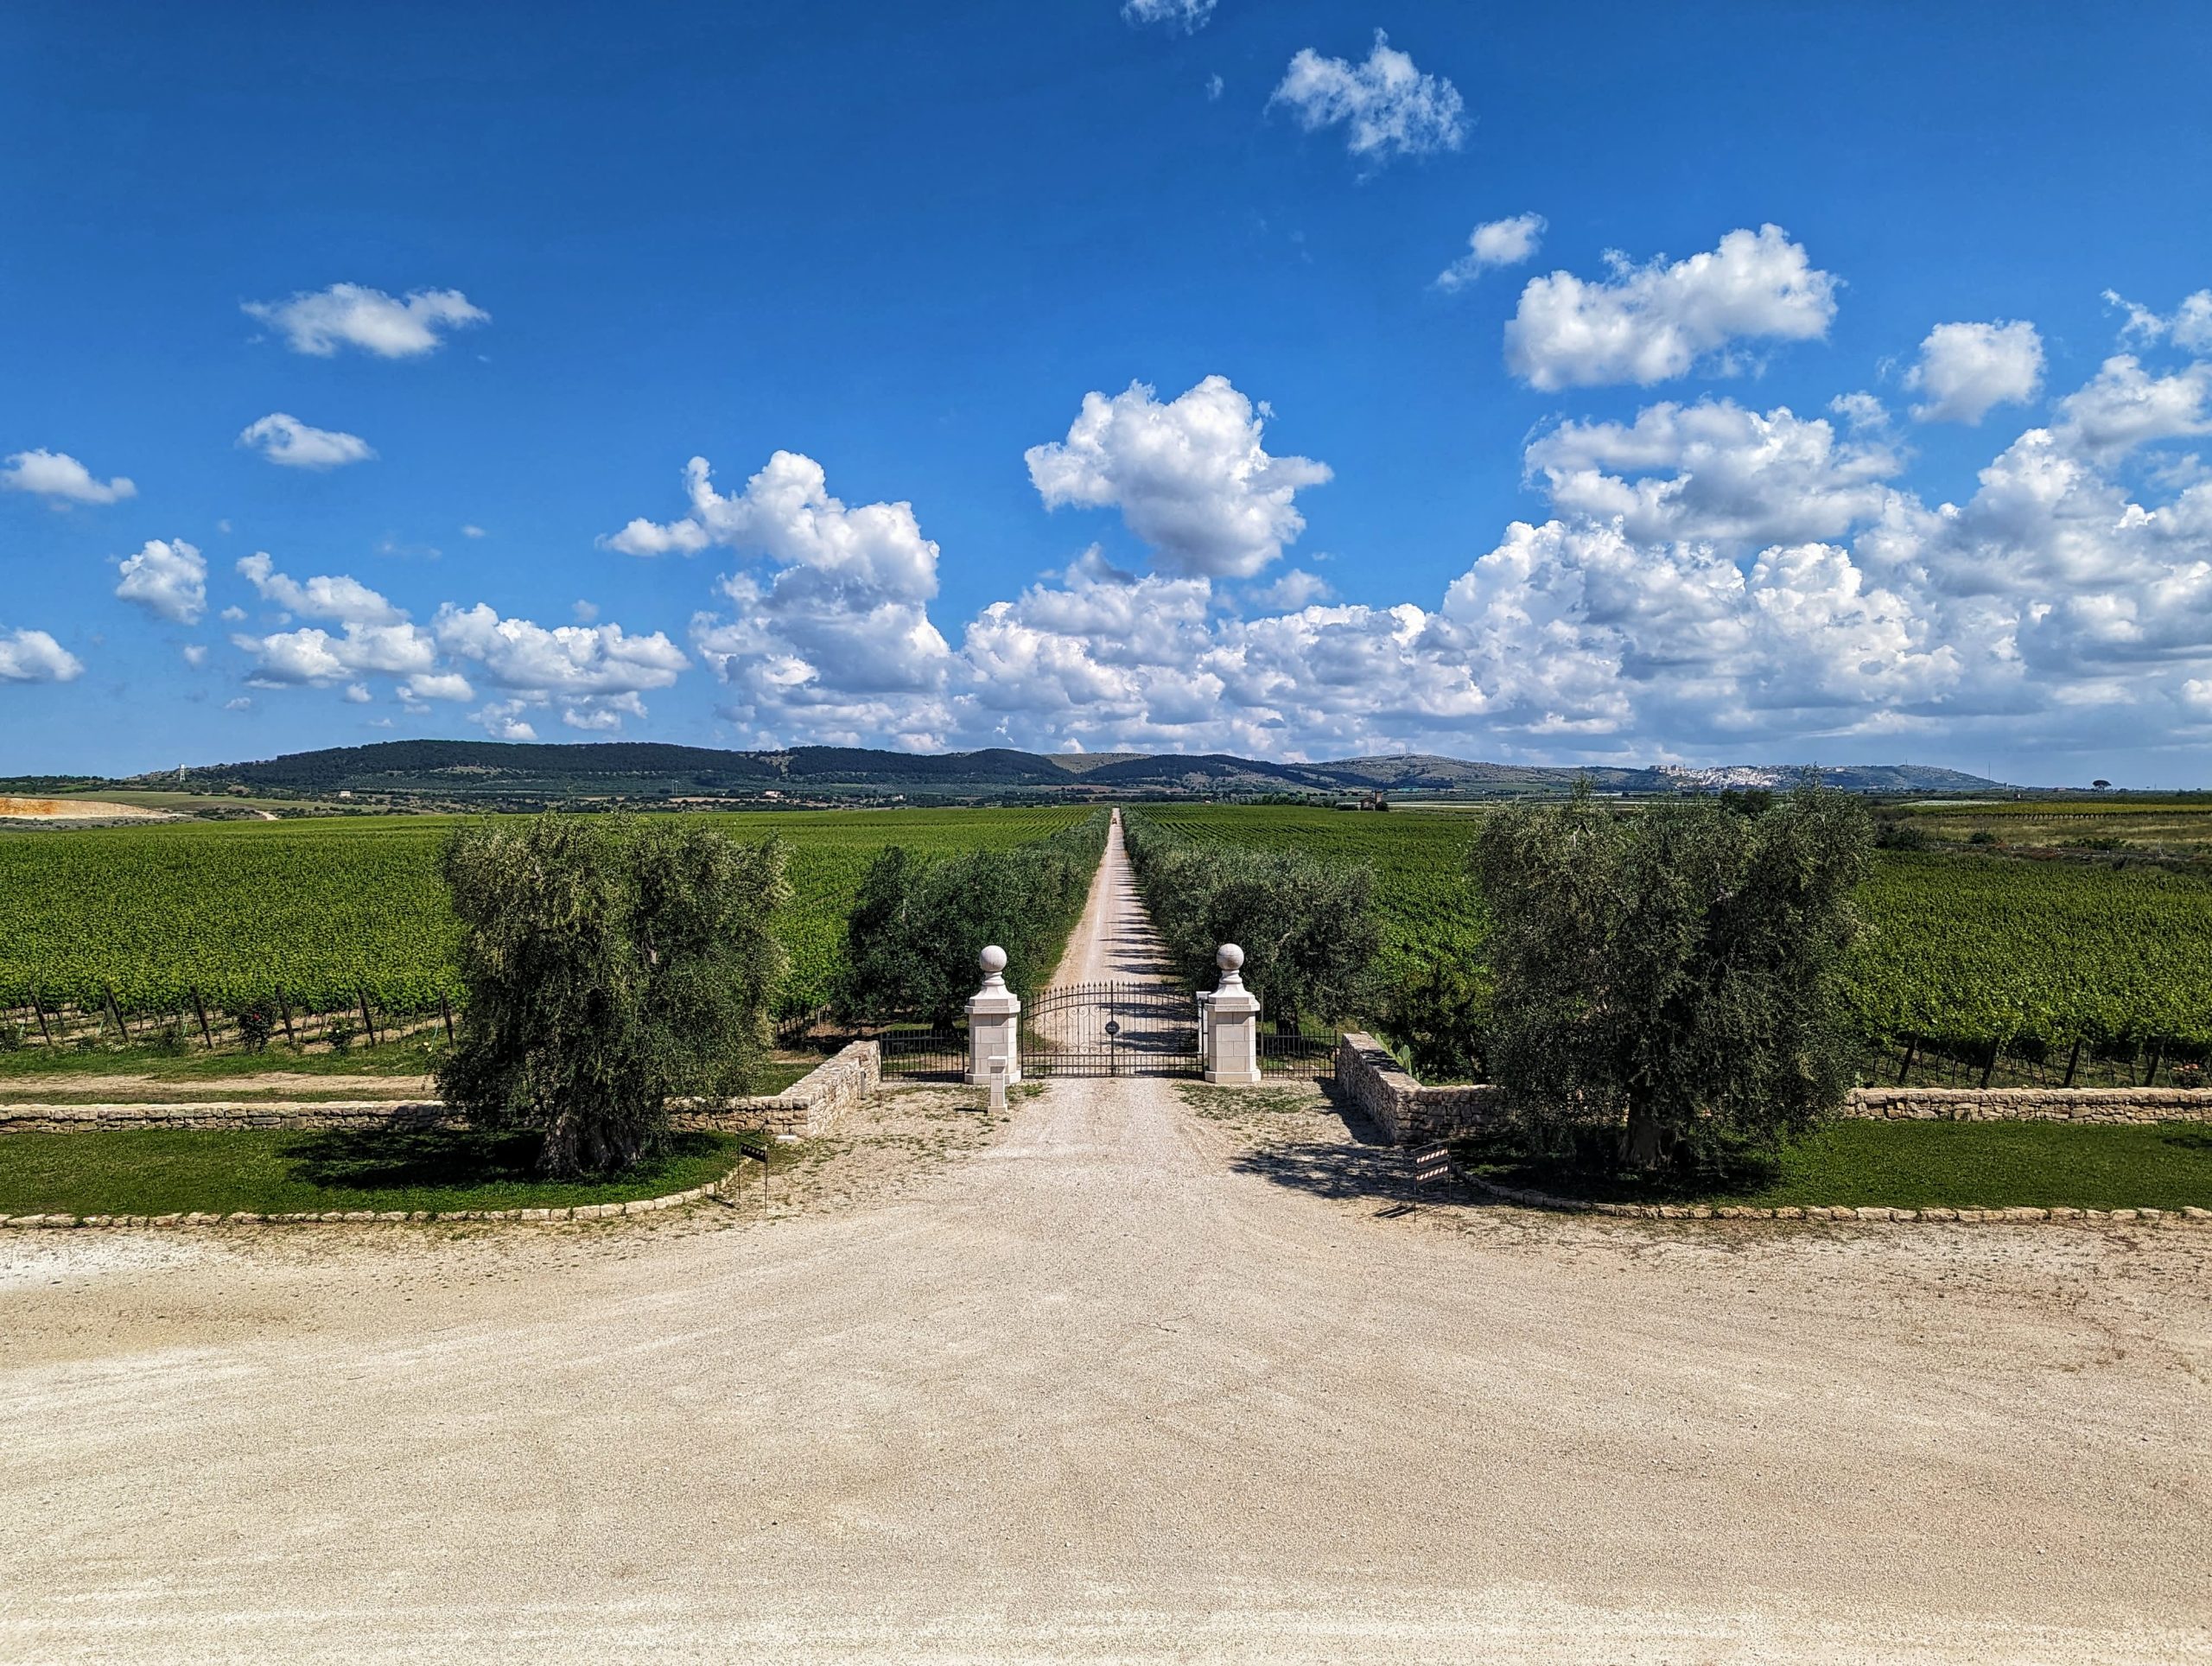
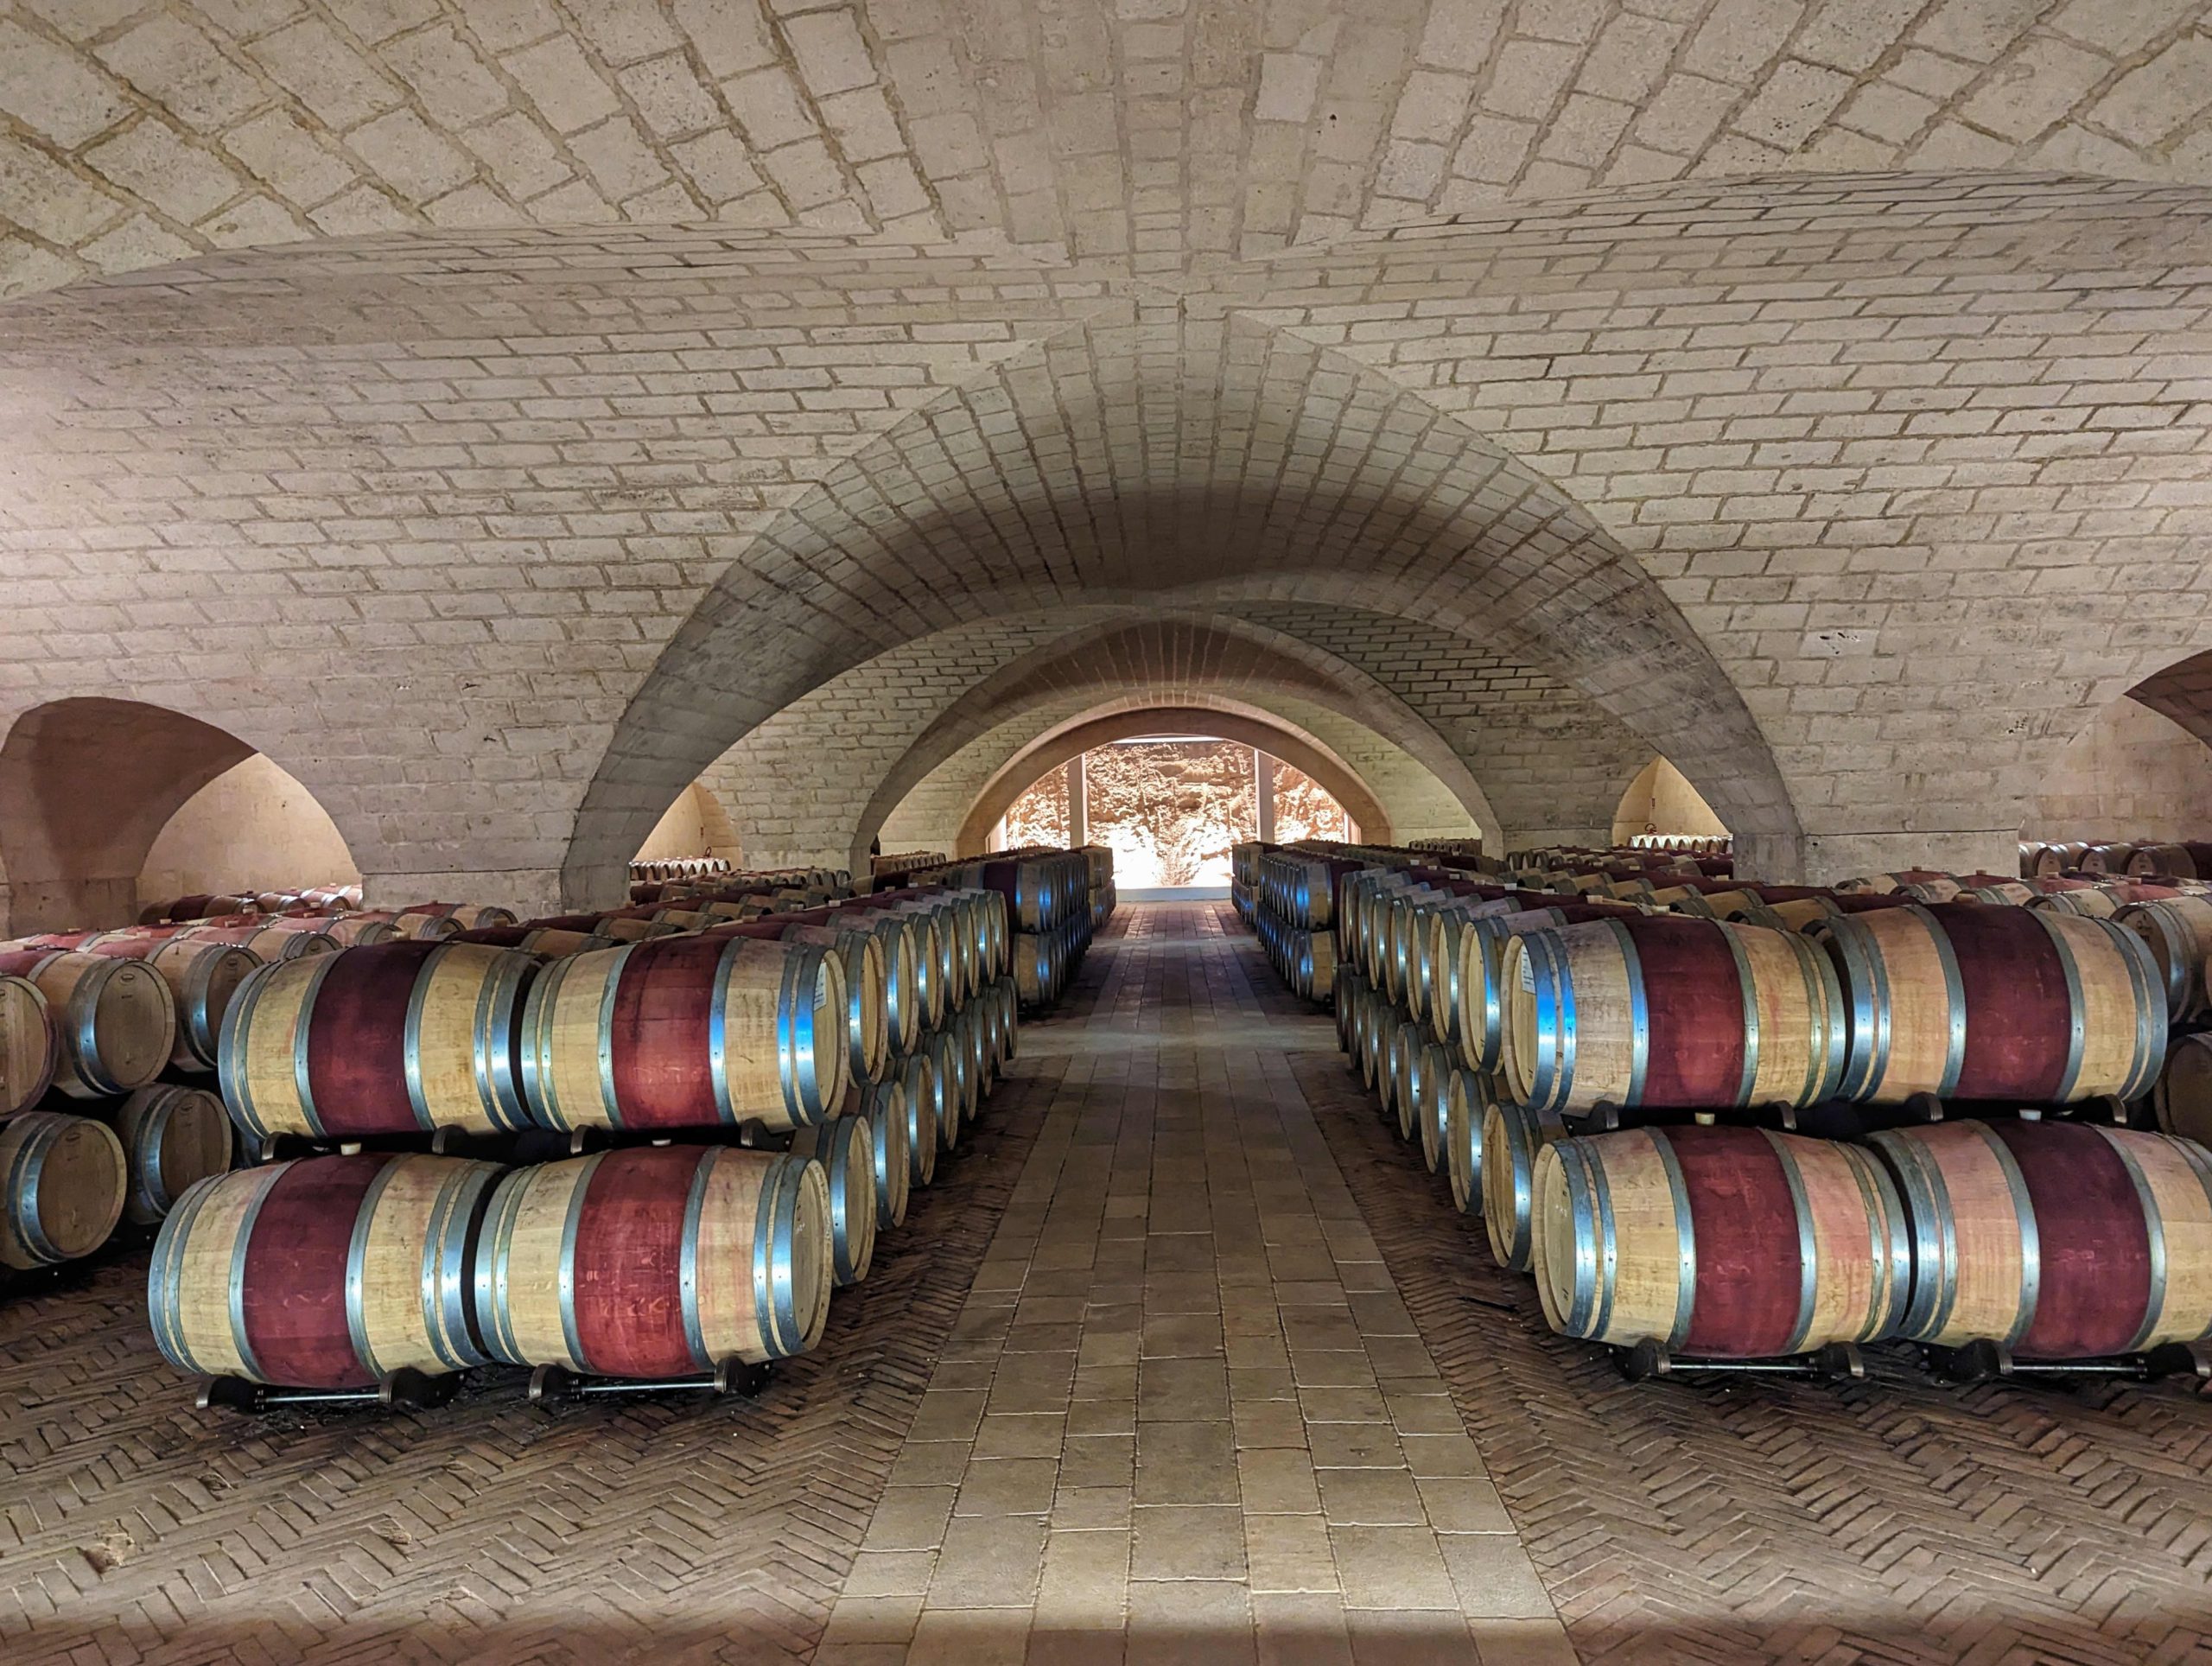
Travellers can spend a day on a farm or dairy learning how to make cheese or pressing their own olive oil, perhaps in between visits to its emergent wineries. At Tenuta Bocco di Lupo, the long, sandy white road that serves as its entrance beckons travelers to its grand estate and cellar. There, they can taste wines under its eponymous label, such as an Aglianico from Castel del Monte; Pietrabianca, made with Chardonnay and Fiano from Castel del Monte; and Fiano di Bocca Di Lupo.
Then there’s Tormaresca’s Calafuria, the best-selling rose wine in, and from, Italy. But it’s through the aforementioned offerings, along with bottles such as Torcicoda, a Primitivo from Salento, as well as the Masseria Maime Negroamaro, that Palumbo plans to establish the bonafides of his two estates in the region. What he and his winemakers have found is that Puglian wines made with intention, and reflective of their home place, are more than capable of great ageing potential, with rich character that consumers can expect to develop and unfold in the decade or two to come, while still being able to be poured today and enjoyed. “We want the Puglian influence,” Palumbo says.
Puglia’s restaurant scene has soared as well, with 10 Michelin-starred outposts in the region and scores of other fine-dining establishments. A prestige institution such as Quintessenza, in Trani, is helmed by the four Di Gennaro brothers, each of whom has a different role in the operation of a space devoted in full to showcasing and elevating Puglia’s bounty.
Jake Emen
The best eating though may be in casual, local spots with seaside views or beachfront settings, from the Coccaro beach club and restaurant, to the Trabucco Tormaresca in Trani, a sceney waterfront bar stylised as an old fisherman shack. The best of both worlds can be found at a restaurant such as Osteria del Tempo Perso in Ostuni, where classic Puglian dishes are showcased with the best ingredients, but without unneeded adornment or reinvention, with the service and setting that elevates food with humble origins into a destination dining experience.
Travellers to Puglia can indulge in it all: the excellent food and wine that will satiate the most discerning of palates and the luxurious accommodations that need not play second fiddle to anywhere else in the country, offered with the trademark embrace of the region’s hospitality.
“The ancient traditions of this region represent a unique heritage,” Melpignano says. “What really makes the difference in Puglia is the people: Always heart-warming, they have the sense of welcome in their blood.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
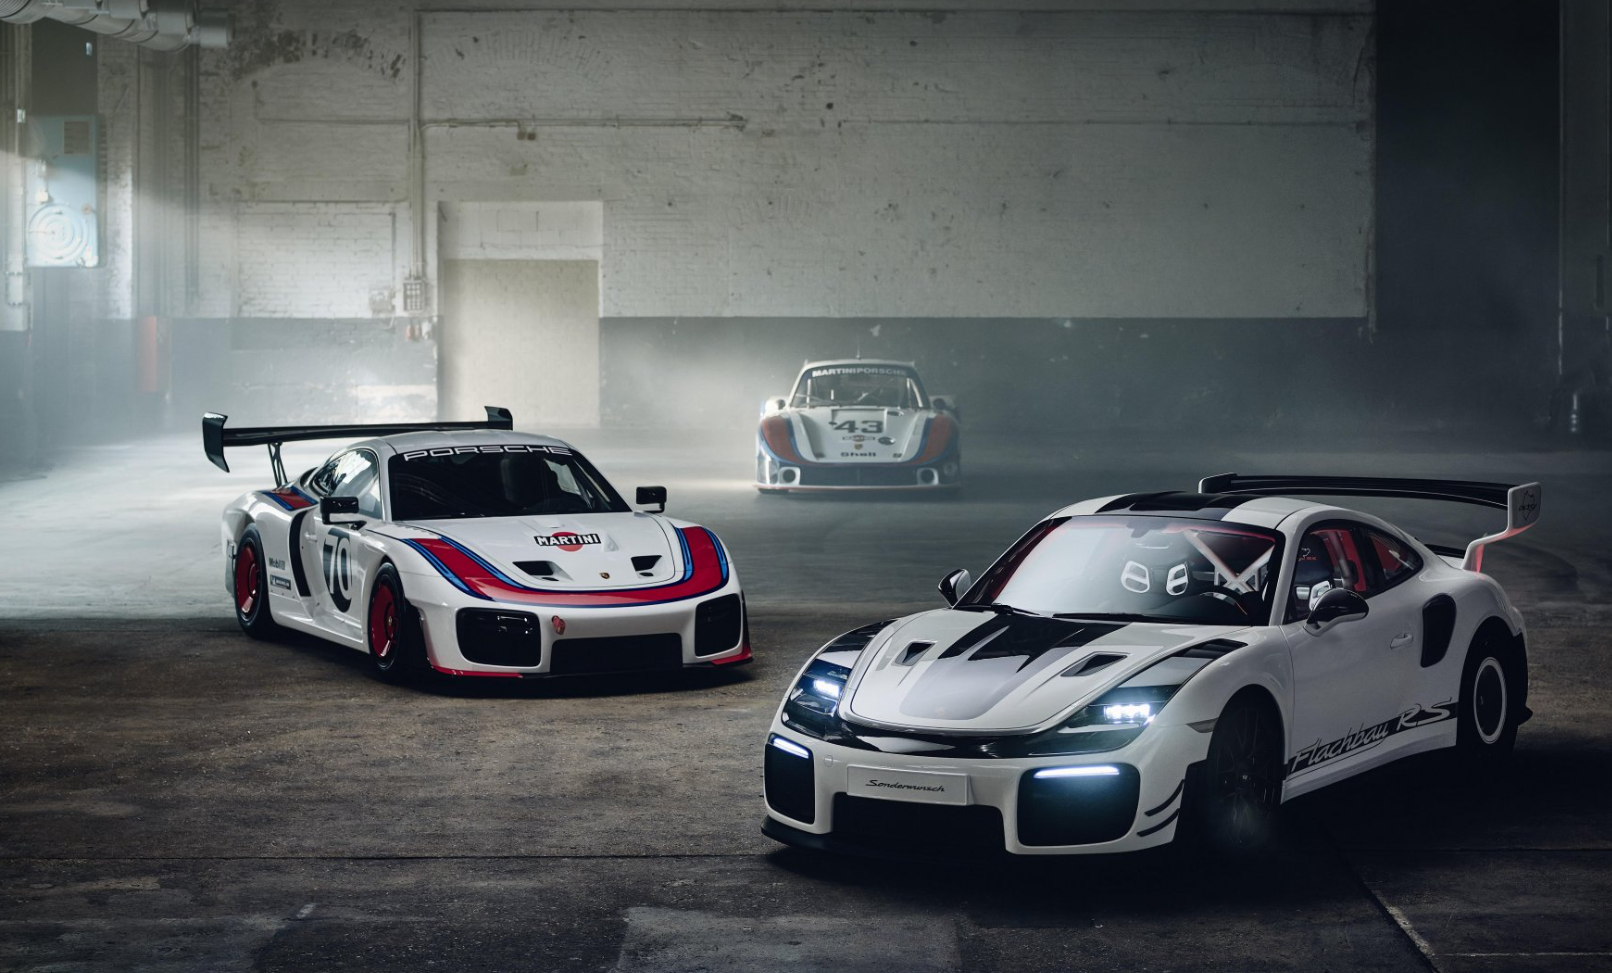
Porsche has revealed a one-off 911 GT2 RS that brings the extraordinary silhouette of its 935/78 “Moby Dick” racing car onto the road. Created by Porsche Sonderwunsch with Manthey, the commission began with a near-new GT2 RS. The owner requested greater performance, a Slantnose profile and a rear wing influenced by the limited 911 GT3 …
Continue reading “Porsche Builds a Road-Going “Moby Dick” From a 911 GT2 RS”

From citrus oils to warming spices, the classic G&T is being reimagined at home as a more thoughtful, seasonal ritual for modern entertaining.