The World’s Richest Person Auditions His Five Children to Run LVMH, the Luxury Empire
Bernard Arnault drilled his offspring in math when young, assigned them company roles and mentors as adults, then made them joint owners of a firm empowered to run the luxury conglomerate

 10 min
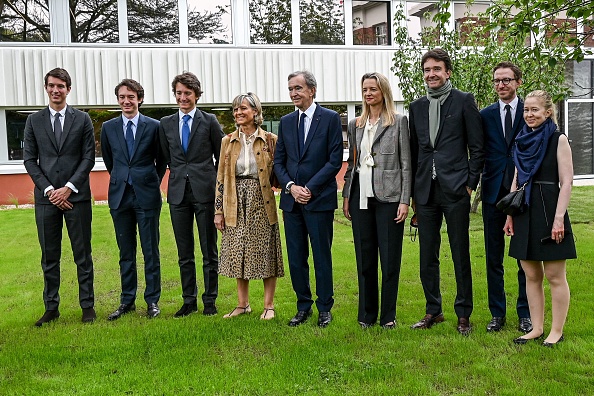
PARIS—Once a month, Bernard Arnault gathers his children for lunch inside a private dining room at the headquarters of LVMH Moët Hennessy Louis Vuitton SE, his globe-spanning luxury goods company.
The meal, which lasts exactly 90 minutes, begins with the French billionaire reading aloud discussion topics he has prepared on his iPad, according to people close to him. Mr. Arnault then goes around the table, asking each of his five adult children for advice. He’ll seek an opinion on specific managers at the company, the people said, or whether it’s time for a shake-up at one of LVMH’s myriad brands, which stretch from the Champagne vineyards of France to handbag-making workshops in Italy and Texas.
Mr. Arnault, 74, currently the world’s richest person, has spent decades grooming his children to run LVMH. He drilled them in mathematics growing up and brought them along on business trips and negotiations. Today, Mr. Arnault is tightening the family’s grip on LVMH, parachuting his children into senior roles and empowering them to one day take over the luxury empire.
In elevating his children, however, Mr. Arnault has also amplified a long-running dilemma: Who will succeed him as chief executive and chairman of the world’s biggest luxury conglomerate? Mr. Arnault built LVMH, valued at $480 billion, by hunting rival luxury firms for corporate takeovers while also nurturing generations of fashion designers. That combination of killer instinct and finesse is why his rivals call him the “wolf in cashmere.”
His eldest child, Delphine Arnault, 48, appeared to many in the fashion world to pull ahead of the pack in January when her father made her chief executive of Christian Dior, the second-largest brand in the group. Paris was also buzzing weeks earlier when her brother Antoine Arnault, 45, became CEO of the listed company that holds the family’s stake in LVMH.
Nipping at their heels are the three sons from Mr. Arnault’s second marriage. Alexandre Arnault, 30, is the executive vice president of Tiffany & Co., with a high-powered network that includes Jay-Z and Twitter co-founder Jack Dorsey. Frédéric Arnault, 28, runs the Tag Heuer watch brand, while 24-year-old Jean Arnault is director of marketing and development at Louis Vuitton’s watches division. All three studied at top engineering schools, a qualification their father has called crucial to his own success.
Mr. Arnault has given no indication whom he will choose as his successor, saying only that it will be based on merit. When asked about the matter in January at a presentation of LVMH’s annual results, he drew a parallel between his recent decision to raise the retirement age of LVMH’s chairman and CEO to 80 and French President Emmanuel Macron’s contentious push to raise France’s retirement age to 64.
“As to succession, you may also have noticed that the retirement age—which is very much in vogue—has been extended,” he said.
With his children looking on from the front row, Mr. Arnault quipped that he could use some free time to hone his skills at tennis, his favourite sport. “The last time I played with Roger Federer, I think I won one point in a single set. Maybe I could do a bit better than that,” he said.
Mr. Arnault pulled ahead of Tesla CEO Elon Musk late last year as the wealthiest person on the planet, according to the Bloomberg Billionaires Index. His wealth was $208 billion on April 19, according to the index.
For decades, Mr. Arnault has run the company with top lieutenants such as Sidney Toledano, who led Christian Dior, and Michael Burke, chief of his biggest brand, Louis Vuitton.
Mr. Burke, 66, stepped down from Louis Vuitton in January to be with his wife before she died from cancer. Mr. Toledano, 71, is expected to give up his role running a stable of the group’s fashion brands, including Celine, Loewe and Marc Jacobs, in the coming months.
Both played key roles in mentoring Mr. Arnault’s children. He tends to pair them with executives who keep an eye on their performance. He will then ask, Mr. Toledano said, “about some of their character traits, or if there’s a need for a little correction.”
Delphine Arnault worked for 12 years at Dior under Mr. Toledano. She then joined Louis Vuitton in 2013, paired with Mr. Burke, who has long worked at her father’s side. Speaking at a farewell tribute for Mr. Burke in January, according to people present, she said it was “impossible to recall precisely my first memory of you. That’s quite logical after all because I’ve known you since I was born.”
Days later, Ms. Arnault attended Dior’s fashion show in Paris as she prepared to take over as the brand’s chief executive. She has an uncanny resemblance to her father, possessing his genteel manners, high forehead and a frame that is tall and slender.
She went backstage, where she offered an assessment of the handbags that had just gone down the runway. Glossy materials, she said, were making a comeback. The collection, she said, was “very elegant. A bit romantic.”
Mr. Toledano looked on like a proud dad. “She survived the Toledano-Michael tandem,” he said. “She’s vaccinated now. She’s received the two doses.”
Mr. Arnault hardly ever speaks about succession in public. People close to him say it has been on his mind for decades.
In 2003, he made a hospital visit to his close friend and tennis partner Jean-Luc Lagardère, who had undergone a hip operation, the people said. Mr. Lagardère was one of France’s most respected businessmen, having built an empire that included missile-maker Matra and publisher Hachette.
Two days later, Mr. Lagardère slipped into a coma after developing an infection, and died shortly thereafter. The executive, who was 75, hadn’t adequately prepared his succession. In the years that followed, his son Arnaud gradually sold off or relinquished what his father had built.
Mr. Arnault recently took steps to tighten his family’s grip on LVMH and pass it on.
In December he transformed Agache, the private holding company that ultimately controls LVMH, into a commandite, a French corporate structure that resembles a limited partnership and allows its controlling shareholder to wield significant power with a relatively small holding.
He also created a second entity, Agache Commandite SAS, that is owned by his five children, each with a 20% stake, according to France’s stock market regulator. The new company is empowered to take over the running of Agache and effectively end Mr. Arnault’s leadership of the company. Major decisions, such as dissolving Agache, require unanimous approval from his children.
The new company has a rotating two-year chairmanship among the children, who can’t sell their shares in it for 30 years without unanimous board approval. Once that period lapses, only direct descendants of the elder Mr. Arnault will be able to hold the shares.
One businessman who has known Mr. Arnault for decades compared the situation to Jean-Paul Sartre’s play “No Exit,” where the main characters are locked in a room together for eternity as punishment.
Mr. Toledano said he was confident the Arnault children can work through any disagreements because their father taught them from a young age to put the interests of the company first. “For now, they all get on great,” he said.
The children all consider themselves siblings and don’t refer to one another as a half brother or half sister, according to people familiar with their relationship. They are careful not to create any appearance of rivalry or conflict, these people said, adding that the five would never discuss or joke about who was best at something like tennis or piano—their father wouldn’t stand for it.
Mr. Arnault is “above all a pragmatic man,” Mr. Toledano said. “You have to choose whoever is best at a given point in time considering the challenges. It’s what he does with his managers, his advisers, and I think it’s what he’ll do with his children.”
It isn’t a given that LVMH’s future leader will be one of Mr. Arnault’s children, according to Mr. Toledano. “At no moment did he tell me, ‘I must prepare my children for my succession,’” he said.
Bernard Arnault was born in 1949 in Roubaix, near the Belgian border. His father, Jean Arnault, was a manufacturer and owner of the civil engineering company Ferret-Savinel.
He excelled at school and earned a spot at the Ecole Polytechnique, a highly selective engineering and science school that has shaped the elite since the French Revolution. Napoleon Bonaparte turned Polytechnique into the military academy it remains to this day.
Mr. Arnault and the 312 other students in his class would wake at 7 a.m. to a bugle and a flag-raising. He learned to march wearing the bicorne hat of the Napoleonic era that students don each year as they proceed down the Champs-Élysées in the Bastille Day parade.
Mr. Arnault recalled in a book of interviews with a French journalist how his education at Polytechnique helped lay the foundations for his conquest of the fashion world. “It is above all a program that gives you a rational mindset, which allows you to analyse a situation or a problem very quickly,” he wrote, adding that LVMH makes a point of recruiting young talent from the school.
Antoine Arnault was more blunt about his father’s esteem for the school. In an interview with Le Monde, the contents of which were confirmed by a spokesman, the eldest son recalled how hard it was to tell his father he wasn’t Polytechnique material. Neither he nor his sister attended the school.
“For him, only Polytechnique counts,” he added.
Mr. Arnault had Antoine and Delphine with his first wife, Anne Dewavrin. As a young father, he took a rigorous approach to his children’s education. They recount how he would call them into his office and drill them on math exercises in between business meetings.
Mr. Arnault moved his family to New York in the early 1980s after the Socialist leader François Mitterrand was elected president of France and vowed to tax the rich heavily. He spent two years in the U.S. building the business he had taken over from his father.
Returning to France in 1984, Mr. Arnault made his first move into the luxury business, gaining control of a textile company called Boussac Saint-Frères that was near bankruptcy. Tucked within it was a jewel: Christian Dior.
Dior became the archetype of Mr. Arnault’s budding empire. The haute couture house had redefined womenswear in the mid-20th century with the “new look” dress, and Mr. Arnault aimed to emphasise that fashion pedigree through aggressive expansion.
He sent Delphine in her early 20s to work at the namesake fashion house of John Galliano, a star designer who was also creative director of Dior. Mr. Toledano then took her under his wing at Dior. The executive recalled huddling with Delphine and her father before making the pivotal decision to fire Mr. Galliano after he was filmed making antisemitic remarks.
Mr. Arnault divorced in 1990 and later that year met Hélène Mercier, a Canadian concert pianist, at a friend’s house. Driving her home, Mr. Arnault told her about his struggles learning to play a collection of études by Frédéric Chopin. When they met again, for tea at Mr. Arnault’s, she asked him to play Chopin for her.
“He was shaking all over with stage fright but seemed determined to go all the way,” she recalled in her autobiography. “I felt that Bernard was suffering, that he was doing violence to himself to move me.”
The couple married and had three boys. People close to the family say Mrs. Mercier-Arnault applied the same drive to parenting that made her a famous pianist. She pushed her boys in music and in school, waking them at dawn to rehearse and study.
Mr. Arnault also threw himself into their studies. Mr. Toledano recalled a flight he took with Mr. Arnault back to Paris after a particularly gruelling trip to Asia. Mr. Arnault, operating on just a few hours’ sleep, pulled out a mathematics textbook and began to study. One of his younger sons was about to take the entrance exam to Polytechnique.
“I need to refresh my memory,” he told Mr. Toledano.
Alexandre Arnault applied to Polytechnique for undergraduate studies but didn’t make the cut. He was later accepted at the school for a master’s-degree program.
At LVMH, he quickly established himself as someone with his father’s ear. When he suggested buying German luggage maker Rimowa, his father told him the brand’s family owners didn’t want to sell. Alexandre wrote to the Rimowa family’s patriarch and traveled to meet with him, according to LVMH executives.
LVMH bought the company in 2017, and Mr. Arnault installed Alexandre as CEO. He gave the brand a makeover by forging collaborations with streetwear-savvy designers. One collection had the Supreme logo emblazoned on luggage. Another had a clear case designed by Virgil Abloh for his Off-White brand.
Mr. Arnault then sent Alexandre to help shake up Tiffany & Co., acquired in 2021 for $15.8 billion. Known for its engagement rings, the jeweler has struggled to gain traction with younger shoppers. Alexandre spearheaded a collaboration between Tiffany and Nike Inc. to make $400 Nike Air Force 1 shoes in all-black leather with a swoosh the color of Tiffany’s classic blue jewelry boxes. Ads proclaiming the brand was “Not your mother’s Tiffany” were plastered across the U.S.
The moves ruffled fashion executives who worried he was tarnishing a prestigious luxury brand. “Why on earth would Tiffany want to move away from that to become just another streetwear brand is beyond me,” said Ana Andjelic, former chief brand officer at Banana Republic.
Mr. Arnault’s two youngest children have hewed most closely to their father’s career track. Both attended a Jesuit high school, where they took literature classes taught by Brigitte Macron before she became the first lady of France.
Frédéric Arnault trained in classical piano and excelled at tennis. He was accepted at Polytechnique, where he took the same courses as his father. He then co-founded an electronic-payments startup, which he sold 18 months later.
In 2018, the elder Mr. Arnault recruited Stéphane Bianchi, an executive who had groomed an heir of the Yves Rocher cosmetics company, to lead LVMH’s watches business. Mr. Bianchi said Mr. Arnault told him from the start to work closely with Frédéric, who at the time was driving TAG Heuer’s digital strategy. Two years later, Mr. Bianchi made him CEO of the brand.
“My father, of course, gives me advice, but he also gives me a lot of freedom,” Frédéric said in an interview. In meetings, he has his father’s tendency to let others do the talking while he studies them, according to Mr. Toledano.
“He looks at you and he absorbs you. Sometimes he lets you talk for 10 minutes while he just absorbs,” he said.
Frédéric has a close relationship with his younger brother Jean, according to people close to them, helping to cultivate the 24-year-old’s fascination with the watch world. Jean went to the Massachusetts Institute of Technology to study financial mathematics. He then earned a master’s degree in mechanical engineering from Imperial College London, writing his thesis on the Tag Heuer carbon balance spring, a component of its watches.
He now works at Louis Vuitton’s watches division, spending much of his time at its factory in Switzerland. In March, he announced plans to relaunch the Gérald Genta brand with the support of the watchmaker’s widow.
In recent years, Mr. Arnault has tapped his children for advice on some of the more delicate issues facing his company. As inflation began to bite last year, fuelling public anger over wealth inequality, Mr. Arnault was worried the public outrage would ripple toward their family and LVMH, according to people close to him.
He went to his eldest son, Antoine, who had been pushing him to communicate more openly with the public about LVMH’s operations, the people said. Antoine suggested LVMH launch an ad campaign publicizing how much the company paid in French taxes last year and the number of jobs it created, the people said. His father took the advice.
This year, Mr. Macron triggered massive street protests with his plan to raise France’s retirement age. Photos of Mr. Arnault began appearing on “wanted” posters at the demonstrations, and protesters stormed into the lobby of LVMH’s headquarters, waving flares and flags. In the days that followed, Mr. Arnault began running his ad campaign in Libération and other leftist newspapers.
The luxury titan also asked his children for advice on how to handle the departure of Mr. Burke from Louis Vuitton, according to people familiar with the matter.
Mr. Burke, who remains an adviser to Mr. Arnault, built Louis Vuitton into a brand with $20 billion in annual sales while navigating personal tragedy. Virgil Abloh, the brand’s creative director for menswear, was diagnosed with cancer around the same time Mr. Burke’s wife, Brigitte, received a cancer diagnosis.
Brigitte Burke and Mr. Abloh bonded over their experience in the months leading up to the designer’s death in November 2021. The designer was a trend-setter in the fashion world. Brigitte was known for bringing employees together for meals.
“She did the cooking. I did the serving,” Mr. Burke said.
Mr. Burke needed to be at his wife’s side before she died in February. Mr. Arnault decided Pietro Beccari, who was CEO of Dior, would take over at Louis Vuitton. Delphine Arnault would become the new chief of Dior.
In late January, Louis Vuitton employees gathered at the Louvre, where the brand had just held its menswear show, for a private tribute to Mr. Burke.
“I’m very touched to be here,” Delphine Arnault told the group, according to people present, as her father and Mr. Burke looked on. One of her earliest memories, she said, was of Mr. Burke’s mustache. She showed them a photo of a young Mr. Burke in the 1980s, adding: “We’ve all learned so much by your side.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

An opulent Ryde home, packed with cinema, pool, sauna and more, is hitting the auction block with a $1 reserve.

French luxury-goods giant’s results are a sign that shoppers weren’t splurging on its collections of high-end garments in the run-up to the holiday season.