This Country Will Police ‘Shrinkflation’ at the Supermarket
South Korea will soon require companies that slim down products to show the old and new sizes on packaging

 3 min
SEOUL—Food prices have risen so much that Kim Soo-yeon has developed a suspicious new habit at the grocery store. She has taken to shaking bags of her favourite brands of potato chips to see if they feel lighter.
“If companies are reducing the amount of food by unnoticeable amounts, it feels deceptive,” said the 32-year-old office worker in Seoul.
South Korean authorities will soon be backing her up in the supermarket aisles.
Seeking to temper the effects of inflation, many countries have sought to use political pressure to dissuade food makers from gouging consumers—with higher prices or lower volumes. South Korea is taking things a step further.
Starting next year, the country will require companies to disclose on their packages and websites when grocery items drop in volume, but not price. To ensure firms comply, South Korea is establishing a dedicated price-investigation team to monitor any fluctuations. Officials are considering levying fines, too.
South Korea’s muscular response to “shrinkflation” reflects how a sluggish economy—its projected full-year growth of 1.4% is roughly half that of other wealthy countries—has become a major problem for President Yoon Suk Yeol, whose approval ratings remain stuck in the mid-30s. Those unhappy with Yoon most commonly cite economic issues.
The new proposals to fight shrinkflation came as the government unveiled an initial list of violators. Following a monthlong investigation, authorities said the offerings of everything from beer to Vienna sausages to dumplings had quietly gotten smaller. Some 16 variants of flavoured almonds had shrunk, too.
Choi Si-yeon, a 28-year-old office worker, said she was angry when she found out about what had happened with her favorite wasabi-flavored almonds. Each bag contained 20 grams less, a seemingly undetectable amount.
“If they had raised the price, at least some consumers would notice,” Choi said.
The maker of the snack, a South Korean firm called HBAF, for Healthy But Awesome Flavors, said it had disclosed the product-size changes on its website. The firm pointed to the pandemic, a rise in labor costs and almond prices as factors.
Other companies also claimed to have made online disclosures or argued the slimmed-down offerings were part of flavour revamps.
Shrinkflation backlash has emerged elsewhere, too. France’s second-largest supermarket chain, Carrefour, has put up bright orange signs to highlight products it deems subject to shrinkflation since September. In the U.S., Sen. Bob Casey (D., Pa.) recently issued a report on shrinkflation, citing facial tissues and Oreos as examples.
With costs rising, what is often lacking is transparency over potential changes, creating room for a sense of injustice when shrinkflation occurs, said Rajiv Biswas, chief economist for the Asia-Pacific region at S&P Global Market Intelligence. “Consumers can’t check the website of hundreds of products,” he said.
Headline inflation in South Korea topped out at 6.3% in July 2022 from the prior year, below the recent peaks of 9.1% in the U.S. and 11.1% in the U.K. But food prices in the East Asian country had remained relatively low for decades, so the recent upticks have triggered outsize anger. Wages haven’t kept pace with rising prices. The country’s housing market—the main source of wealth for many South Koreans—has stagnated.
A majority of South Koreans plan to spend less money next year, according to a recent poll, with nearly half of respondents citing inflation as the chief reason.
Low inflation had been a particular policy priority for South Korea over the decades, helping the country’s export-heavy economy maintain a good environment for private investment, said Randall Jones, a former senior official at the Organization for Economic Cooperation and Development who led the group’s economic reports on South Korea.
“People aren’t used to inflation in South Korea,” said Jones, who is now a distinguished fellow at the Korea Economic Institute of America, a think tank based in Washington, D.C.
South Korea is conducting daily price checks for more than two dozen staple items such as milk and ramen noodles. The country’s antitrust regulator will list any shrinkflation examples on a newly created website and will handle enforcement of the new measures. The government wants to ink agreements with large South Korean retailers to build a joint monitoring system for some 10,000 everyday items.
That sliced cheese and other inexpensive items were among the first named shrinkflation violators irks people like Lee Hyun-woo, a 23-year-old university student. “If even processed food is shrinking, I feel betrayed,” Lee said.
In recent weeks, the country’s shrinkflation suspicions have touched everything from the cubed white radish accompanying Korean fried chicken to the cream density of a slice of strawberry cake.
Kim Young-hee, a 42-year-old homemaker, is glad about more government transparency. But the extra knowledge likely won’t change her habits, such as her occasional purchase of honey-butter almonds for her children.
“I’ll still buy the almonds,” Kim said, “but I don’t want to be tricked.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Warmer minimalism, tactile materials and wellness focused layouts are redefining luxury interiors as homeowners design for comfort, connection and lasting appeal.
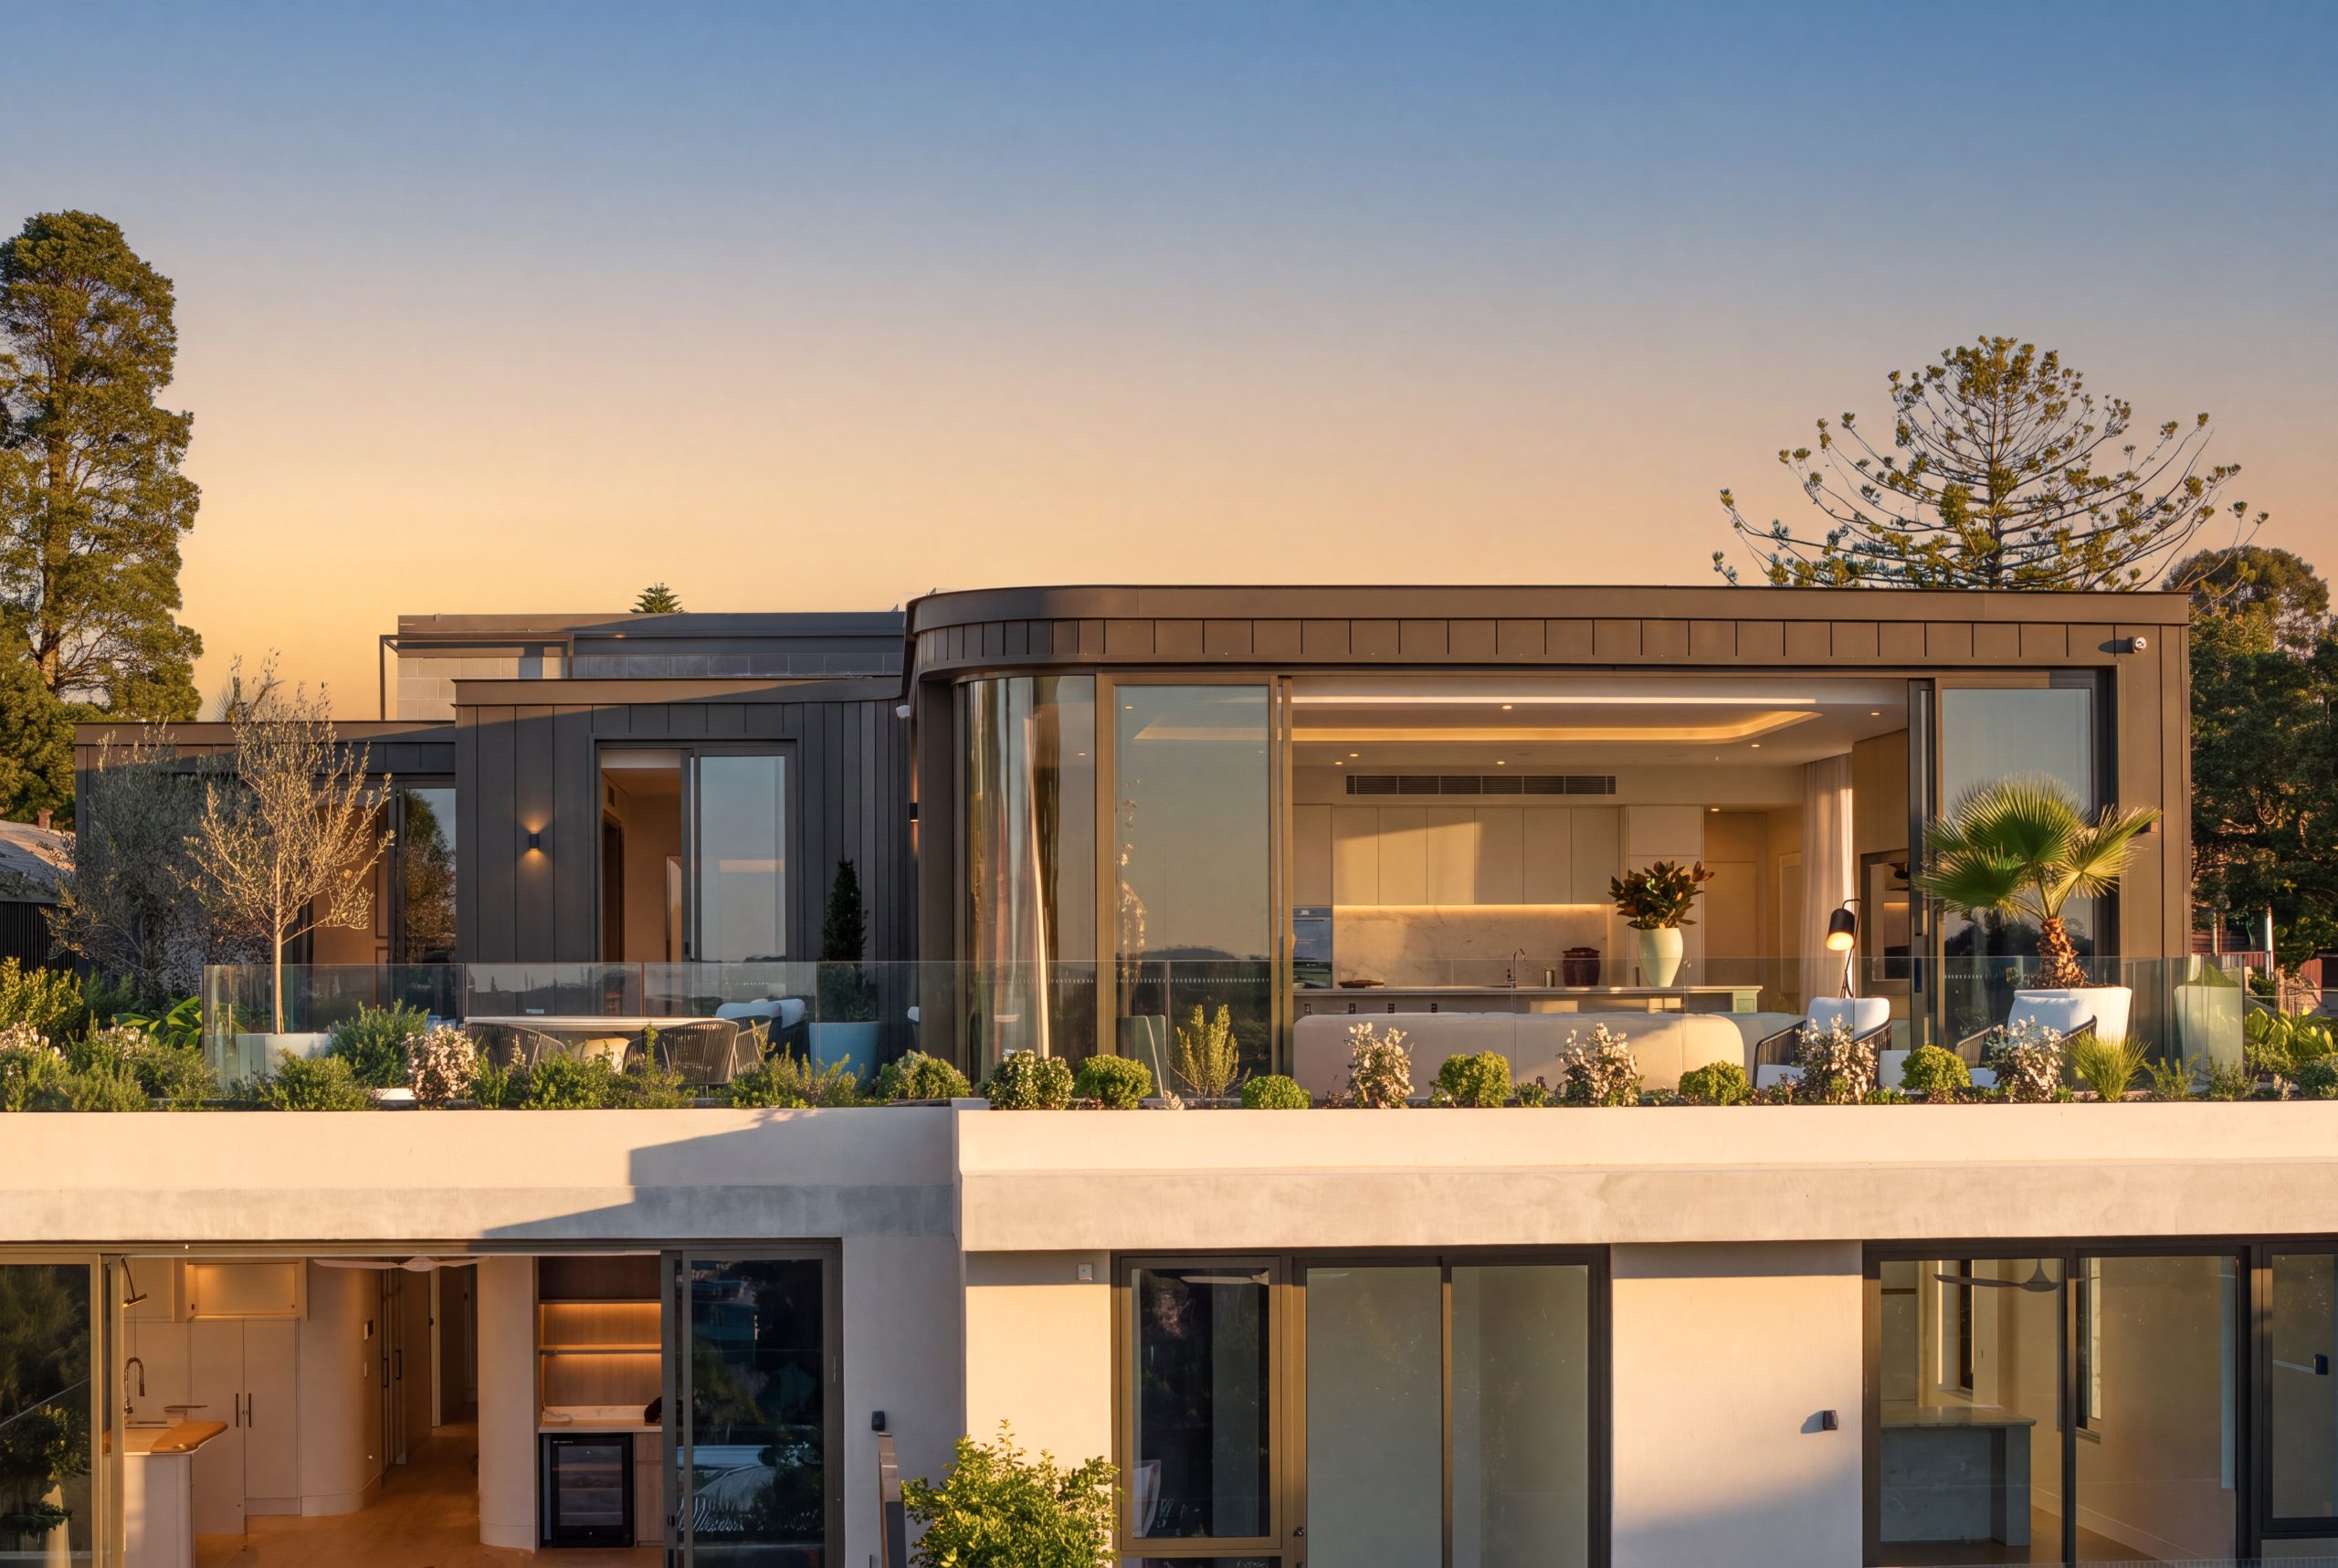
The completed penthouse at Park Residences showcases a considered approach to luxury apartment living, combining northern light, curated interiors and the privacy of a whole-floor residence.