Trump Administration Could Bring an Economic ‘Detox.’ What It Means for Stocks.
Investors may have nothing to fear but fear itself. But sometimes fear is more than enough.

 4 min

As another week begins with more selling–all three major indexes are falling, with the Nasdaq Composite hit hardest–fear is undoubtedly running high in the market. The Cboe Volatility Index, Wall Street’s fear gauge, jumped 15% to 27 on Monday morning. That would be its highest close since Dec. 18, when it was at 27.62.
Uncertainty about government policy and the health of the economy is overshadowing positive data.
Tariffs are one part of the problem. Not only are they disruptive to global trade and lead to higher prices, but President Donald Trump has walked back their implementation and doubled down enough to give the market whiplash. And then there are worries about huge cuts to federal spending, including mass firings and slashing outlays for programs, with a budget fight that could lead to a government shutdown at the end of the week.
Investors have little incentive to keep the faith, especially because signs of economic weakness are starting to emerge.
“Prior to tariff uncertainty, Momentum factors were leading, and risk factor returns were stable,” notes 22V Research’s Dennis DeBusschere. “ Payrolls and PMI data indicate weaker growth at the same time tariffs are adding to uncertainty about the path of economic data and earnings.” The result is that stocks are swinging wildly, riskier names are out of favor, and defensive shares are the flavor of the month.
According to Sevens Report’s Tom Essaye, “until there’s some movement towards stable policy, the best we can hope for is a churn sideways between around 5,700 and 6,000 in the S&P 500.” The index broke below 5650 in morning trading Monday.
The problem is that the greater the losses, the more the market could be closing in on a “liquidation avalanche,” as Dohmen Capital Research’s Bert Dohmen puts it. The concern is that forced selling, such as to raise cash for margin calls on shares bought with borrowed money, or by money managers desperate to limit losses, creates a downward spiral.
Wall Street famously abhors unpredictability, but even more worrisome may be rhetoric from Washington, D.C., that indicates the Trump administration is fine with causing what it believes will be a short-lived downturn as it pursues long-term goals it considers more important.
Asked whether a recession on the way, the president declined to rule out the possibility. “I hate to predict things like that,” Trump told Fox News’ Sunday Morning Futures. “There is a period of transition, because what we’re doing is very big. We’re bringing wealth back to America.”
Treasury Secretary Scott Bessent, a former hedge fund manager, predicted “a natural adjustment as we move away from public spending to private spending, in an interview with CNBC. “The market and the economy have just become hooked, and we’ve become addicted to this government spending, and there’s going to be a detox period. There’s going to be a detox.”
As T.S. Lombard’s Dario Perkins notes, Elon Musk and others in Trump’s orbit have pointed to Argentina as a successful example of this strategy. President Javier Milei imposed strict austerity measures to combat inflation, leading to a brief recession in 2024.
Of course, “copying the policies of a country that had massive endemic corruption and was on the brink of hyperinflation is, er, problematic,” Perkins writes. “Yes, inflation is a bit high, but not so high that Musk and co should deliberately engineer a recession. Perhaps the new U.S. administration has forgotten what a ‘real’ recession is like.”
The 2008-2009 financial crisis was nearly two decades ago, and the U.S. only rebounded from the Covid-19 downturn so quickly and strongly because of huge government spending. That means it is “odd to see US policymakers talk as if they want to inflict damage on the economy, or at least do things that risk causing damage,” he notes.
The White House didn’t immediately respond to a request for comment.
Damage could snowball quickly. If big government layoffs continue at a time when hiring is already weak, it could lead to a further loss of confidence and even higher unemployment. And as history shows, recessions aren’t always quick or without damage.
“The US is not Argentina, and it is not facing an imminent debt crisis,” Perkins writes. “In any case, does anyone seriously think a recession in 2025 would lower America’s debt trajectory? Every recession I know has had the exact opposite effect.”
The good news is that we aren’t there yet. Earnings have held up well, and while the mention of tariffs in fourth-quarter conference calls was up 40% from their prior peak in 2018, mentions of a recession fell to their lowest point since the first quarter of 2018, as DataTrek Research’s Nicolas Colas notes.
“The dichotomy between record high ‘tariff’ and near-record low ‘recession’ mentions on investor calls neatly reflects the mood of corporate America,” he writes. “The C-suite is struggling to come to grips with tariff policy but remains fairly optimistic on the US economy. So far, anyway…Any change to the latter view would be unwelcomed.”
For his part, TS Lombard’s Perkins isn’t predicting a recession. Sevens Reports’ Essaye notes that concern about tariffs so far has been worse than their effects. While it makes sense to brace for volatility, “that negative scenario is not a foregone conclusion and actual facts on the economy and earnings [are] hanging on.” he says.
22V Research’s DeBusschere highlights that in aggregate, macroeconomic data still point to a very high probability that the U.S. economy is still expanding. “Over the past few weeks though, market internals have weakened to a level more consistent with economic slowdowns/heightened recession risk,” he says. “Markets are discounting a sharp slowdown that is not evident TODAY in actual data.”
The problem is that as long as chaotic moves in Washington, D.C., continue, that won’t matter for stocks.
“Although the U.S. will still likely avoid a recession this year, investor sentiment does appear to be headed toward another recession scare,” writes Paulsen Perspectives’ Jim Paulsen. “An actual recession would probably result in a bear market, but even an ongoing or worsening ‘fear’ of recession will likely magnify the current stock market correction.”
When the market gets clarity about what comes next, prices can recover. But until then, it is hard to see how stocks can rise consistently. Just the fear of a recession is enough to weigh on markets.
Write to Teresa Rivas at teresa.rivas@barrons.com
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
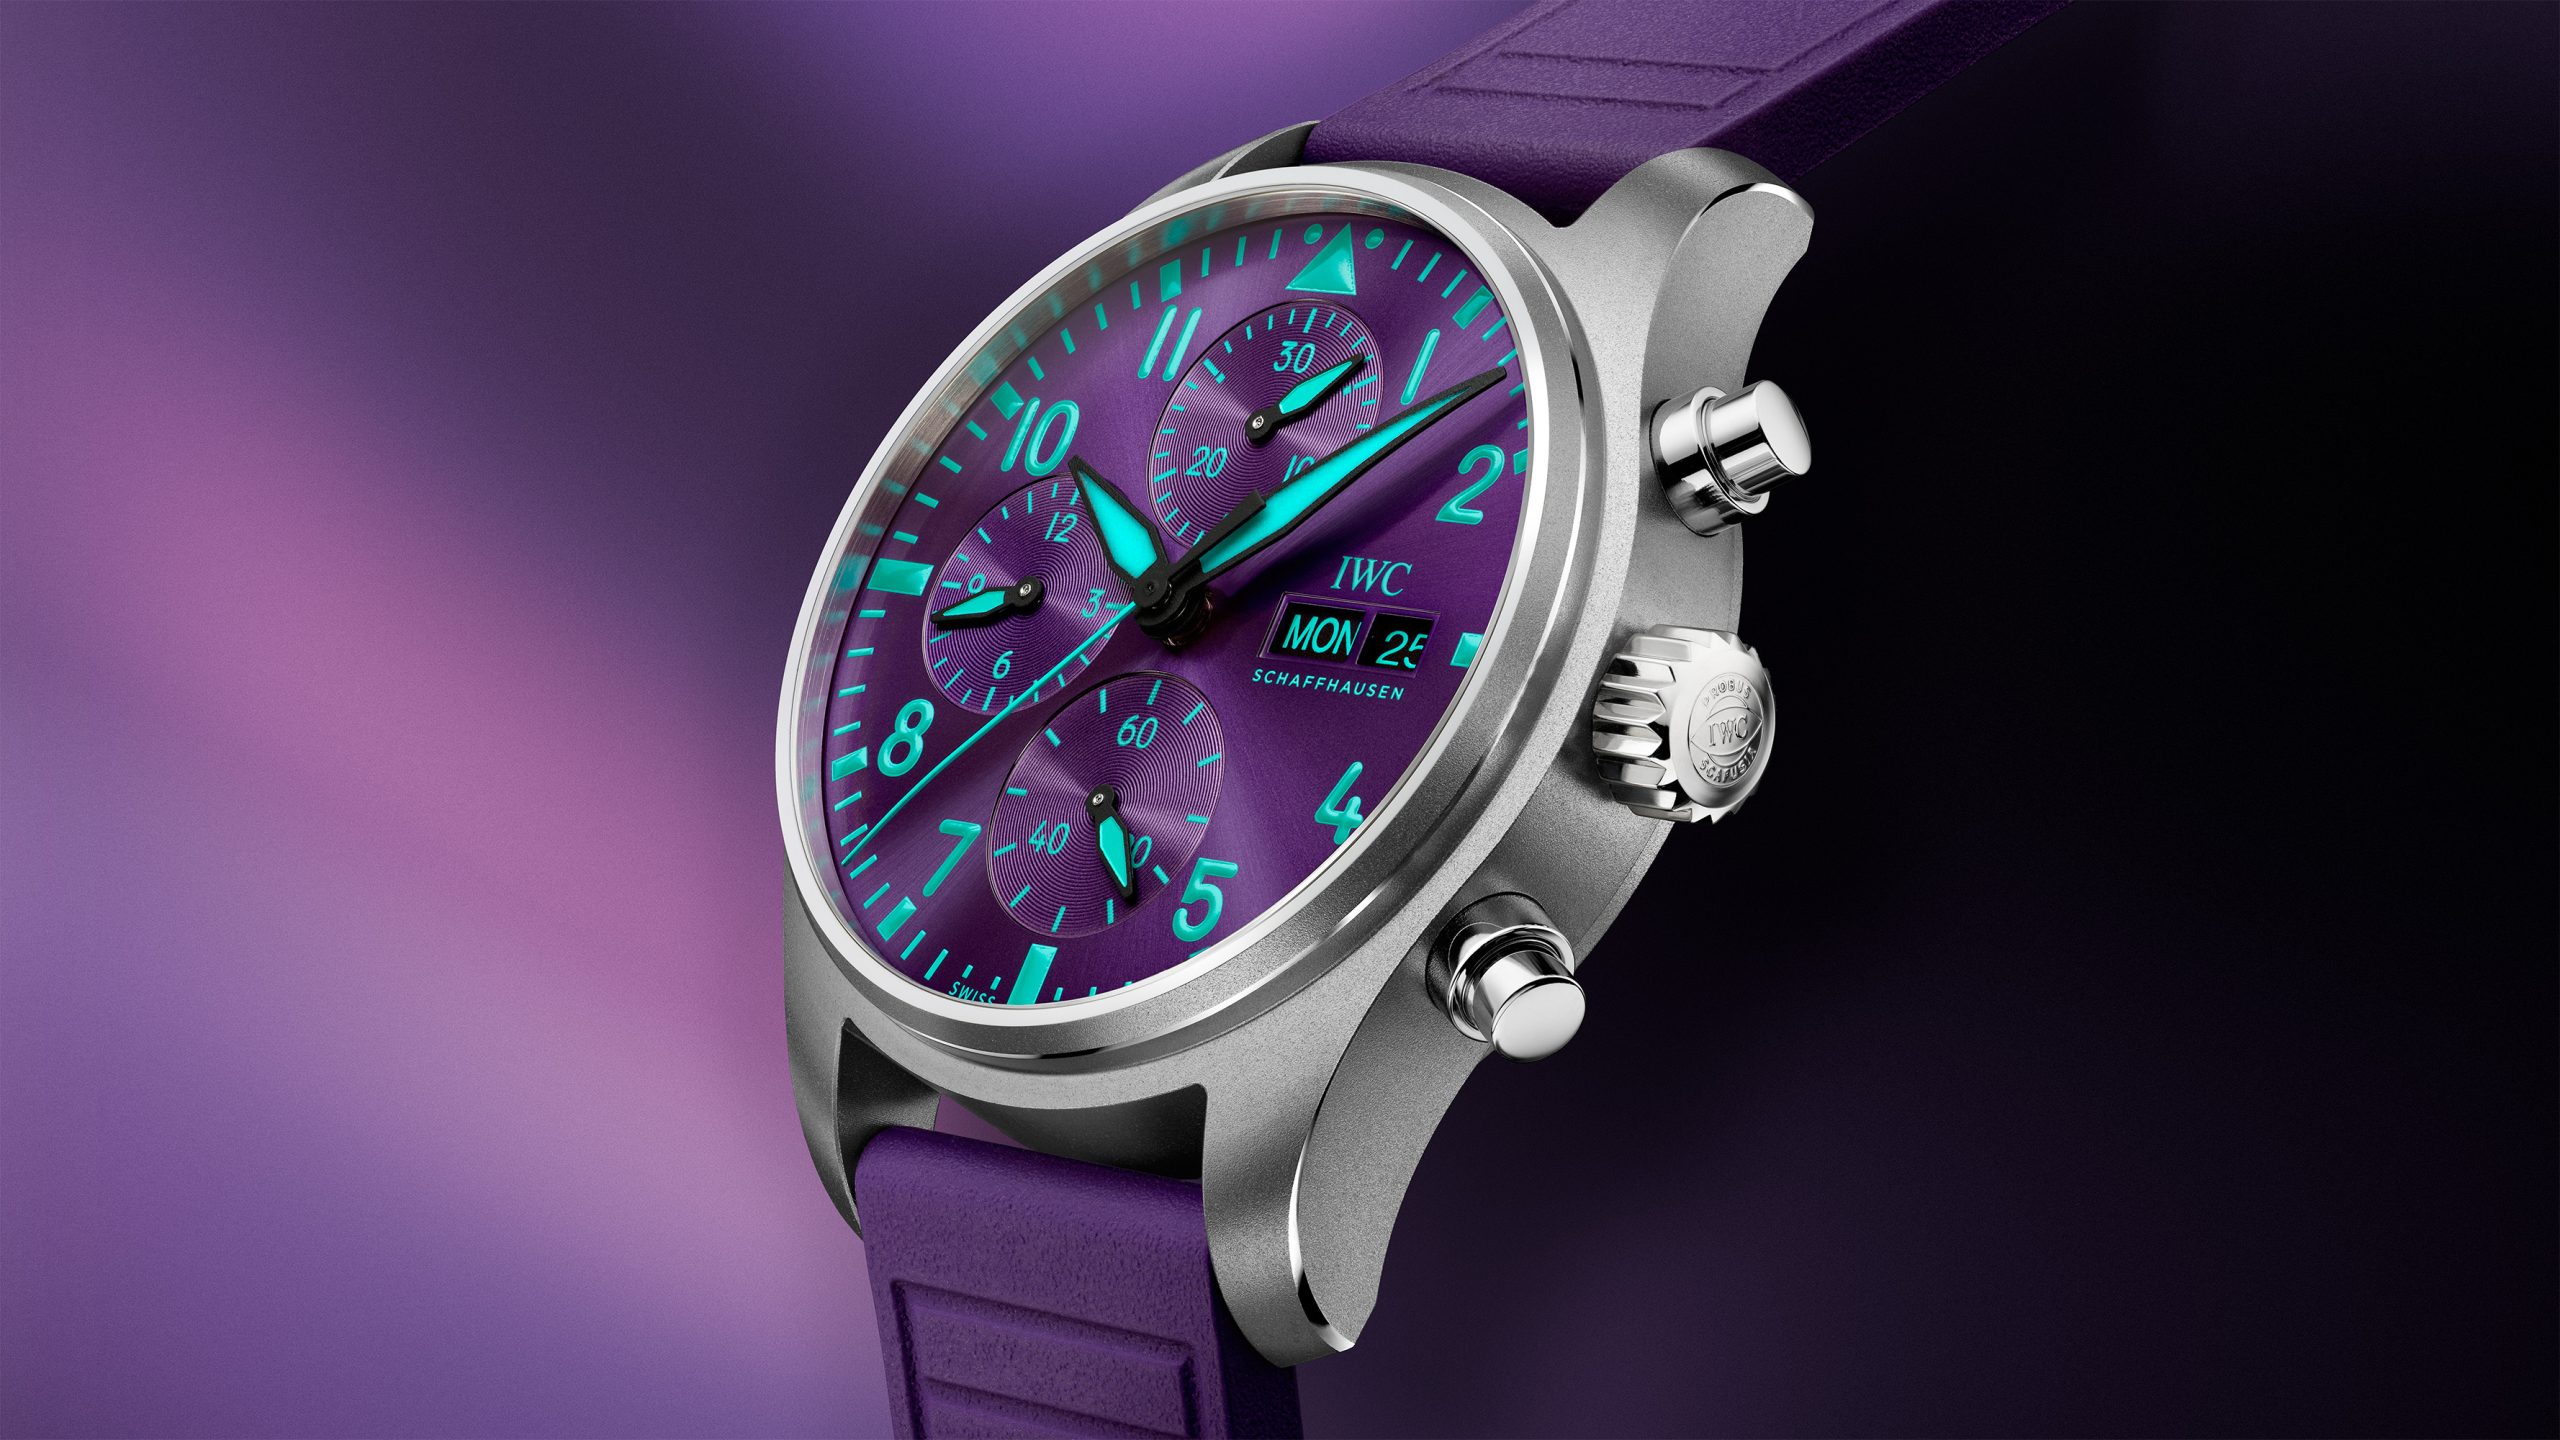
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”

Parts for iPhones to cost more owing to surging demand from AI companies.