

U.S. Companies Face EU Deforestation Rules on Coffee, Wood and Other Everyday Goods
Businesses are bracing for tough new regulations after voluntary corporate efforts failed

 4 min
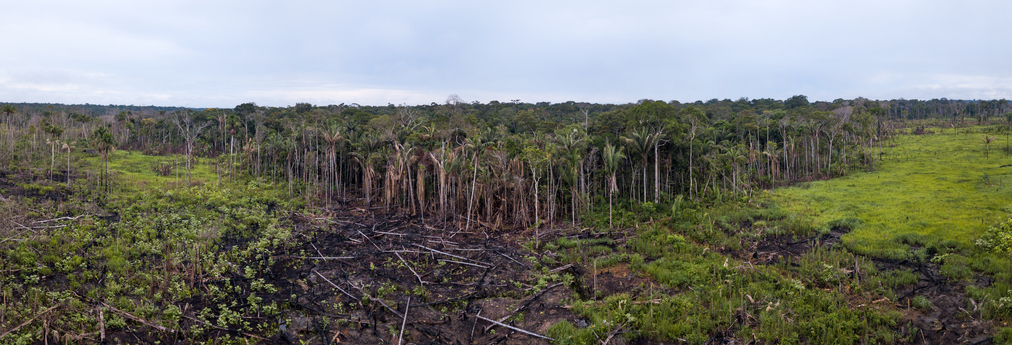
Companies selling everyday products such as leather shoes, coffee and chocolate in the European Union will soon need to prove their wares aren’t causing forest loss under a new law, after voluntary efforts largely failed.
The world’s toughest rules on deforestation come into force Thursday, meaning that companies have 18 months to prepare for proving the origin of seven commodities imported into the EU that are known to drive forest loss: cattle, cocoa, coffee, palm oil, soy, rubber and wood.
Almost 40% of the world’s 500 largest companies using the seven commodities covered by the new EU rules haven’t set a policy on forest loss, environmental nonprofit Global Canopy said in a report in February. The nonprofit estimates at least 37 big U.S.-based companies, including Starbucks and Kellogg, will be covered by the new rules.
“Our team is reviewing the regulations and working with our materials and ingredients suppliers to prepare,” a Kellogg spokeswoman said. Starbucks declined to comment.
Businesses will need to pinpoint the plot of land where the product came from and prove no forests have been cleared on the site since 2020. They will need to provide evidence of due diligence, which will likely include satellite imagery. Planet Labs and Airbus-owned Starling—two businesses that use satellites to monitor land use—said U.S. companies have shown interest in their services because of the new regulations.
Importers failing to meet the new rules face fines of up to 4% of their annual revenue in the bloc. The law requires the bloc’s national authorities to check 9% of shipments coming from countries it considers to have a high risk of deforestation, 3% for nations it labels standard risk and 1% from low risk nations.
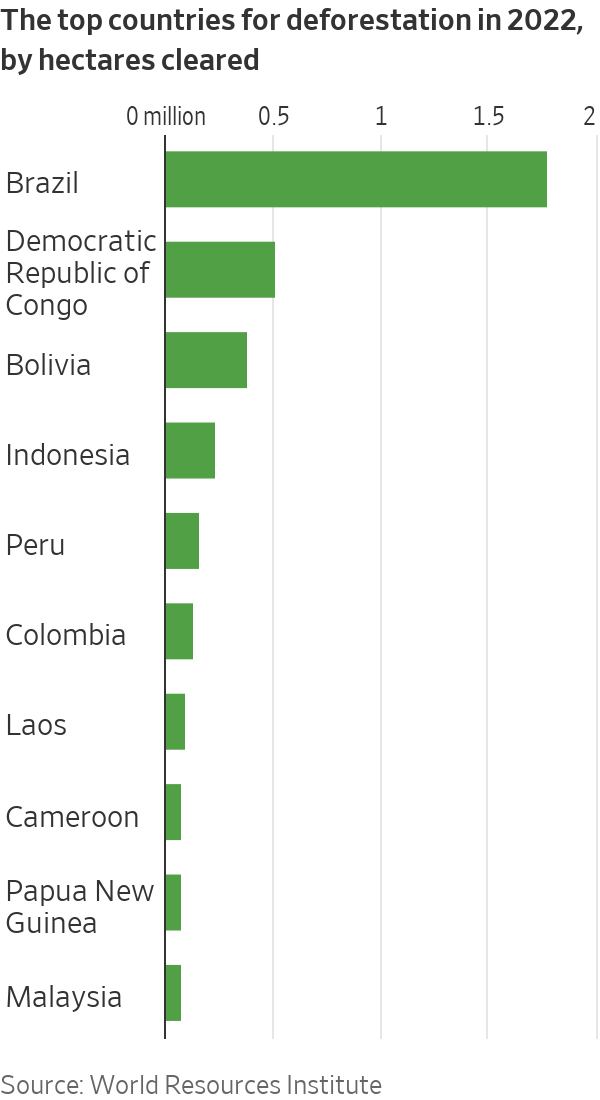
Companies are still waiting for the EU to provide a list of countries designated as high risk. Nations such as Brazil, Indonesia and Malaysia are lobbying against being classified as high risk, fearing the label will hurt trade.
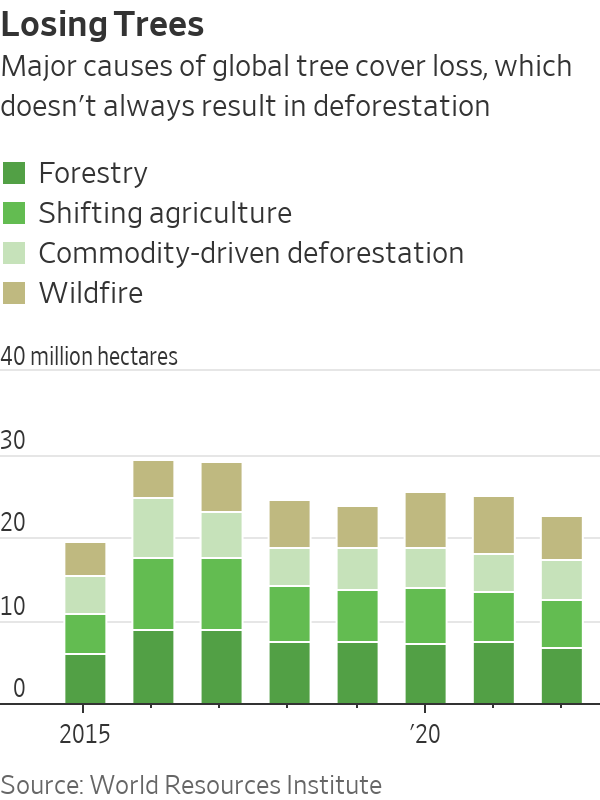
Loss of tropical primary, or mature, forests globally totalled 4.1 million hectares in 2022, the equivalent of losing 11 soccer fields of forest a minute, according to the World Resources Institute.
Many companies struggle to police their supply chains. Voluntary deforestation ambitions have failed, including the Consumer Goods Forum’s 2010 pledge to “achieve net zero deforestation” by 2020. In 2014, more than 200 companies pledged in the New York Declaration on Forests to eliminate deforestation by 2030, but they missed an interim target to halve deforestation by 2020.
Kellogg backed both initiatives and in a 2020 report identified a variety of reasons for the failure, including a lack of coordination between organisations, inconsistent regulations and opaque supplier ownership. It is among the companies working to fulfil the longer-term commitment of the New York Declaration on Forests to eliminate deforestation by 2030.
In 2021, leaders from more than 100 countries agreed to a deal at the COP26 climate summit aiming to end and then reverse deforestation by 2030.
The EU’s regulations aim to reduce the destruction of forests for economic activity and fight global warming. Trees absorb carbon dioxide, and forest loss and damage has caused around 10% of global warming, according to nonprofit World Wildlife Fund.
“Combating deforestation is an urgent task for this generation, and a great legacy to leave behind for the next,” Frans Timmermans, the EU official overseeing the bloc’s climate plans, said when political agreement on the regulations was reached in December.
The EU rules apply to companies meeting the bloc’s broad definition of an “operator,” which includes a business importing into the EU, exporting from it, or putting products on the bloc’s market. Operators can be big agribusinesses such as Cargill and Bunge supplying companies in the bloc, but also EU subsidiaries importing commodities to manufacture and sell products.
Guillaume Croisant, a Brussels-based lawyer at Linklaters, said that because the rules will be enforced by national officials, there could be discrepancies as “some authorities may be harsher.”
The EU has estimated the combined yearly due-diligence costs for importers to comply with the new rules could be as high as €2.6 billion a year, equivalent to roughly $2.8 billion.
Fast-moving consumer goods companies using coffee, cocoa, palm oil and soy could be hit with big compliance costs from the reporting requirements to trace precise geolocations as well as potential reorganisation of supply chains that are unable or unlikely to be compliant, according to an analyst report from Barclays.
The EU rules are expected to become stricter over time. A review on expanding them is scheduled in two years and some policy makers are pushing to have corn added to the list of commodities covered and for the financial sector to be regulated under the rules.
In the U.S., Democrats in Congress are pushing for similar legislation called the Forest Act. Sen. Brian Schatz, a Hawaii Democrat who is spearheading the effort, said the U.S. needs to follow the EU in enacting deforestation regulations on trade.
“If we do nothing, the U.S. market will become a dumping ground for commodities that can no longer make their way into Europe,” he said. “While companies talk a big game on preventing deforestation, we can no longer allow them to police themselves.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.

Margot Robbie and Jacob Elordi star in an adaptation of the classic novel that respects the romance’s slow burn.
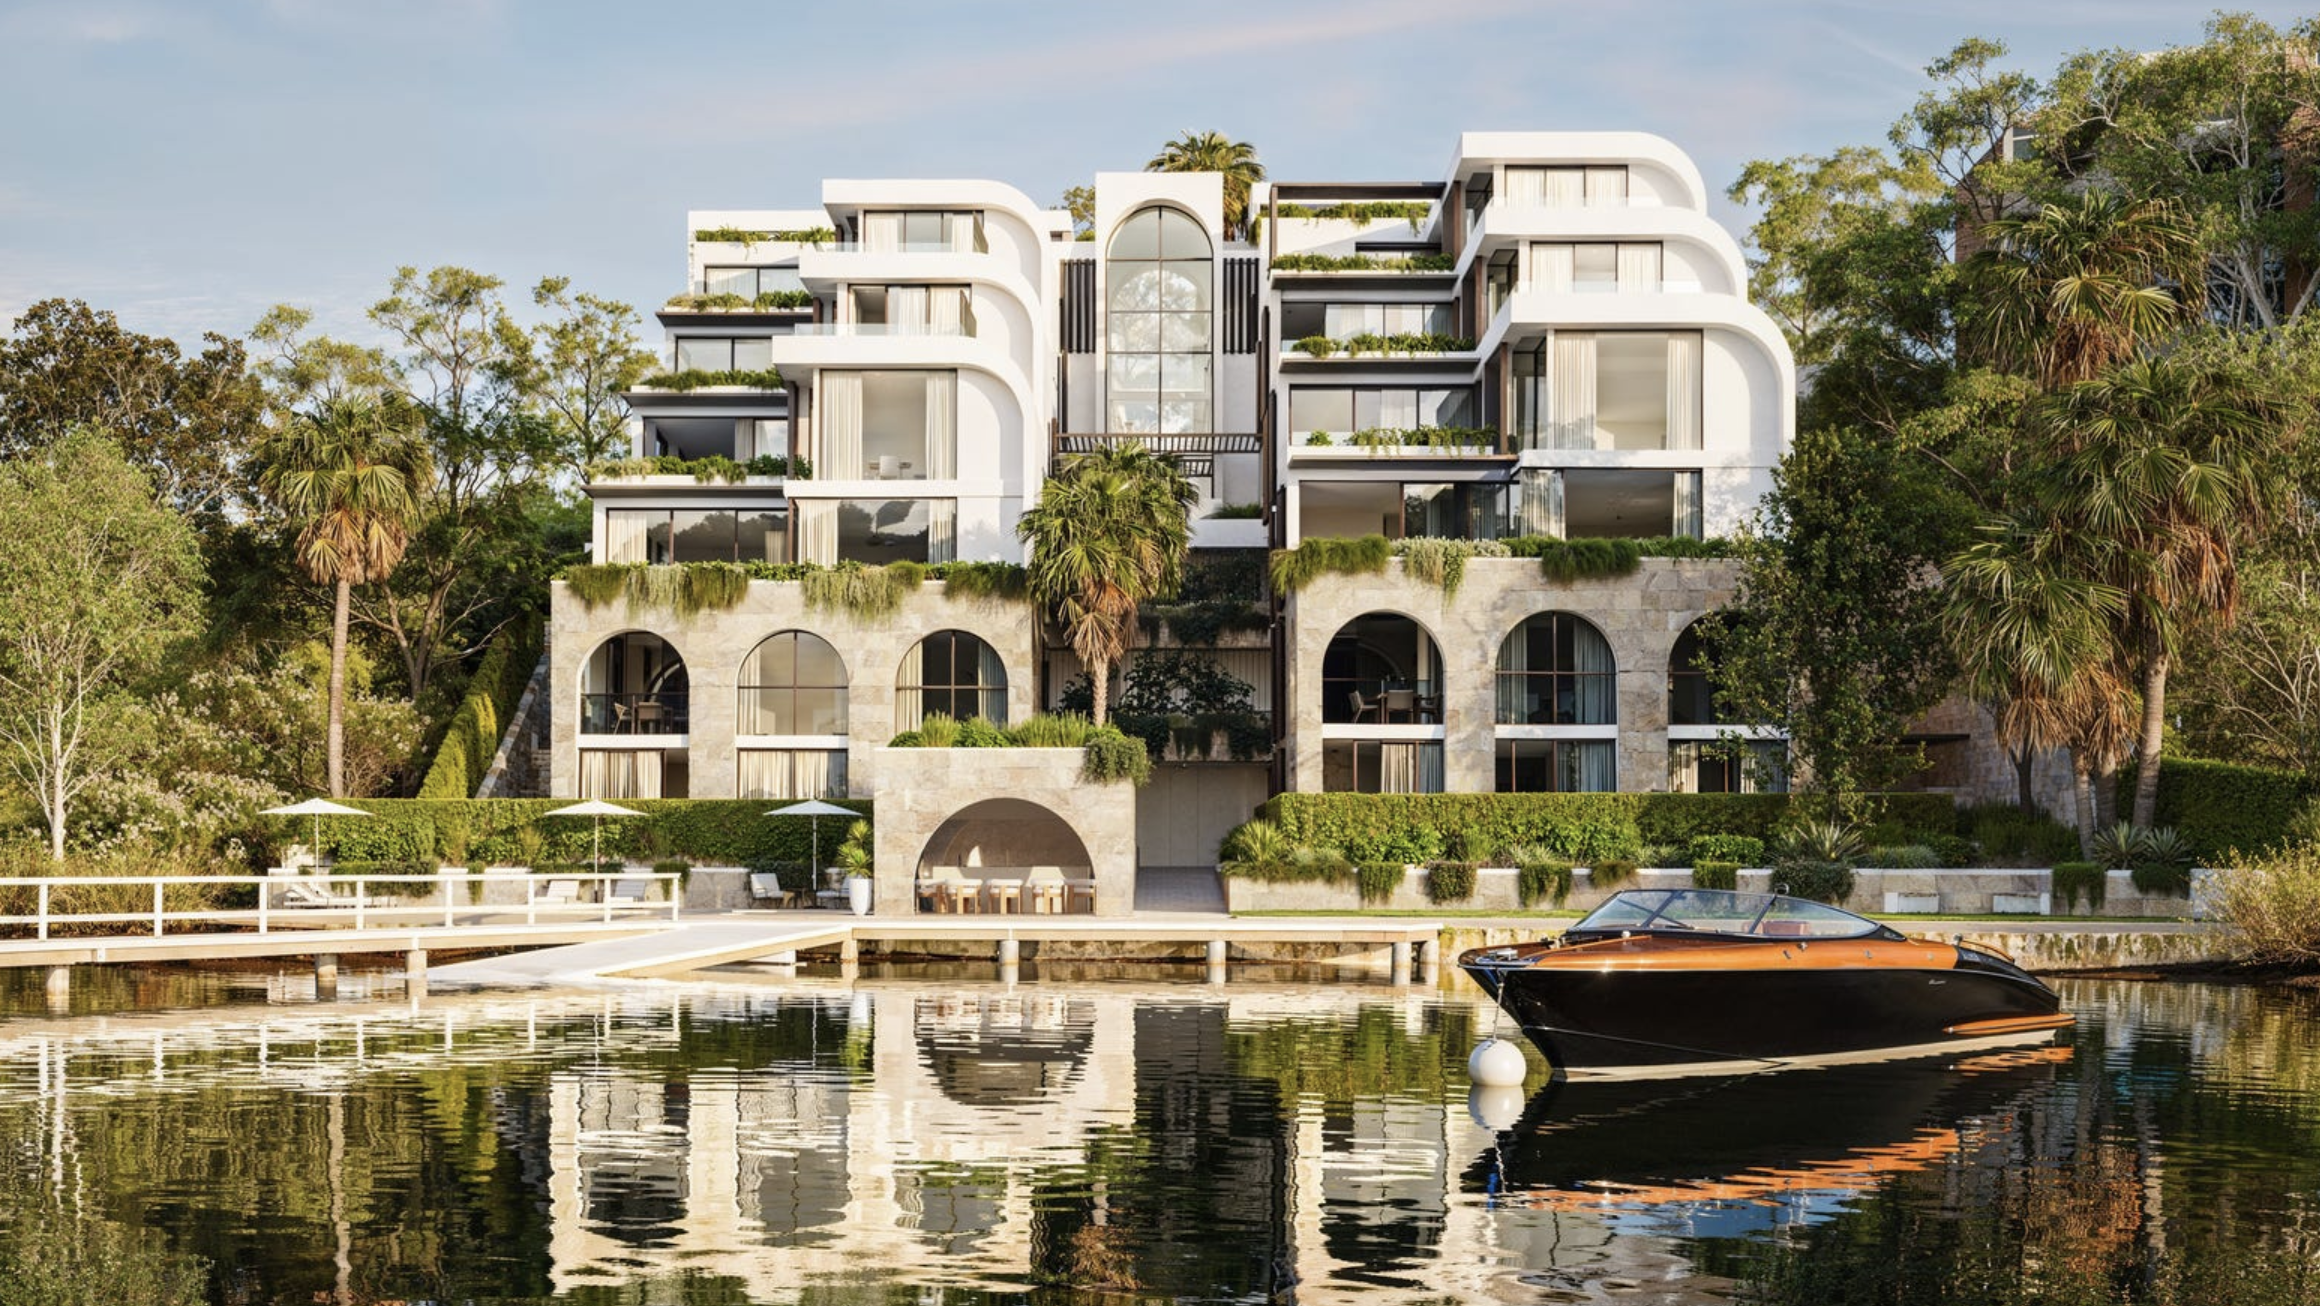
Advertising legend John Singleton unveils an exclusive 16-residence Caroline Bay development, marking his latest high-end property play on the Central Coast.