‘What Was I Thinking?’ The Big-Ticket Items People Regret
People spend a lot of money on all sorts of things, only to later ask themselves: Why?

 5 min
While it may be true that money can’t buy happiness, that doesn’t stop people from trying.
And then wishing they hadn’t.
Many of us have had a big-ticket expenditure that we later come to regret. Maybe it’s something meant to convey status, which we realise later did nothing of the sort. Maybe it was to fulfil dreams of a luxury lifestyle, only to discover that we’ve bought a bottomless money pit.
We asked Wall Street Journal readers to share their stories of pricey purchases that ultimately led to disappointment. Below are some of their stories and reflections—with some free advice to their younger selves.
The wristwatch of his dreams
“It was back in day of wingtip shoes, white shirts and red ties,” says Bryan Desloge, who began his career at IBM in 1984. And like many rookie employees, Desloge wanted to fit in. “I bought suits. I took my earring out. I cut my hair and I registered in the Republican Party,” he says. To complete the look, he paid over $7,000 for the wristwatch of his dreams—a Rolex Submariner. It was a hefty sum, considering he was making roughly $18,000 a year.
Now 64 and retired, Desloge says his younger self saw the stainless-steel watch as a status symbol. “The older guys had nice dress watches already, while I wore a Casio or a Timex.” Just two years after buying the Rolex, however, Desloge realised the timepiece was impractical for him. “The Rolex is great, but I don’t want to look at a clock face,” he says, “and the glow-in-the-dark hands are hard to read at night.”
Desloge, who lives in Tallahassee, Fla., recently tried to give the Rolex to his son, who turned him down. So it remains tucked away in favor of a Garmin smartwatch, which has a fitness tracker, alerts and email, among other features. Purchased for about $500, the Garmin can multitask in ways his Rolex cannot. “I will probably wear that watch for the rest of my life,” Desloge says.
Cabin fever
The family called it “the little brown house,” says Michael Kotas of his vacation cabin in the mountains overlooking Tucson, Ariz. In 2005, Kotas and his wife paid $120,000 for the 1950s cabin, and it needed a lot of work.
“We bought it from an older couple, who had dark rugs and wood paneling,” says Kotas, who is now in his mid-60s and retired from a job in technology sales. He redid the cabin “with a cool Manhattan vibe,” updated the electrical wiring and corrected a flooding issue in the basement. In all, Kotas estimates he spent $60,000 in upgrades.
But his financial headaches were far from over.
Even though Kotas owned the cabin, the federal government owned the land it sat on, since it was located within the Coronado National Forest. Leasing the land cost $800 a year when the cabin was purchased, but eventually grew to $3,600 a year by the time it sold.
During that time, two fires came within 100 yards of the cabin, jacking up Kotas’s fire-insurance premiums. Then, a species of bark beetle attacked ponderosa pines there, and the Forest Service required cabin owners to remove infested trees around their property, costing $1,000 to $1,200 a pop. “I counted all my trees around my house and thought, ‘I can’t afford this.’ ”
Over time, Kotas’s children didn’t want to go to the cabin anymore, saying “there was nothing to do,” he says. “We ended up spending about five nights a year there for the last several years.” Kotas, whose year-round home also is in Tucson, came to the realisation that he wasn’t getting his money’s worth. “It became an albatross,” he says.
The tipping point came when a man parked his truck just 100 feet from the cabin and lived out of his vehicle on the side of the road. Kotas sold the cabin in 2022 for $195,000.
“I would probably never buy a vacation home again,” he says. “It was a tough lesson to learn. I wish the [new] buyers well, but all I can say is, ‘Good riddance!’ ”
RV to nowhere
After retiring from a career in ophthalmology, Gordon Preecs bought a large pickup truck in 2013 and a 22-foot travel trailer in 2017 with the dream that he and his wife, Connie Preecs, would visit national parks around the country. Combined, the new vehicles cost around $50,000.
Living in Seattle at the time, the couple started out by taking the RV on short trips, such as an event for woodcarvers in Washington state. It didn’t take long for them to feel pinched in a 120-square-foot RV. “I thought we’d have our own hotel” with an RV, says Preecs, who is now 75 and living in Round Rock, Texas. “But we had to just shove things in there. The kitchen counter was hand’s breadth wide, and the bathroom was like a phone-booth shower. If I dropped the soap, I couldn’t pick it up.”
Three years after purchasing the trailer, Preecs and his wife relocated to Texas to be closer to their grandchildren. Still, they were able to visit Grand Teton and Yellowstone national parks in the Northwest. That’s when they felt the financial pinch of RV ownership.
“At 6 miles per gallon and $60 to $80 a night at RV parks, the expenses really added up,” he says. “We found it was an inefficient way to travel.” Some of the RV parks are located in funky, backwater places, he says. And setup and breakdown at every stop became a hassle. “You want to be free, but you’re not.”
In 2020, they sold the trailer, which had less than 5,000 miles of use, and the pickup for a combined $32,000. With the proceeds, Preecs bought a Tesla.
Outfitted and outwitted
As a vintner in California, much of Pam Starr’s work takes place outside among the grape vines. “I live in jeans and winemaker vests, T-shirts and sometimes boots,” says the 63-year-old. “So I can tear my clothes on a vine or get barrel slime on me” and it doesn’t really matter.
A few years ago, a well-heeled friend with an eye for fashion convinced Starr, who lives in Napa, to join her in San Francisco for a meeting with her couturier—a person who creates luxury clothing to the client’s specifications. The friend had told Starr that she wouldn’t have to buy anything, but this particular couturier was very persuasive, Starr recalls.
For example, the couturier held up a gauzy swimsuit coverup with white sequins and said, “You have to wear this swimsuit coverup by the pool.” Starr paid $1,800 for a custom coverup, but later it hit her: “I don’t wear a coverup when I’m at the pool because I’m actually in the pool.” To this day, it has never been worn. Starr says she spent another $1,800 for an off-the-shoulder silk shirt with three-quarter length sleeves.
The quality of the clothing was low, Starr says. “That silk shirt turned out to be my most disappointing piece,” she says. It didn’t clean well, and hasn’t retained its shape. Many of the pieces she purchased haven’t held up well, she says, even though she rarely wears them. “Out of the 15 items I had made for me, I loved maybe three,” Starr says. “That’s more than $20,000 worth of clothes, and I should have gotten more out of them.”
If she could go back in time, Starr says, she would say to herself, “ ‘Listen, Pam. Pick two things and start slowly. If you like them, you can expand into other things.’ ” Also, she would pause to ask herself how often she would actually wear the clothing.
“Because of a friend, I ended up in a couture shop,” Starr says. “In that world, it’s uncharted territory for me. The couturier pulls you in really hard.” Knowing what she knows now, Starr says, “if I needed someone to design a gown for me, I wouldn’t go back there. I would go to a seamstress locally.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Exclusive eco-conscious lodges are attracting wealthy travellers seeking immersive experiences that prioritise conservation, community and restraint over excess.
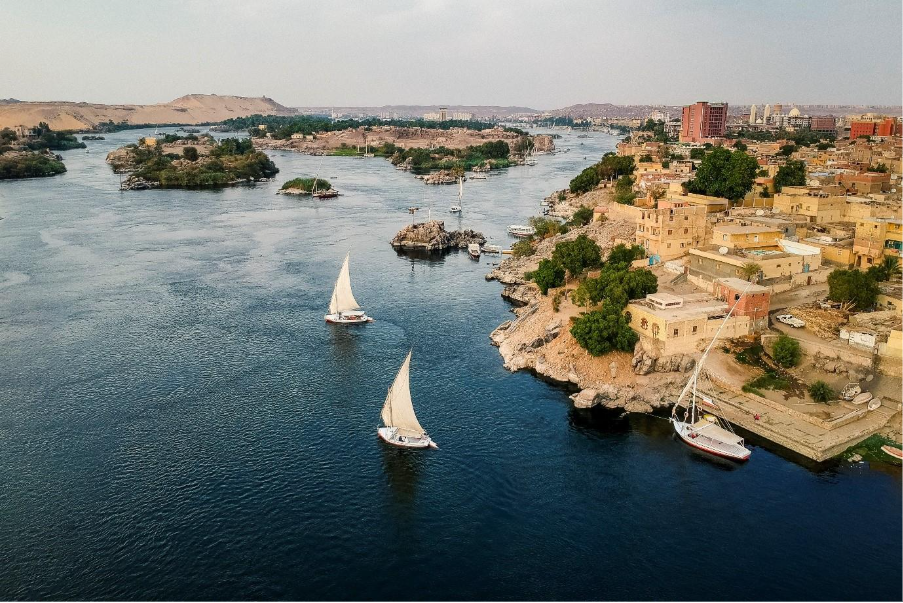
A resurgence in high-end travel to Egypt is being driven by museum openings, private river journeys and renewed long-term investment along the Nile.