

When It Comes to Marriage and Money, Opposites Attract
Spouses reshape each others’ financial behaviour, for richer and poorer, marriage research suggests

 3 min
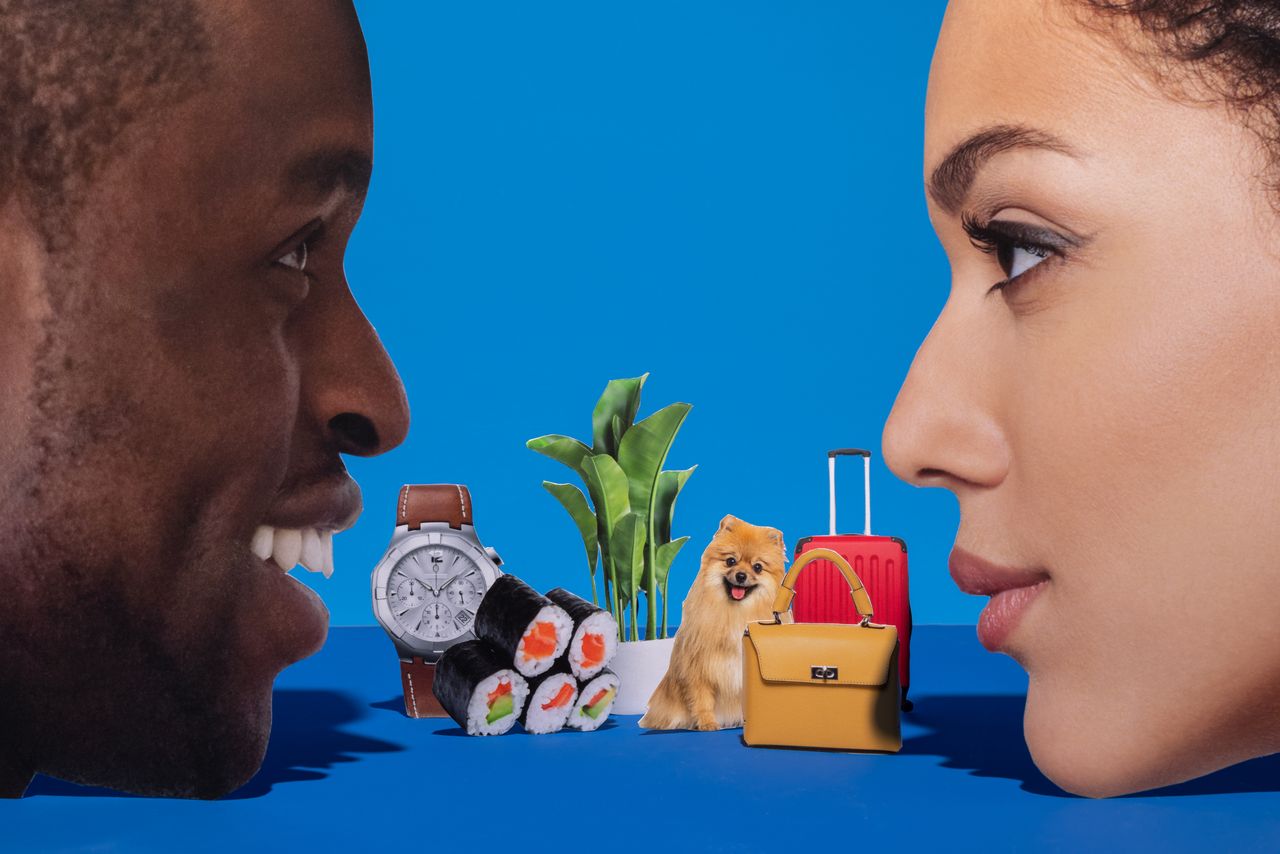
The person you marry will often change your relationship to money.
We tend to choose our partners based on shared values, in-common traits and other similarities, marriage researchers say. But money-management styles are one case in which opposites do attract, said Jenny Olson, an assistant professor of marketing at Indiana University who studies couples’ financial decision-making.
We are drawn to people who can check and balance our own rigid rules about money, Prof. Olson said. Someone who feels they are too focused on saving and not focused enough on using money to enjoy life might look for a partner who can help them feel more comfortable with an occasional splurge.
Over the decades, however, spouses often grow more alike. The spendthrifts married to the tightwads manage to find some middle ground, learning from one another in the process, said Scott Rick, a marketing professor at the University of Michigan whose studies marital finances.
“The spouses who don’t converge have a harder time and those marriages are probably more fragile and could end in divorce,” Prof. Rick said, referencing his analysis of 1,303 couples, which will be published in a forthcoming book.
This mutual influence along with the built-in financial accountability couples get when they pool their assets are partly why married couples have a financial advantage over their single counterparts, researchers say. The median net worth of married couples 25 to 34 years old was nearly nine times as much as the median net worth of single households in 2019, up from four times as much in 2010, according to research from the Federal Reserve Bank of St. Louis.
When Kristen James, a 33-year-old product manager in Austin, Texas, first started dating her now-husband, Ben, a 35-year-old startup co-founder, she noticed they came to the relationship with different approaches to their finances. Mr. James considered himself much more of a financial risk-taker; Ms. James preferred to manage her money more conservatively.
Instead of their differences erupting in conflict, Ms. James said her husband’s approach had a positive influence. After talking it over as a couple, Ms. James made the leap to change her career, moving into the technology industry and ultimately earning a higher salary as a result. Without her husband’s encouragement, she said she wouldn’t have felt secure making such a huge life change.
“He said, ‘You’re worth far more than what you’re making,’ and he pushed me to take on more risk and challenge myself in different ways,” she said.
Couples who communicate about the differences in their financial beliefs are better able to make decisions together, as tedious as that practice may initially feel, said Matt Lundquist, a psychotherapist and the clinical director of Tribeca Therapy, a psychotherapy practice based in New York.
He points to clients who take a regular weekend trip and have made it a habit to use the driving time to discuss their finances. While the children snooze in the back of the car, the parents review the state of their budgets and check in on progress toward longer-term goals.
Talking as a pair also prevents an imbalance of power in which one partner appoints themselves money manager, said Adrian Ward, a marketing professor at the University of Texas at Austin.
In his own research looking at how couples manage their money, Prof. Ward found that one partner often takes charge of the finances, not because they’re better equipped to do so, but because they have more time for the job. The in-house money manager—whom Prof. Ward calls “the household CFO”—often shuts the other partner out of the decision-making. Sometimes, the other person is relieved, but over time, that partner’s financial literacy suffers.
“Even though it’s hard to make decisions together and we’re both busy, and it would be way easier for one of us to just do it, it’s the best long-term way to care for each other,” he said.
Marcella Mollon-Williams, a behavioural financial adviser based in Bowie, Md., runs a premarital financial counselling session for couples.
The main issue she sees early on in relationships: Couples too often talk about the things one partner wants the other to avoid doing with their money, as opposed to the things they want to do together.
“Talk about the desires money brings, the things you want to accomplish,” she said. “When you start dreaming together, identifying the things money can buy, it’ll become easier. It’s sort of looking ahead and then working backwards.”
To stay on the same page financially, Kristen and Ben James set a monthly family finance meeting. Talking about their goals, reviewing financial allocations and having time to connect on those topics helps them keep their sights trained on the bigger picture, Ms. James said.
When she’s tempted to scroll through Redfin real-estate listings, she relies on her husband to hold her accountable.
“We have each other to say ‘We’re not buying a new house right now’ or ‘We’re not buying a new car right now’—you have that other person to ground you,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
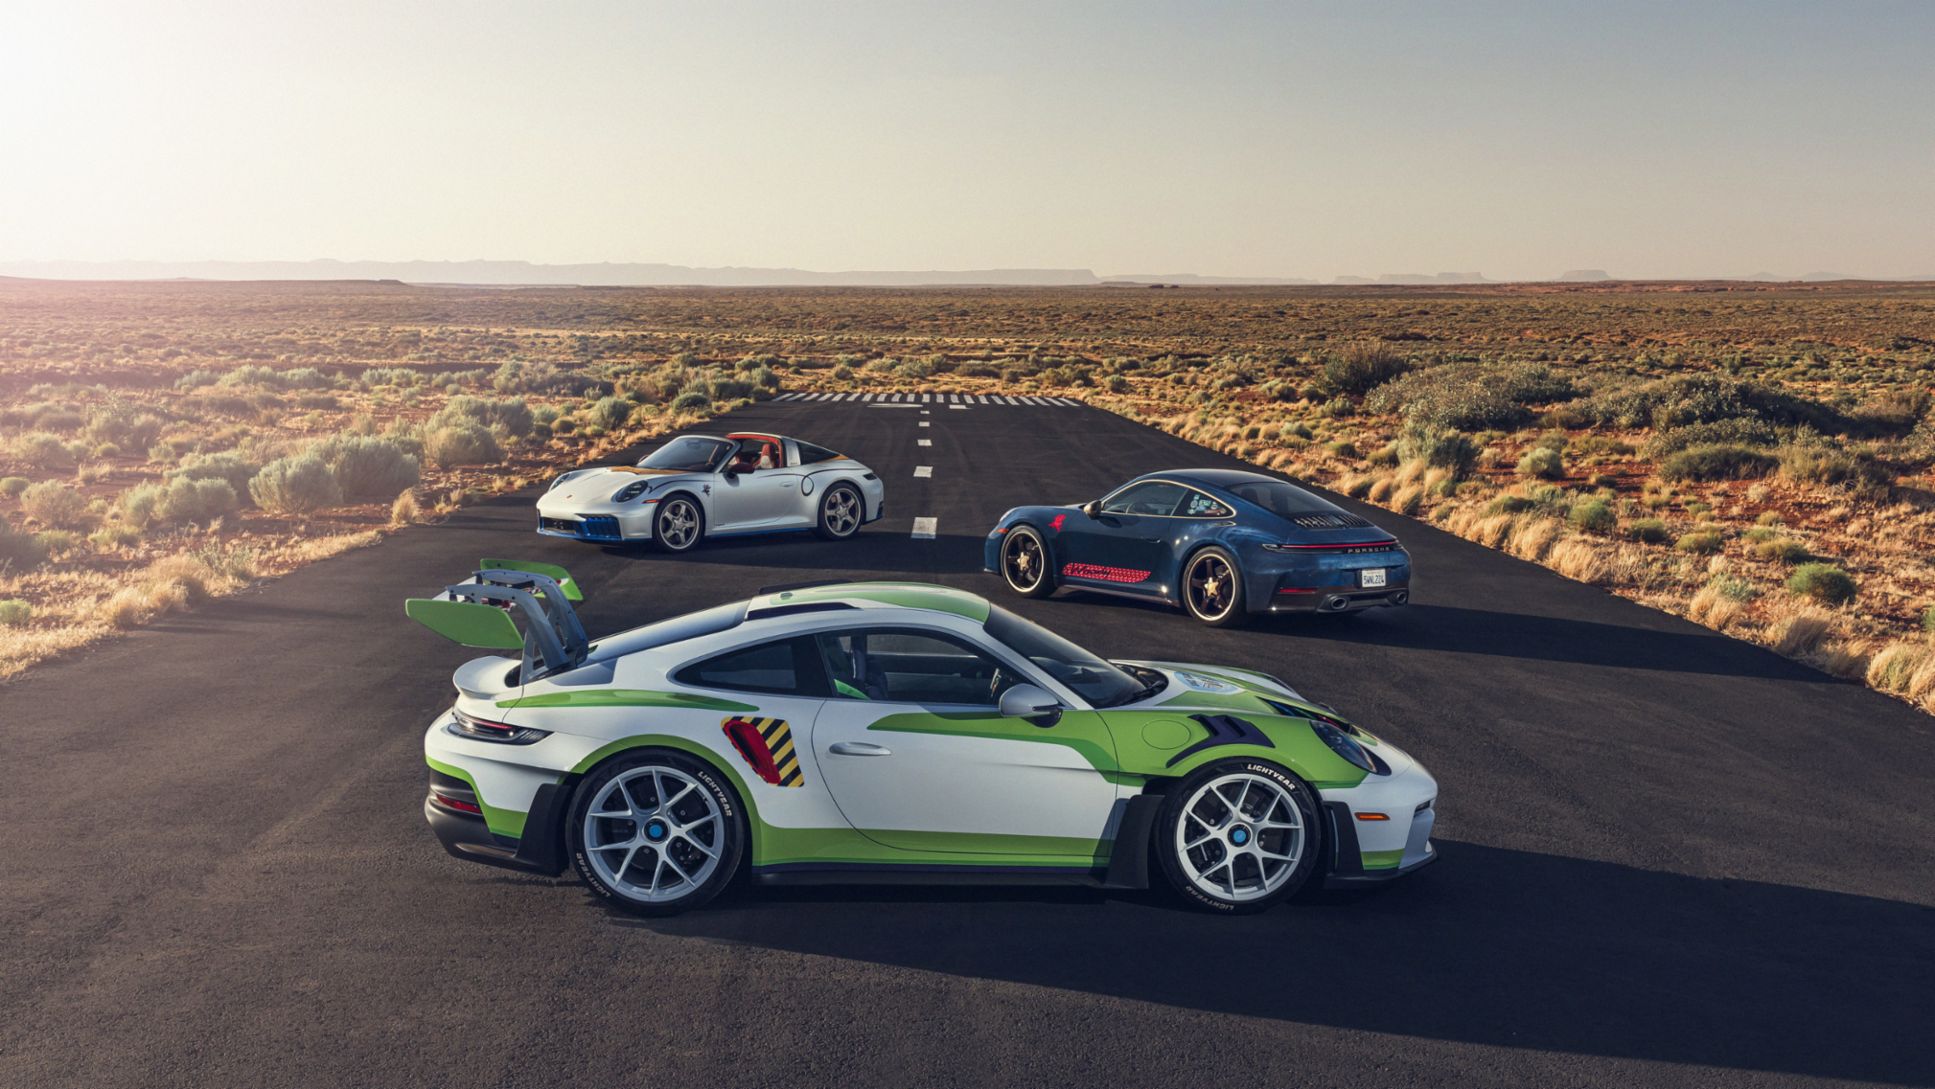
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min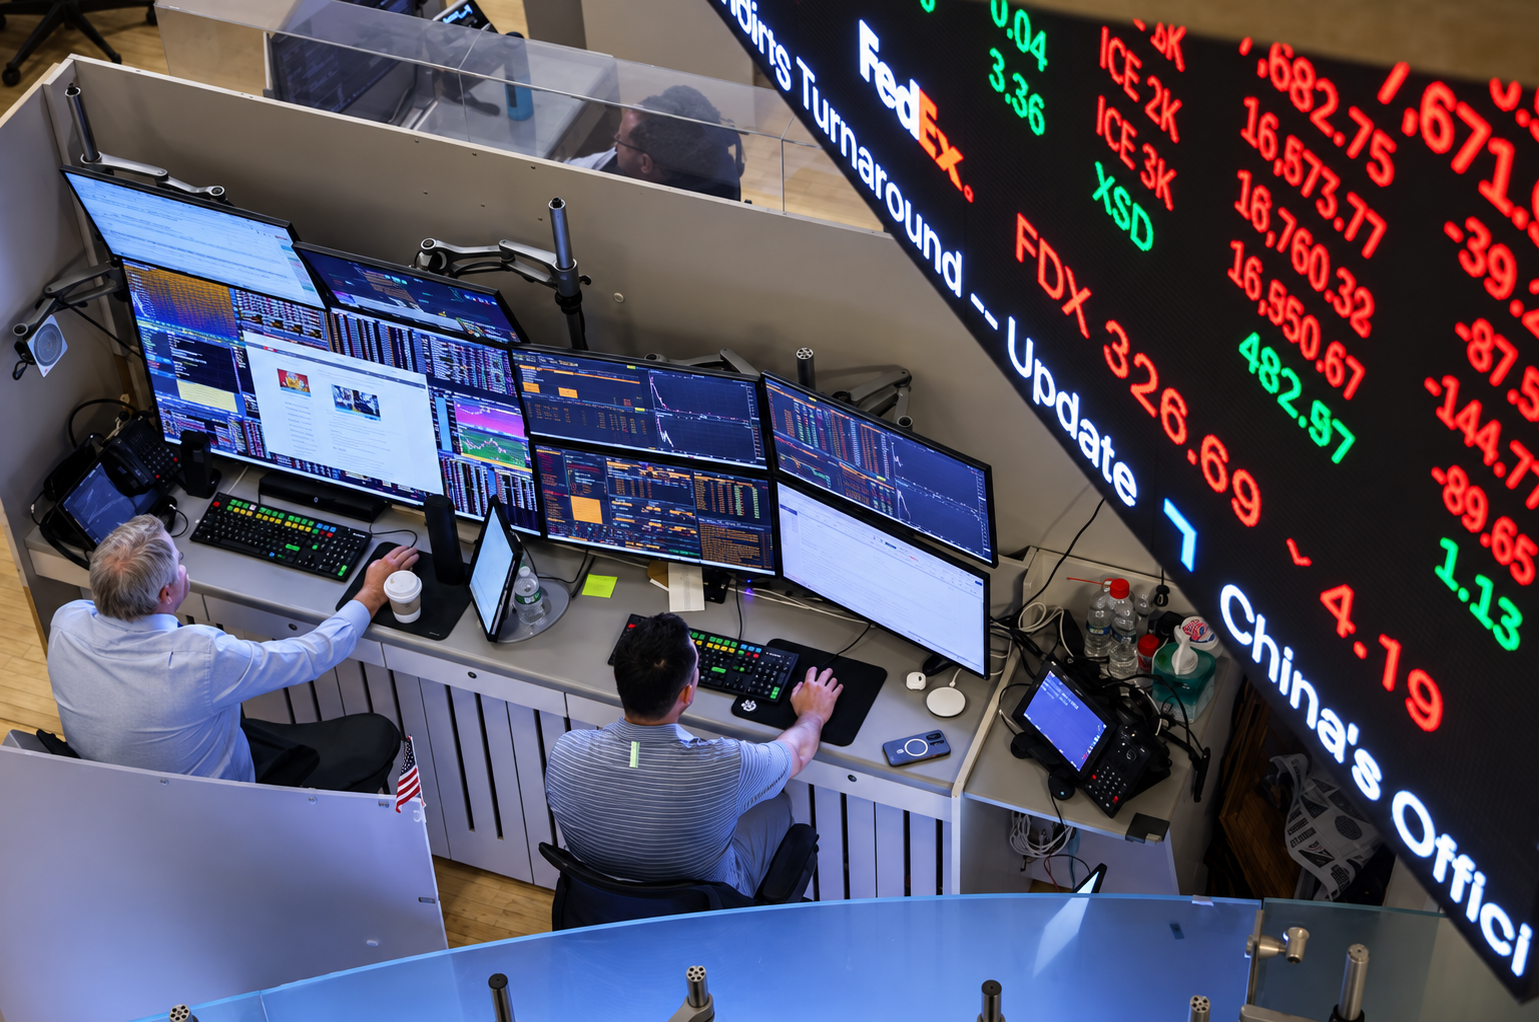
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”

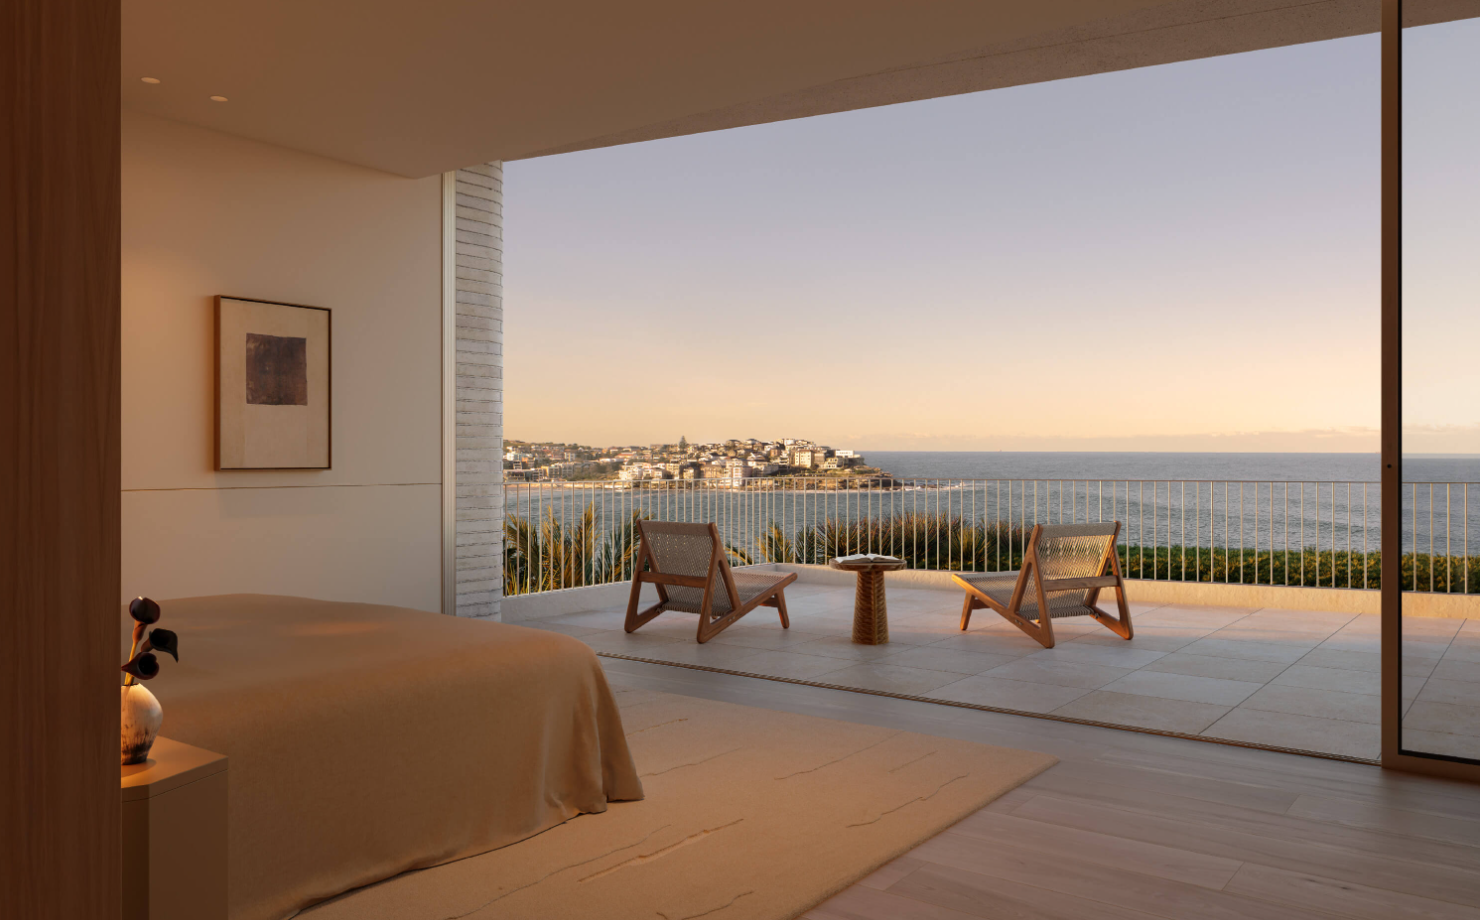
Warmer minimalism, tactile materials and wellness focused layouts are redefining luxury interiors as homeowners design for comfort, connection and lasting appeal.
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation