





China’s Housing Market Woes Deepen Despite Stimulus
Home prices declined at a faster pace in May in major cities, while other data show a mixed picture for the world’s second-largest economy

 4 min
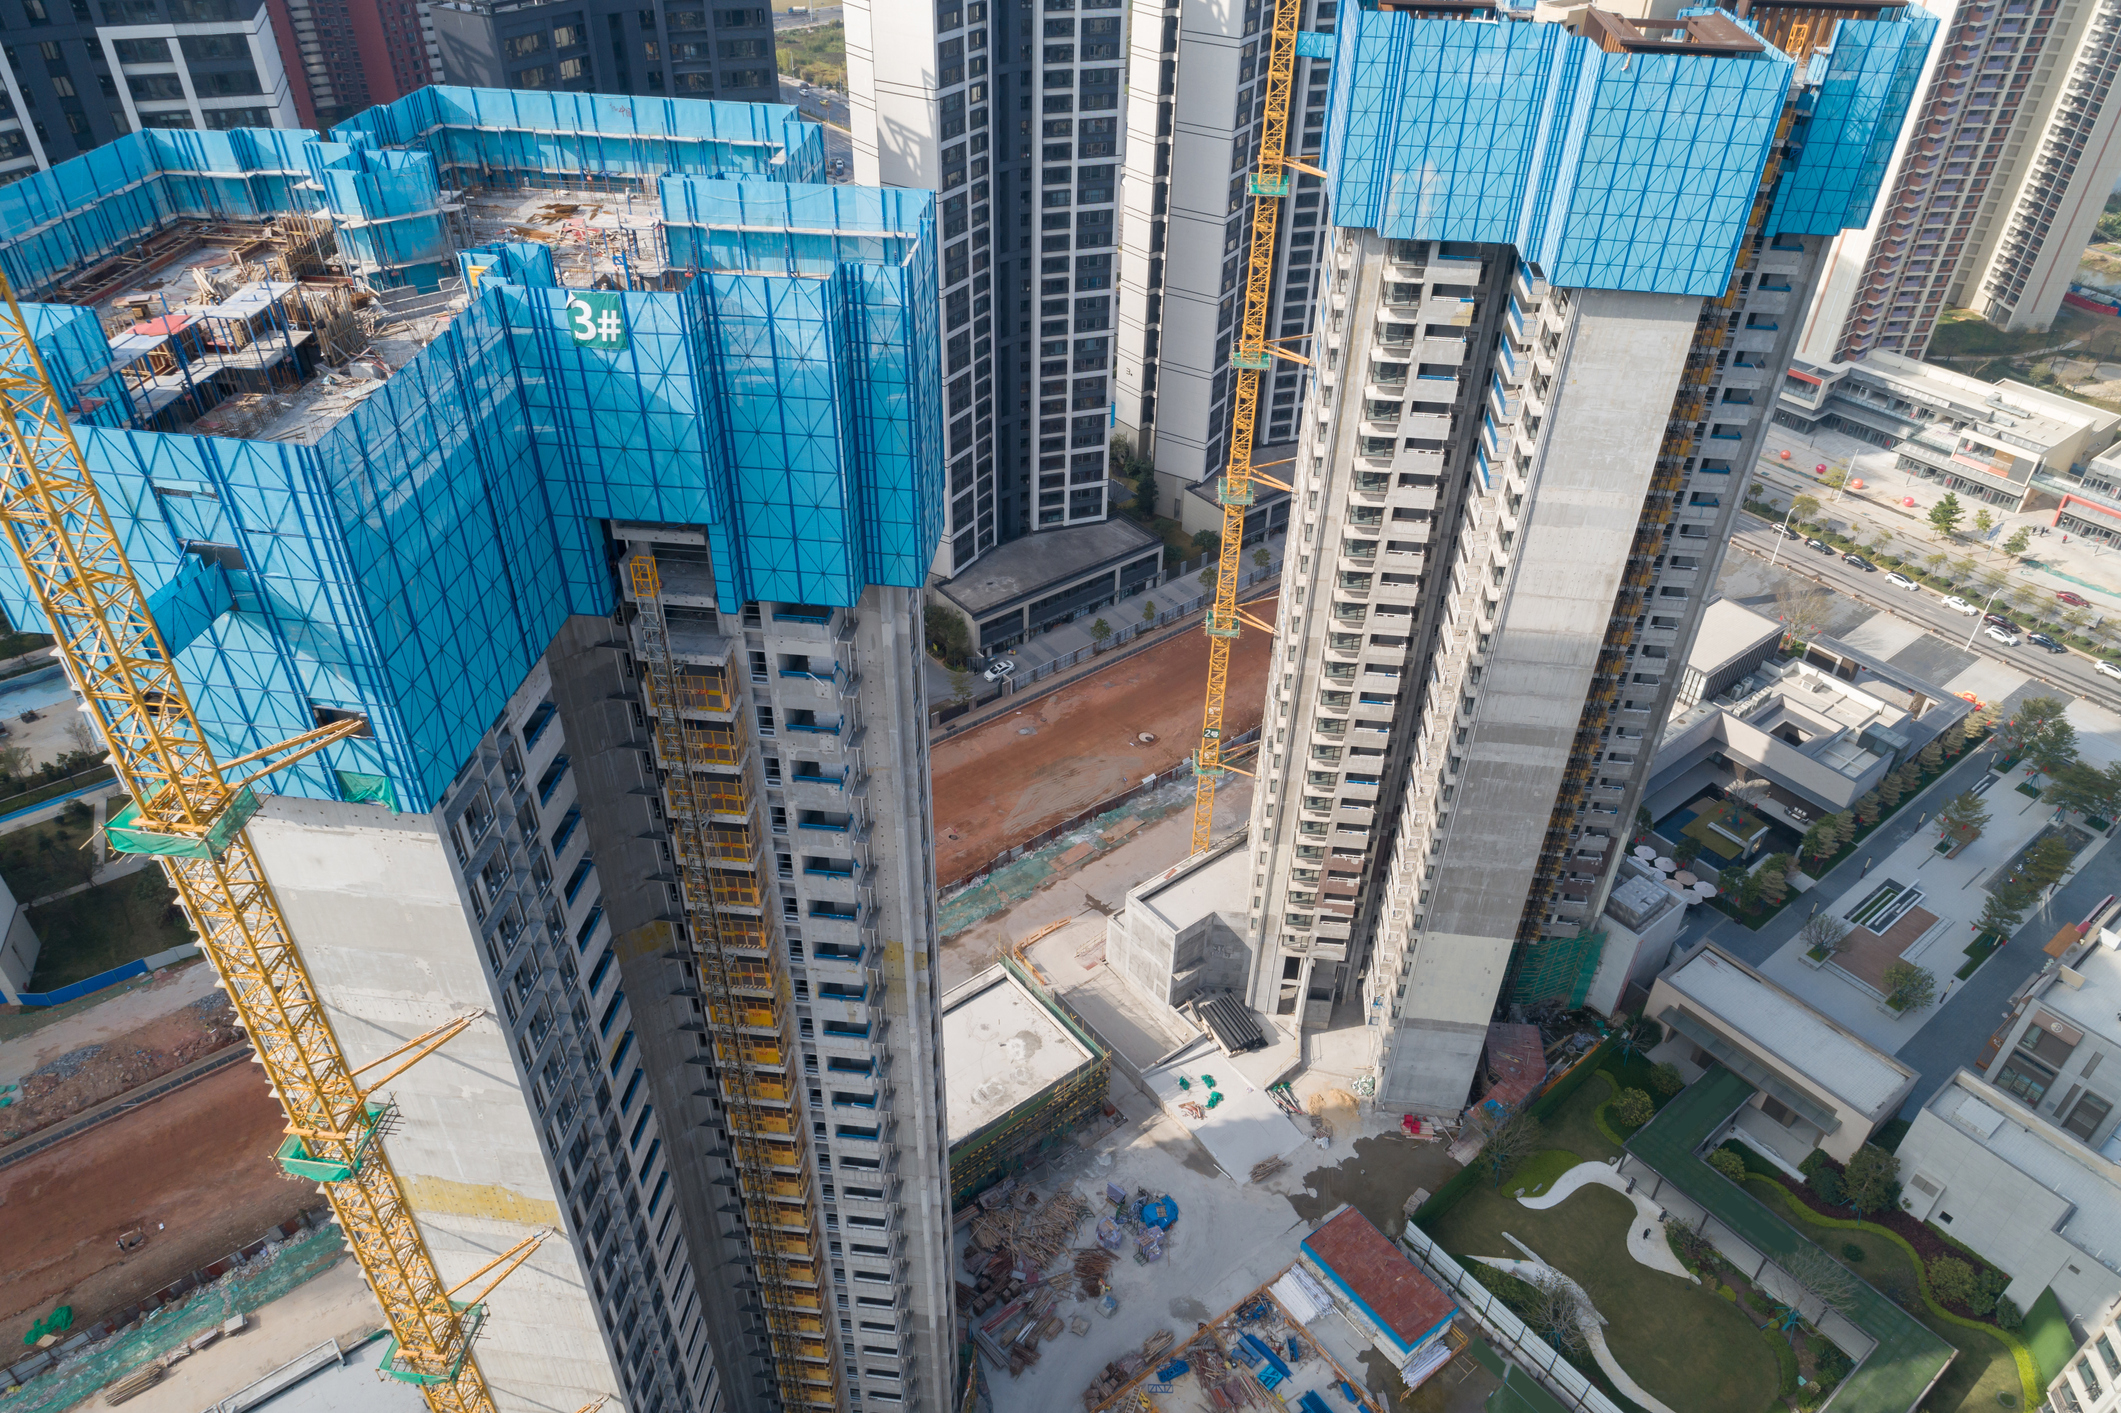
China’s broken housing market isn’t responding to some of the country’s boldest stimulus measures to date—at least not yet.
The Chinese government has been stepping up support for housing and other industries in recent months as it tries to revitalise an economy that has continued to disappoint since the early days of the pandemic.
But fresh data for May showed that businesses and consumers remain cautious. Home prices continue to fall at an accelerating rate, and fixed-asset investment and industrial production, while growing, lost some momentum.
“China’s May economic data suggest that policymakers have a lot to do to sustain the fragile recovery,” Yao Wei, chief China economist at Société Générale, wrote in a client note on Monday.
The worst pain is in the property sector, which has been struggling to deal with oversupply and weak buyer sentiment since 2021, when a multiyear housing boom ended . The market still doesn’t appear to have found a floor, even after Beijing rolled out its most aggressive stimulus measures so far in mid-May in hopes of restoring confidence.
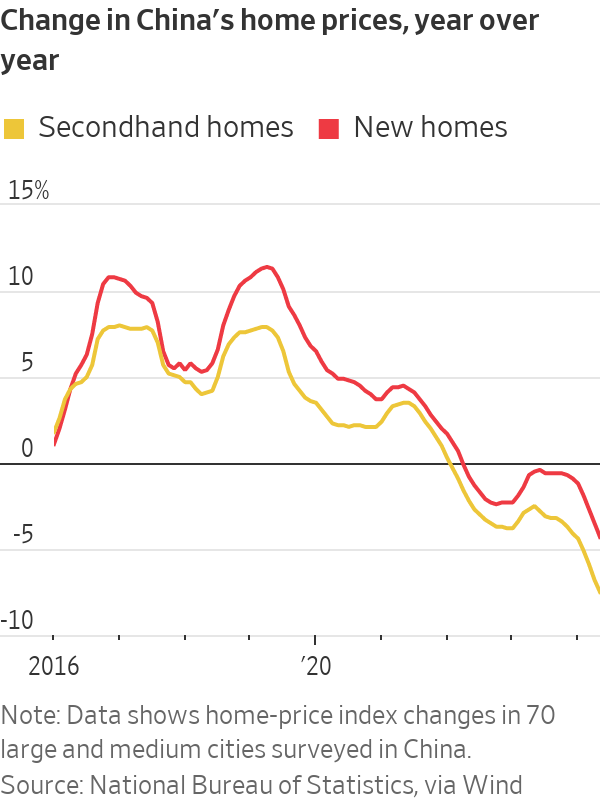
In major cities, new-home prices fell 4.3% in May compared with a year earlier, worse than a 3.5% decline in April, according to data released Monday by China’s National Bureau of Statistics. Prices in China’s secondhand home market tumbled 7.5%, compared with a 6.8% drop in April.
Home sales by value tumbled 30.5% in the first five months of this year compared with the same months last year.
“This data was certainly on the disappointing side and may ring some alarm bells, as May’s policy support package has not yet translated to a slower decline of housing prices, let alone a stabilisation,” said Lynn Song, chief China economist at ING.
Economists had also been hoping to see a wider recovery this month after Beijing started rolling out a planned issuance of 1 trillion yuan, the equivalent of $138 billion, in ultra-long sovereign bonds in May. The funds are designed to help pay for infrastructure and property projects backed by the authorities. Investors gobbled up the first batch of these bonds.
Monday’s bundle of economic data, however, underlined how the country still isn’t firing on all cylinders.
Retail sales, a key metric of consumer spending, rose 3.7% in May from a year earlier, compared with 2.3% in April, according to the National Bureau of Statistics. While the trend is heading in the right direction, it is still a relatively subdued level of growth, and below what most economists believe is needed to kick-start a major revival in consumer spending.
The expansion in industrial production—5.6% in May compared with a year earlier—was down from April’s 6.7% increase. Fixed-asset investment growth, of which 40% came from property and infrastructure sectors, also decelerated, to 3.5% year-over-year growth in May from 3.6% in April.
Key to the sluggish economic activity data in May—and China’s outlook going forward—is the crisis in the property market, which has proven hard for policymakers to address.
The property rescue package in May included letting local governments buy up unsold homes, removing minimum interest rates on mortgages, and reducing payments for potential home buyers. It also included as its centrepiece a $41 billion so-called re-lending program launched by the People’s Bank of China, which would provide funding to Chinese banks to support home purchases by state-owned firms.
The hope was that by stepping in as a buyer of last resort for millions of properties, the government would manage to mop up unsold housing inventory and persuade wary home buyers to re-enter the market. In turn, Chinese consumers, who have most of their wealth tied up in real estate, would feel more confident about spending again, thereby lifting the overall economy.
But the size of the re-lending program wasn’t big enough to convince home buyers, said Larry Hu , chief China economist at Macquarie Group. “Meanwhile, their income outlook also stays weak given the current economic condition,” he said.
For the property market to bottom out and reach a new equilibrium, mortgage rates, which stand at around 3-4% in China, need to be as low as rental yields, which are currently below 2% in major cities, said Zhaopeng Xing, a senior China strategist at ANZ. He said that a large mortgage rate cut will need to happen eventually.
The other key part of China’s push to revive growth revolves around the manufacturing sector, with leaders funnelling more investment into factories to boost output and reduce the country’s reliance on foreign suppliers of key technologies.
The result has been a surge in production. But with domestic consumption not strong enough to absorb all those goods, many factories have been forced to cut prices and seek out more overseas buyers.
Data released earlier this month showed that Chinese exports rose faster in May than the month before.
However, the export push is butting into resistance as governments around the world worry about the impact of cheap Chinese competition on domestic jobs and industries. The European Union last week said it would impose new import tariffs on Chinese electric vehicles, describing China’s auto industry as heavily subsidised by the government, to the point where other countries’ automakers can’t fairly compete.
The U.S. has also hit Chinese cars and some other products with hefty duties, while countries including Brazil, India and Turkey have opened antidumping investigations into Chinese steel, chemicals and other goods.
Beijing says such moves are protectionist and that its industries compete fairly with global rivals.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.
As interest rates, inflation and market sentiment fluctuate, investors are being urged to focus on data, not panic.
From warmer neutrals to tactile finishes, Australian homes are moving away from stark minimalism and towards spaces that feel more human.


